Sign in to fuzzto save your conversations, follow your research and come back anytime.

Punjab National Bank (PNB) is a state-owned commercial bank headquartered in New Delhi, India. It offers a wide range of banking products and services, including retail and corporate banking, international banking, and capital market services. PNB has an extensive network of over 10,000 branches and 12,000 ATMs across India. The bank provides personal and corporate loans, deposit accounts, forex services, cash management, and various digital banking solutions. PNB also offers insurance products, mutual funds, and merchant banking services. As of March 31, 2024, PNB's global business stood at Rs. 23,53,038 Crore, with deposits of Rs. 13,69,713 Crore and CASA deposits of Rs. 5,52,499 Crore. The bank has overseas presence through branches and representative offices in several countries.
In the news
PNB targets 17-18% retail loan growth, 21% MSME growth this quarter
PNB Q2 FY27: Profit Growth, Asset Quality, and Capital Strength
PNB Q2 Net Profit Jumps 13% to Record ₹5,532 Cr, Eyes ₹6,000 Cr Target
RBI Hikes Repo Rate to 5.5% - Major Banks Raise Loan Rates
HDFC Bank's Q2FY27: Deposit Surge, Loan Growth, and the PSU Rally
Banks Sweeten Festive Offers as Retail Loan Campaigns Launch

PNB Q2 Update: Global Business Crosses ₹31 Lakh Crore
CBI arrests Nirav Modi associate after UAE extradition
Bank Strike September 28-30: PSBs Open Sunday, Govt Advances Salaries
PNB accelerates wealth management launch, targets December rollout
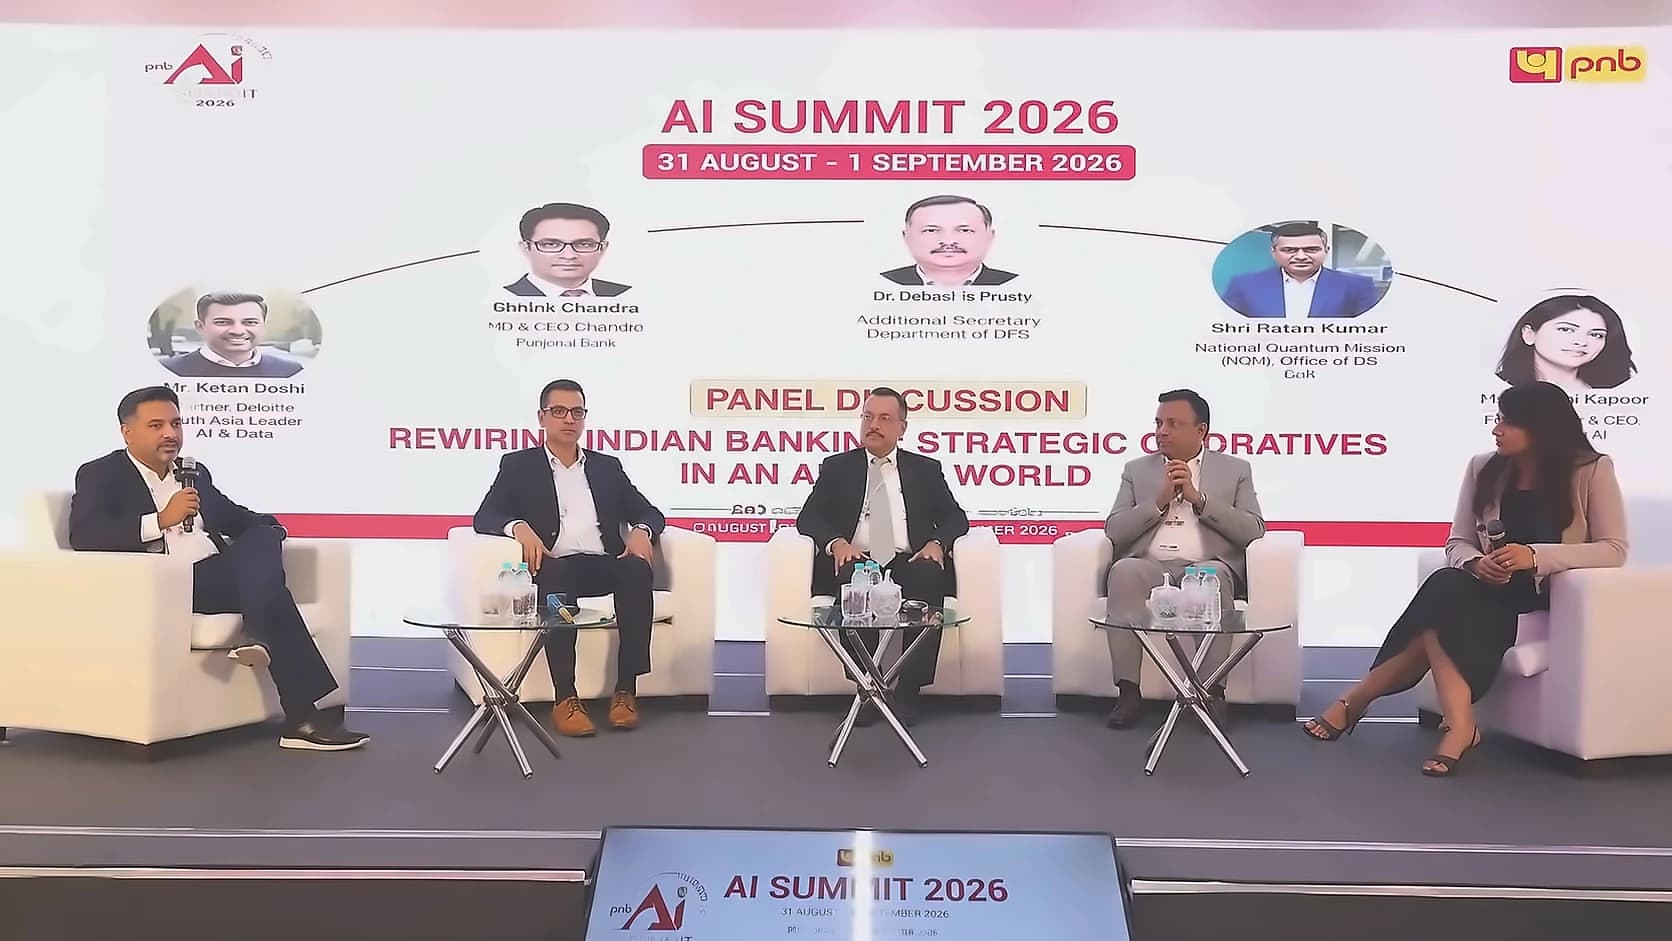
PNB Maintains 8.80% MCLR, Targets $2.5B FCNR Deposits Amid AI Investment

PNB Plans Haryana Gramin Bank Listing in Q4FY27
6 stocks experts recommend for short-term gains amid market volatility
PNB to close inactive accounts by September 13, 2026
PNB Q1 FY27: Profit Surge, Margin Pressure, and Asset Quality Turnaround
PNB's Rs 30 Lakh Crore Milestone: Why the Stock Still Slipped 3%
PSB Consolidation and FDI Liberalization: A New Era for Indian Banking
PSB Consolidation: From 27 to 5 Banks, What's at Stake?
PSB Consolidation: The Road to Global Competitiveness
PNB's AI Revolution: From Data Analytics to Corporate Lending Powerhouse
The Quarter story
The two most recent quarterly results, compared side-by-side.
PNB strengthens asset quality and profitability while managing deposit mix and retail loan cycles.
Agriculture Gross NPA ratio falls from 10.77% to 9.07% from Q1 to Q4 FY26, reflecting steady credit quality improvement.
CASA share dips from 38% to 37.1% from Q1 to Q3 FY26, indicating a shift toward higher-cost term deposits.
Consolidated Gross NPA ratio drops from 3.45% to 2.68% from Q2 to Q4 FY26, stabilizing at 2.78% in Q1 FY27.
Domestic NIM compresses from 2.84% to 2.61% from Q1 to Q4 FY26, recovering slightly to 2.64% in Q1 FY27 amid rate normalization.
MSME advances grow from ₹169,426 Cr to ₹203,025 Cr from Q1 FY26 to Q1 FY27, driving inclusive lending expansion.
Corporate advances peak at ₹582,834 Cr in Q4 FY26 before contracting to ₹515,372 Cr in Q1 FY27, signaling portfolio rebalancing.
Return on equity rises from 6.59% to 18.00% from Q1 to Q4 FY26, maintaining strong capital efficiency at 17.33% in Q1 FY27.
Retail advances fall from ₹281,988 Cr to ₹257,064 Cr from Q3 FY26 to Q1 FY27, reflecting natural loan maturity cycles.
Cost to income ratio improves from 55.31% to 48.42% from Q1 to Q4 FY26, reflecting better operational efficiency.
Retail SMA 2 accounts climb from 43 to 111 from Q1 FY26 to Q1 FY27, requiring closer monitoring to prevent future slippages.
Company insights, generated from the most recent coverage.
The 85% provision cut did not touch PNB's cost-to-income ratio at all — provisions sit below operating profit. It only lifted pre-tax profit ~13% to ₹7,435 cr against 4.2% operating profit growth.
Provisions fell from ~8.9% of PNB's operating profit to ~1.3% (₹643 cr to ₹97 cr). That gap cannot repeat, so from Q3 the bank has to grow profit off operations alone.
PNB's FY27 IT and digital budget of ~₹3,400 cr — new data centre plus AI tools — locks other operating expenses at an elevated level even as staff costs fall, capping how far the cost-to-income ratio can compress.