Sign in to fuzzto save your conversations, follow your research and come back anytime.

CESC Limited is an integrated power utility company primarily engaged in the generation and distribution of electricity. It operates in Kolkata and surrounding areas of West Bengal, covering 567 square kilometers with 3.5 million customers. The company has three generating stations with a total capacity of 1,125 MW. Through subsidiaries, CESC distributes power in Greater Noida, Uttar Pradesh, and operates distribution franchises in Kota, Bharatpur, and Bikaner in Rajasthan, as well as in Malegaon, Maharashtra. The company also owns and operates thermal power plants outside Kolkata, generating 885 MW. CESC's operations span the value chain from coal mining to power generation and distribution. Its subsidiaries include Haldia Energy Limited, Malegaon Power Supply Limited, and Bhadla Three SKP Green Ventures Private Limited.
In the news

BNP Paribas Turns Bullish on Power Stocks with Up to 57% Upside

Prabhudas Lilladher maintains ₹220 CESC target amid renewable expansion
CESC Q1 Results: Net Profit Up 3.88% YoY, ₹6 Dividend Declared
CESC unit acquires 1.4 GWp ReNew Solar companies for ₹4,859 crore
CESC's Purvah Green wins 175 MW wind project at ₹3.85/kWh
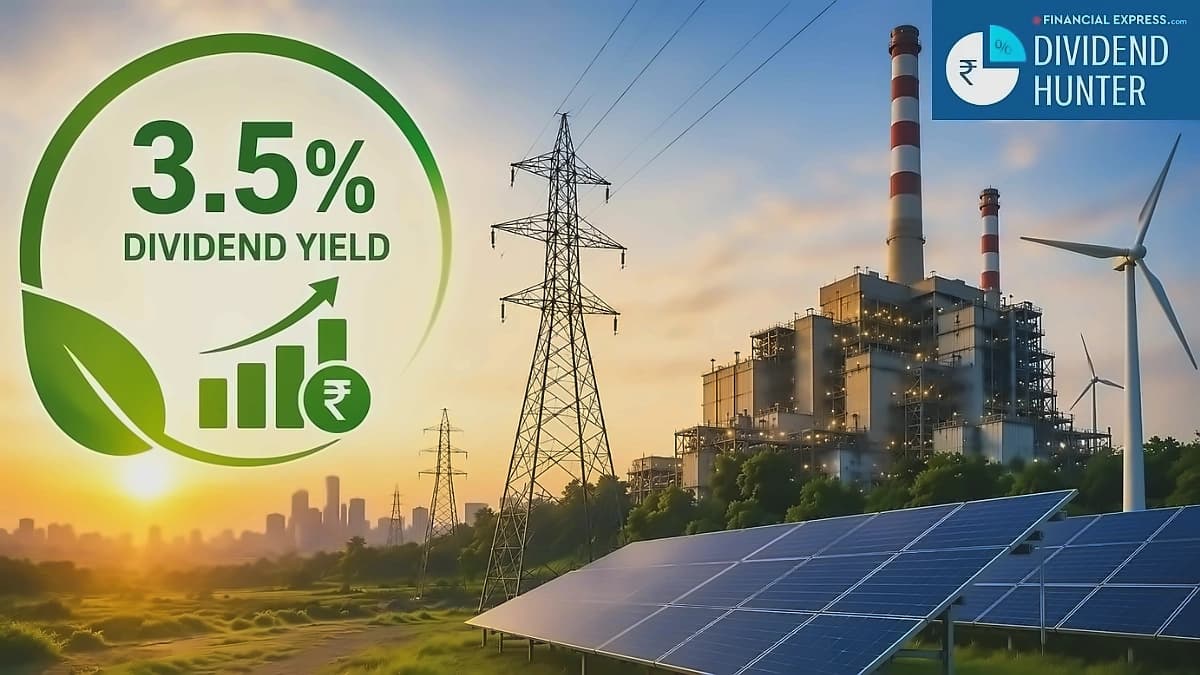
CESC offers 3.5% dividend yield with ₹4,057 cr cash flow
Stocks under ₹200: Anand Rathi's 3 picks amid market volatility

CESC hits 52-week high at ₹197.25 on strong earnings, renewable push

ICICI Lombard schedules May 27 analyst meet, allots 103K shares

Bengal stocks surge up to 10% on BJP victory, experts warn rally won't last

CESC signs 600 MW wind-solar hybrid deals at ₹3.75/kWh
CESC awards 600 MW wind-solar hybrid projects to four firms
The Quarter story
The two most recent quarterly results, compared side-by-side.
CESC Ltd delivers stronger profitability and better grid efficiency in Q4 FY26, driven by higher thermal plant utilization and reduced transmission losses across key distribution circles.
Consolidated EBITDA grows from ₹1,036 Cr to ₹1,274 Cr from Q3 to Q4 FY26, reflecting stronger operational profitability.
T&D losses in Noida Power rise from 5.5% to 6.95% from Q3 to Q4 FY26, indicating grid inefficiencies in that circle.
Thermal plant load factors improve, with Budge Budge rising from 74% to 83% and Haldia Energy from 87% to 95% in Q4 FY26.
Cost of fuel increases from ₹852 Cr to ₹976 Cr from Q3 to Q4 FY26, adding pressure on generation margins.
Profit after tax increases from ₹304 Cr to ₹459 Cr in Q4 FY26, supported by higher power generation volumes.
Crescent Power EBITDA drops from ₹36 Cr to ₹21 Cr in Q4 FY26, signaling weaker profitability at that thermal asset.
Southern Generating Station utilization jumps from 2% to 65% in Q4 FY26, bringing idle capacity back online.
Malegaon DF T&D loss remains high at 32.67% in Q4 FY26, down only slightly from 35% in Q3 FY26.
Consolidated revenue grows from ₹4,099 Cr to ₹4,192 Cr from Q3 to Q4 FY26, showing steady top-line expansion.
Cost of electricity purchased rises from ₹1,475 Cr to ₹1,505 Cr from Q3 to Q4 FY26, tightening distribution margins.
Company insights, generated from the most recent coverage.
90% PPA concentration with SECI reduces overall counterparty risk compared to a diversified portfolio with lower-quality private or state DISCOMs, despite apparent lack of diversification.
Deal includes ₹230 crore contingent payment for change-in-law claims, excluded from base EV of ₹4,859 crore, deferring cash outflows until regulatory compensation is realized.
Contracted capacity increase to 4.8 GWp enhances bargaining power with suppliers and offtakers, enabling better tariff negotiations and supply chain resilience.