The Income-tax Act, 2025, came into effect from 1 April 2026, meaning it will apply to income-tax returns filed in 2027 for tax year 2026-27. According to reports from Mint, while income-tax rates remain unchanged, several section references, forms, and reporting requirements have changed significantly. Isha Sekhri, Founder of Isha Sekhri & Associates LLP, has identified key changes in section references from the Income-tax Act, 1961, to the Income-tax Act, 2025.
As reported by Mint, the most significant changes include salary-related sections being renumbered from 17(1), 17(2) to 16, 17. The standard deduction has been increased to ₹75,000/₹50,000 under section 19, while gratuity, leave encashment, and commuted pension are now covered under section 19(1) table. TDS forms have been renumbered from 192, 194-series, 206C to 392, 393, 394, and capital gains sections have been renumbered from 111A, 112, 112A to 196, 197, 198. The default regime applies under section 202, with non-business filers able to switch regimes each year in their ITR.
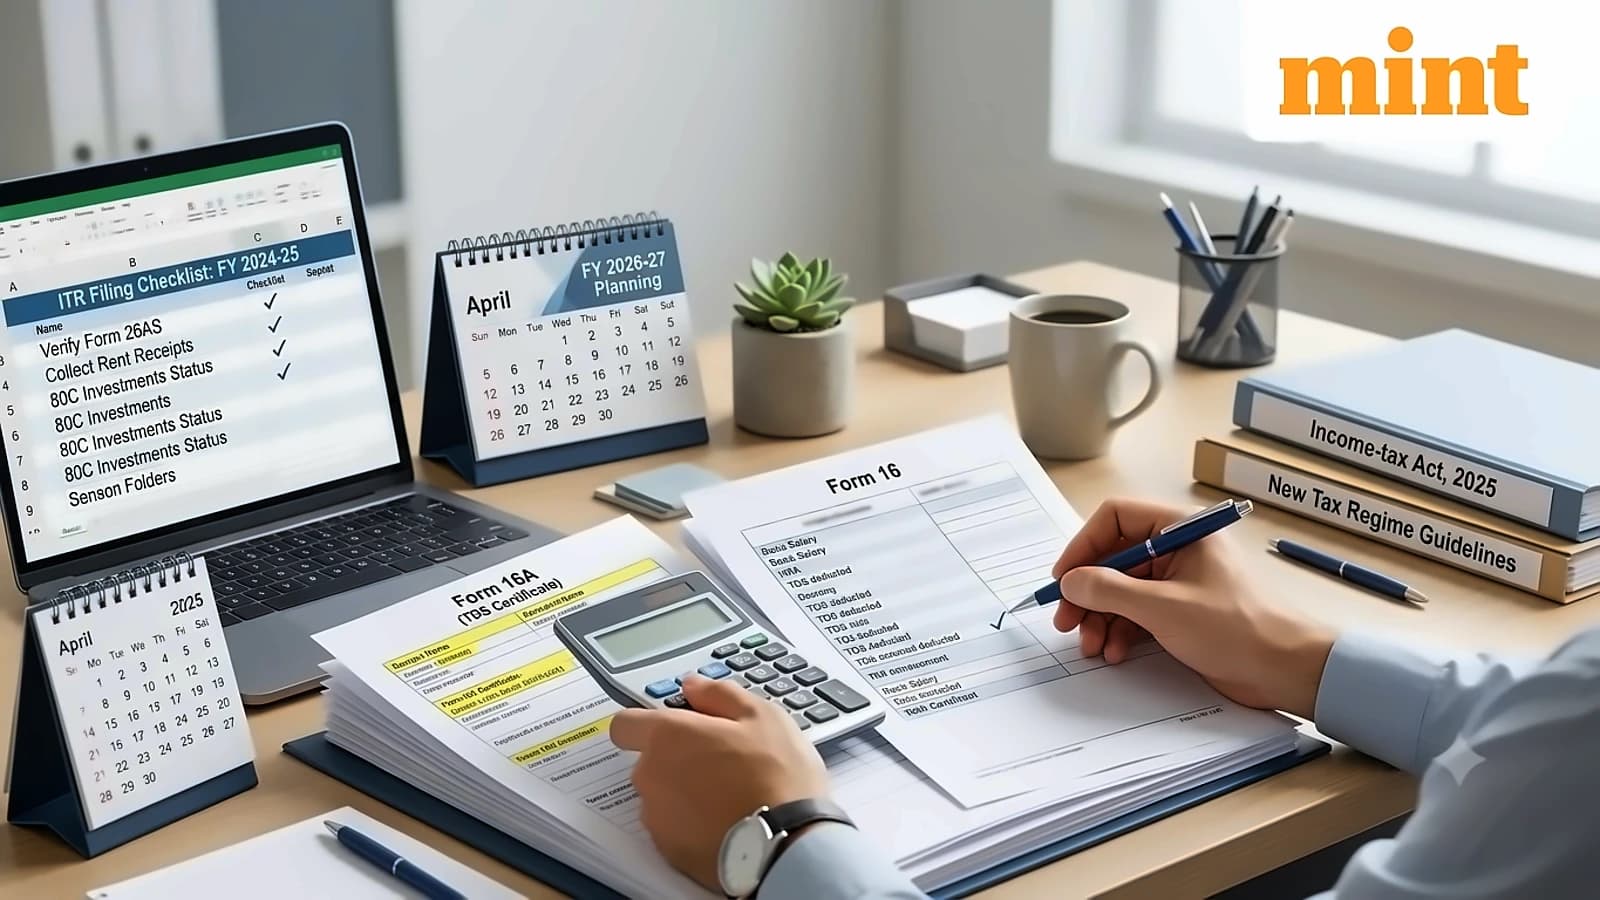
According to Mint reports, taxpayers should confirm their tax regime selection in payroll TDS, ensuring the default regime applies unless Form 122 is submitted. They should check HRA city classification and landlord details in Form 124, keep rent agreements and receipts on record, and compare Form 124 with submitted proof documents. Taxpayers should reconcile Form 168 (new Form 26AS) and AIS with payslips, verify interest, dividend, and broker-provided capital gains statements, and ensure salary and TDS from previous employers are correctly reported to new employers.
As reported by Mint, the key change is in tax form numbering, with Form 16 being replaced by Form 130 for TDS certificates. Form 12BB/12BA has been replaced by Form 124/123, where Form 124 covers employee declarations and Form 123 details perquisites. Form 26AS has been replaced by Form 168 as the annual tax-credit statement. Taxpayers should ensure TDS returns carry new Section 392/393 codes and Form 130 reflects 2025 Act references, as incorrect codes could cause problems with tax-credit matching. The July-September TDS return is due by 31 October.
According to Mint reports, taxpayers should prepare this year's tax computation using the 2025 Act structure and compare the two tax regimes before the March payroll cut-off. For filing ITR under Section 263, the due date of 31 July stays the same. Brought-forward losses will continue with existing character and without a fresh carry-forward period under the new IT Act. Taxpayers should retain proofs, copies of Forms 122 and 124, and AIS snapshots together, and take opening balances from the carry-forward schedule of their AY 2026-27 return.