The Mumbai bench of the Income Tax Appellate Tribunal (ITAT) has ruled in favor of a taxpayer who successfully challenged a ₹17.18 lakh penalty imposed by the tax department. According to reports from The Times of India, the taxpayer had not filed an income tax return for assessment year 2016-17, and the department subsequently completed a reassessment without his participation. On February 15, 2024, the department assessed his total income at ₹55.62 lakh, treating the amount as unexplained cash deposits in a bank account attributed to him.
The critical issue centered on whether the tax officer could legally impose a penalty under Section 271(1)(c) when the assessment order had recorded the initiation of proceedings under other provisions. As reported by The Times of India, the assessment order referred to Section 68 at one point and later treated the amount as unexplained money under Section 69, while also directing tax to be charged under Section 115BBE. The officer recorded that penalty proceedings were being initiated under Sections 271AAC and 272A(1)(d), but the tax department imposed the penalty under Section 271(1)(c), which deals with concealment of income or furnishing inaccurate particulars of income.
The tribunal's finding was straightforward: the assessment order mentioned Sections 271AAC and 272A(1)(d), but contained no corresponding direction to initiate penalty proceedings under Section 271(1)(c). According to The Times of India, Section 271(1B) provides for deemed satisfaction in specified circumstances where an assessment order contains a direction to initiate penalty proceedings under Section 271(1)(c), but the necessary direction was missing in this case. The tribunal held that the officer could not simply switch to a different penalty provision later, as Sections 271AAC and 271(1)(c) are distinct provisions.
Amit Gupta, Partner at Saraf and Partners, explained to The Times of India that the judgment emphasizes the rule of law regarding distinction between penalty proceedings versus underlying assessment proceedings. He noted that proceedings for imposition of penalty, though emanating from assessment, are independent, and the taxpayer can challenge the validity of penalty proceedings independently. Gupta emphasized that the existence of conditions stipulated in Section 271(1)(c) are essential for initiation of penalty proceedings, and such existence should be clearly reflected in the underlying assessment order.
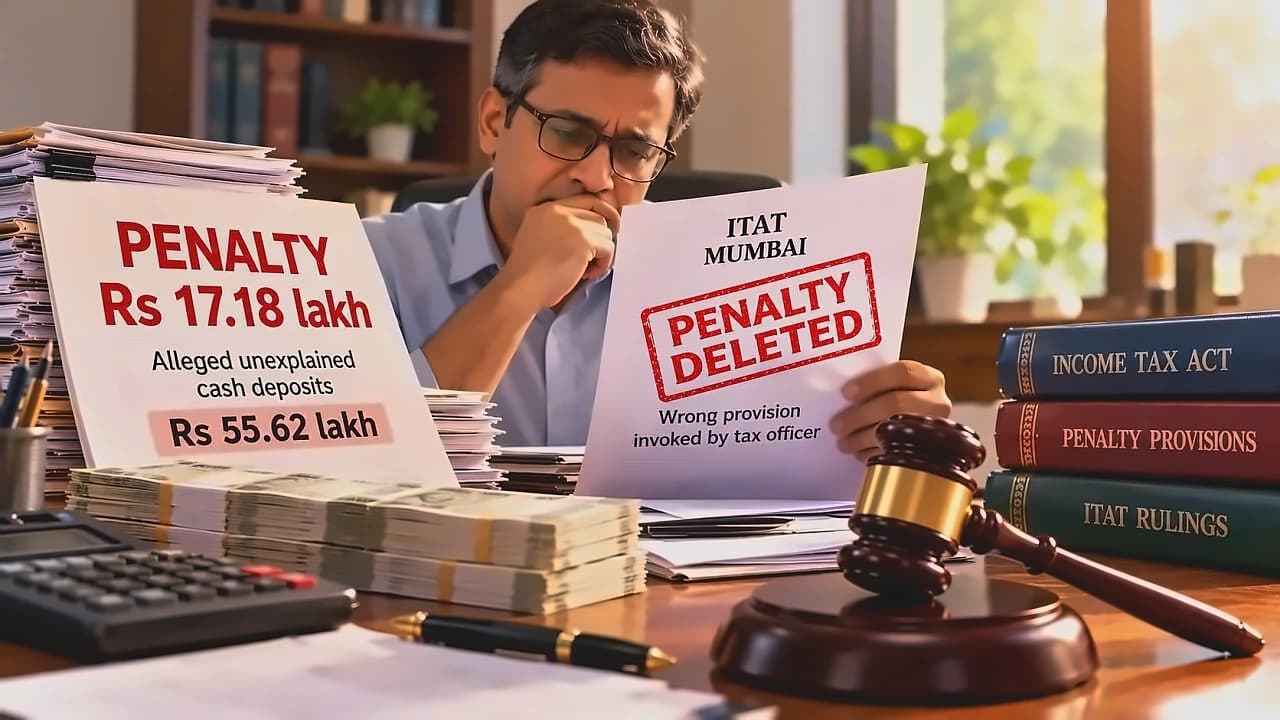
The tribunal explained that the validity of the penalty was a separate question from whether the ₹55.62 lakh addition would ultimately stand. According to The Times of India, the tribunal deleted the penalty of ₹17.18 lakh without waiting for the pending appeal over the addition, since the penalty could not survive without valid initiation under Section 271(1)(c). The decision is limited to the penalty challenge and does not establish that the cash deposits were wrongly treated as income or that the disputed bank account did not belong to the taxpayer.