India's tax system has undergone a comprehensive transformation since the 1991 economic reforms, when then Finance Minister Manmohan Singh implemented significant changes to simplify the tax structure. According to reports from Business Standard, the peak personal income tax rate was reduced from nearly 56% in 1991 to 40% in 1992-93, and further to 30% in 1997-98. Corporate tax rates were similarly reduced from the 40-50% range to a uniform 40% in 1994-95 and 35% in 1997-98. The Raja Chelliah Tax Reforms Committee, established in August 1991, provided the foundation for these reforms by recommending lower tax rates, broader tax base, and simpler tax structures.
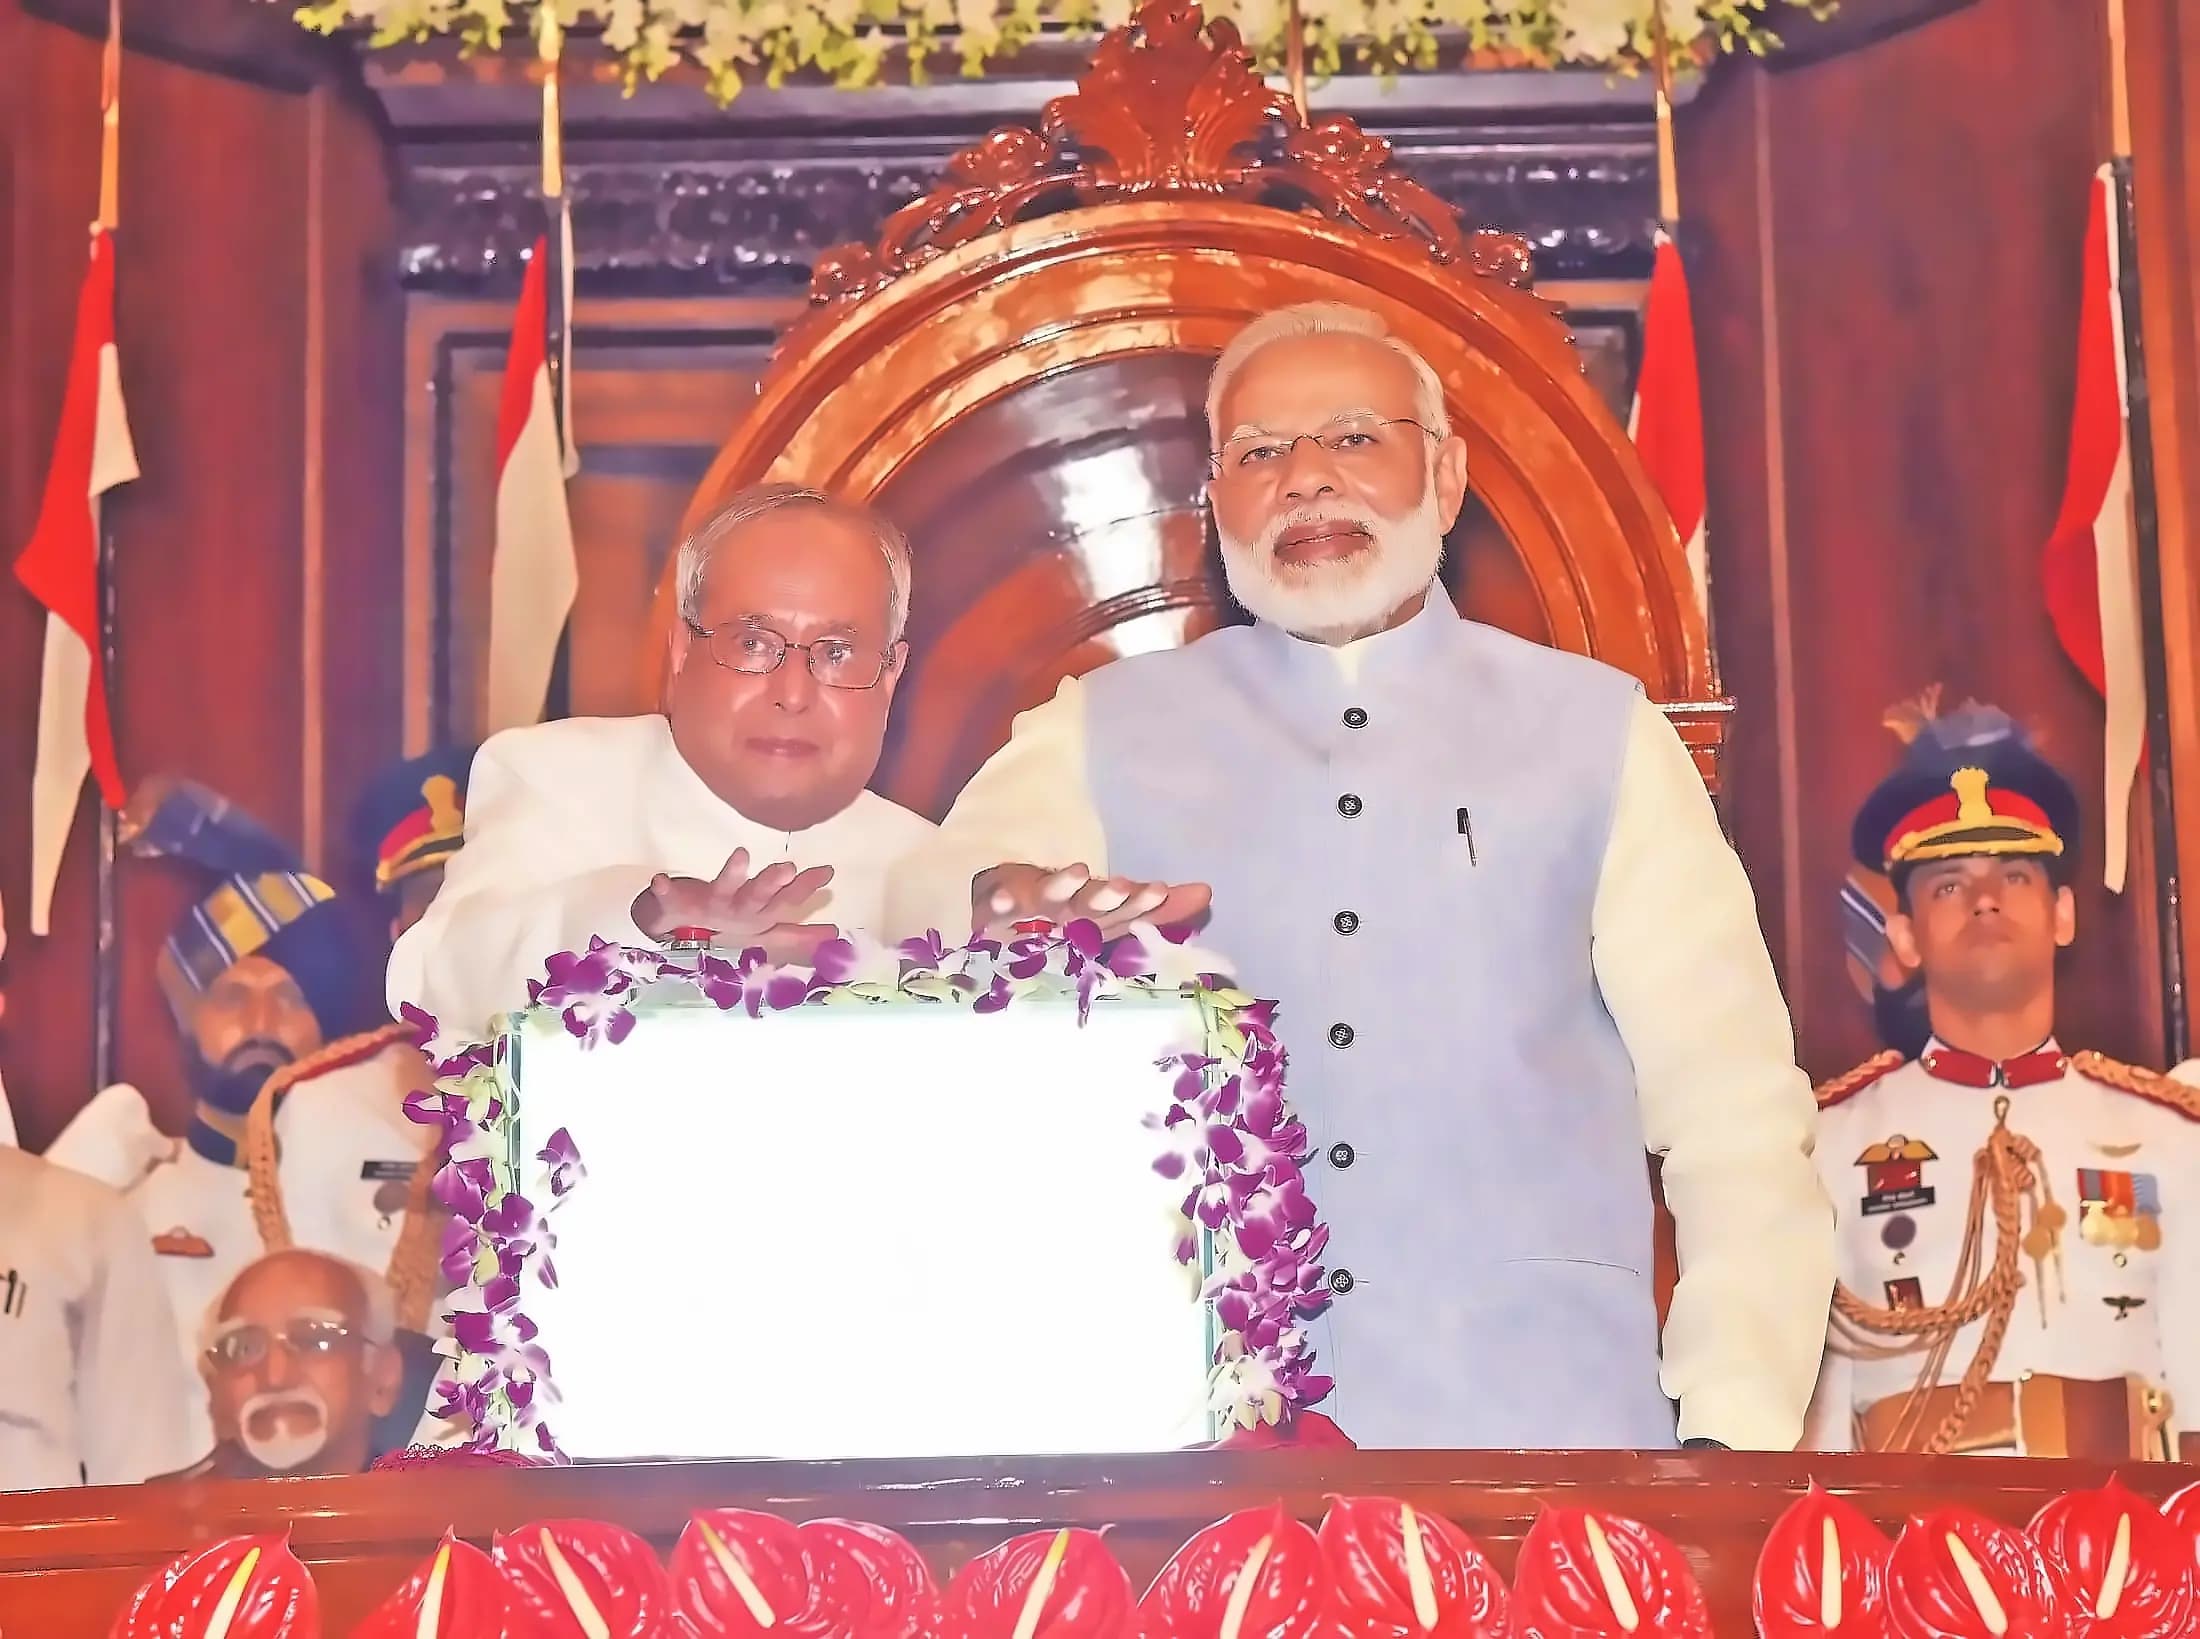
The most significant indirect tax reform came with the Goods and Services Tax (GST) rollout on July 1, 2017, which replaced the fragmented tax system with a common national framework. As reported by Business Standard, GST registered taxpayers increased from 6.7 million before GST to over 1.5 crore, reaching about 1.65 crore by mid-2026. The GST Council, established through constitutional amendments in 2016, enables joint decision-making between the Centre and states on rates, exemptions, and major policy matters. In September 2025, the GST Council carried out major rate rationalisation, bringing most goods and services under 5% and 18% slabs, while maintaining a higher 40% special rate for luxury and sin goods.
The reforms have significantly improved tax collection efficiency and compliance. According to Business Standard reports, direct tax revenue receipt as a share of GDP has increased from around 2% in the early 1990s to about 6% in recent years. The number of income-tax returns has grown to over 80 million. The latest milestone is the Income Tax Act, 2025, which came into force on April 1, 2026, rewriting the six-decade-old Income Tax Act, 1961, in a simpler and more organized manner. The new Act reduces the number of sections from around 819 to 536, using simpler language, tables, and formulas to improve understanding.
Despite significant progress, experts identify key areas requiring further attention. As reported by Business Standard, the unfinished agenda includes clearing the backlog of pending tax appeals and dealing with old tax demands that can no longer be collected. On the indirect tax side, experts suggest the next phase should focus on making GST compliance easier for businesses, with major policy changes ideally effective from April to align with the financial year. The GST structure needs further simplification, with experts arguing that multiple tax slabs create classification disputes and increase compliance costs. Additionally, bringing petroleum products, Aviation Turbine Fuel, and natural gas under GST remains a priority.
Technology has emerged as a major driver of tax administration improvements. According to Business Standard reports, electronic filing, PAN-Aadhaar linkage, pre-filled income tax returns, and data analytics have enhanced compliance and strengthened enforcement. Faceless assessment, introduced in 2019, reduced direct interaction between taxpayers and tax officers. The government has also implemented the General Anti-Avoidance Rule (GAAR) from April 1, 2017, to deny arrangements whose main purpose is tax benefit, with recent amendments in March 2026 clarifying its application to investments made before April 1, 2017.