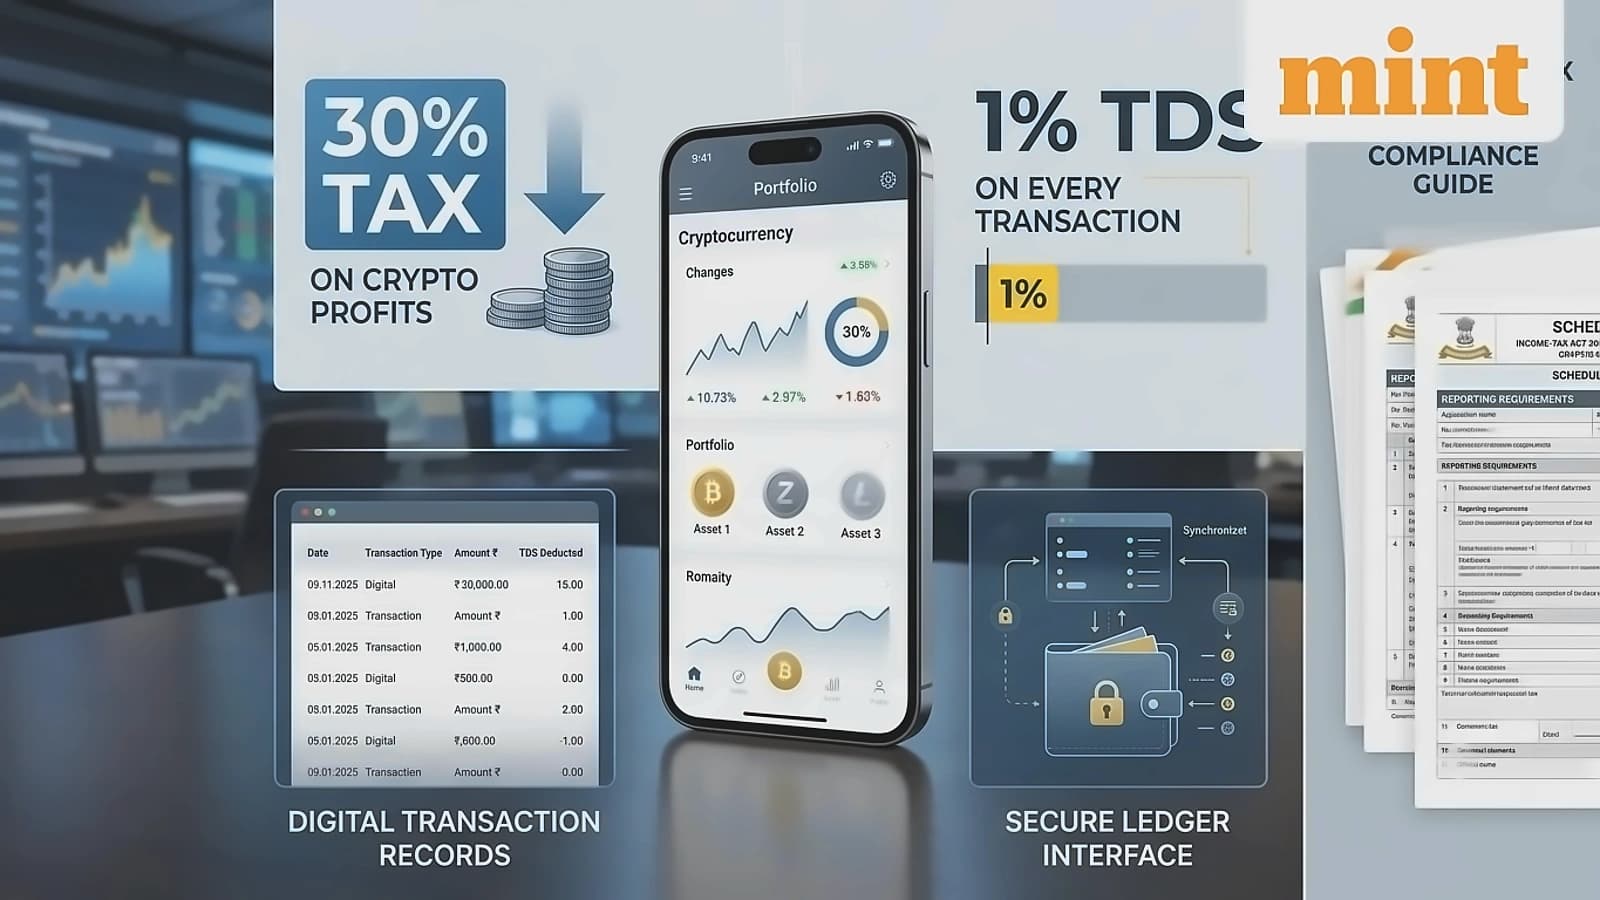
The Income-tax Act 2025 introduces significant structural changes to crypto taxation while maintaining existing tax rates. According to reports from Mint, the 30% tax on VDA transfers moves from Section 115BBH to Section 194(1), while 1% TDS shifts from Section 194S to Section 393(1). The new Act also includes Section 509, which introduces a dedicated reporting framework for crypto exchanges and service providers, requiring them to identify users, verify tax residency, and file annual transaction-level reports through Form 167. As reported by Mint, the core provisions remain familiar to investors, representing more of a structural reorganisation than fundamental changes to crypto taxation.
The new Act explicitly defines Virtual Digital Assets (VDAs) to include crypto, NFTs, and similar tokens, with the definition covering what is taxable. According to reports from Mint, investors should distinguish between virtual digital assets and virtual digital space, which covers digital environments accessed during authorised tax proceedings. Online investment accounts, trading platforms, emails and cloud records fall within virtual digital space but do not automatically become taxable VDAs. As explained by Mint, the inclusion of online investment accounts or cloud servers within virtual digital space does not make those accounts or systems taxable VDAs, but rather digital locations containing information relevant to assessments.
The 30% flat tax rate on VDA transfers remains unchanged, with no distinction between short-term and long-term holding periods. According to reports from Mint, only the cost of acquiring VDAs can be deducted, while trading fees, platform charges, and advisory expenses cannot be separately deducted under the special VDA provision. VDA losses cannot be carried forward to offset future gains or other income, and losses from one VDA cannot be set off against gains from another VDA or against salary, business income, or capital gains. The 1% TDS framework continues under the new Act, with TDS serving as advance tax credit rather than additional tax over final liability.
Section 509 creates comprehensive reporting obligations for crypto service providers, covering crypto-to-crypto trades, crypto-to-fiat conversions, and transfers rather than just buy-and-sell transactions. As reported by Mint, crypto service providers must report specified user and transaction information, with the reporting covering all crypto activities including transfers to external wallets. The new Act uses 'Tax Year' terminology instead of 'Assessment Year' and 'Previous Year', with reporting under Section 509 covering transactions from calendar year 2026, with first reports expected in 2027. Investors must maintain detailed records including transaction dates, asset types and quantities, acquisition costs, transaction values, wallet addresses, and exchange statements.
For ITR filing, investors must report all taxable VDA income including crypto-to-crypto transactions and reconcile with exchange statements, AIS, Form 26AS, and TDS records. According to reports from Mint, investors using multiple exchanges or self-custodied wallets should prepare a consolidated transaction ledger and preserve valuation records for crypto-to-crypto transactions and transfers across platforms. The terminology change to 'Tax Year' will apply to crypto-related tax filings, with investors advised to separately review airdrops, staking rewards, mining income, gifts, and transactions on foreign platforms. Investors should maintain comprehensive records including wallet addresses, transaction IDs, exchange statements, and documents supporting valuation used for tax reporting.