India's student housing sector is grappling with a severe accommodation shortage that threatens to undermine the country's educational expansion goals. According to industry estimates reported by Business Standard, only 7.5 million on-campus beds were available against over 43.3 million students enrolled in higher education during 2021-22. This significant accommodation gap has widened as demand is being met by unorganised and unregulated paying guest (PG) accommodation providers, leaving students with limited options that are often low-quality, poorly regulated and, in some cases, unsafe. The shortage comes as India seeks to bring more young people into higher education, with the National Education Policy (NEP) 2020 targeting a gross enrolment ratio (GER) of 50 per cent by 2035.
Despite the substantial market opportunity, organised private developers have largely stayed away from student housing across major education hubs including Delhi, Mumbai, Bengaluru, Kota and Sikar. As reported by Business Standard, Santhosh Kumar, vice-chairman at realty consultancy firm Anarock, attributed this to low rental yield, longer payback periods, high land costs near major education hubs, fragmented demand and limited institutionalisation. The economics of the asset class present additional challenges, with high land prices around education hubs making it difficult to offer affordable accommodation while generating attractive rental yields, as student residences are operationally intensive. However, industry players believe that student housing in India is no longer an ancillary segment but is fast maturing into a core alternative real estate asset class.
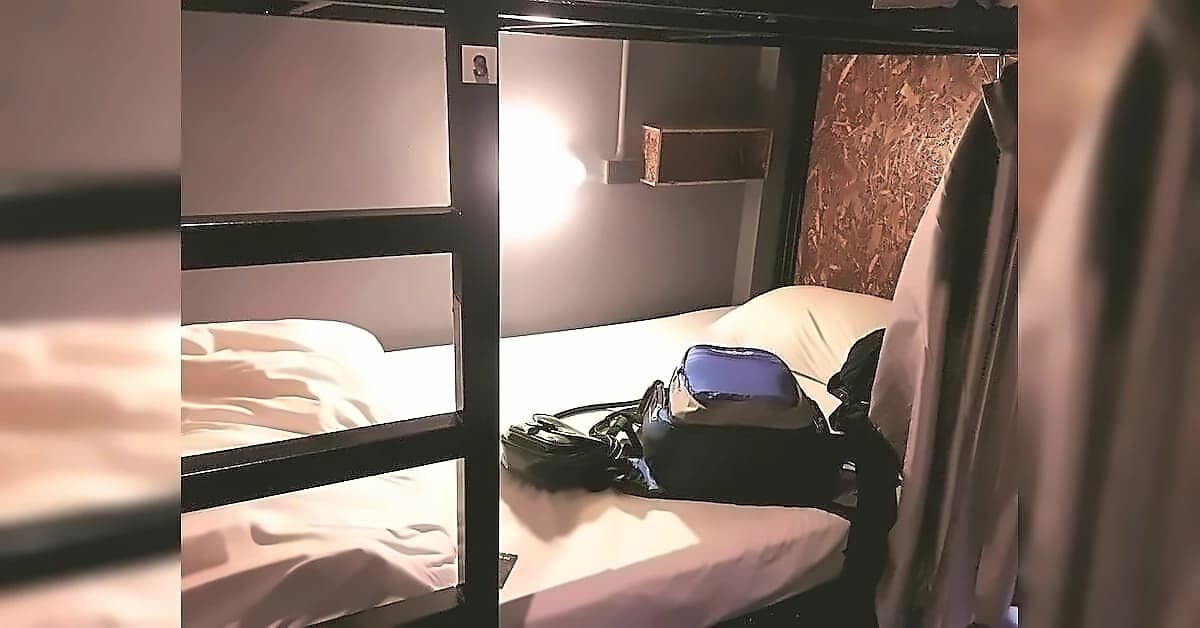
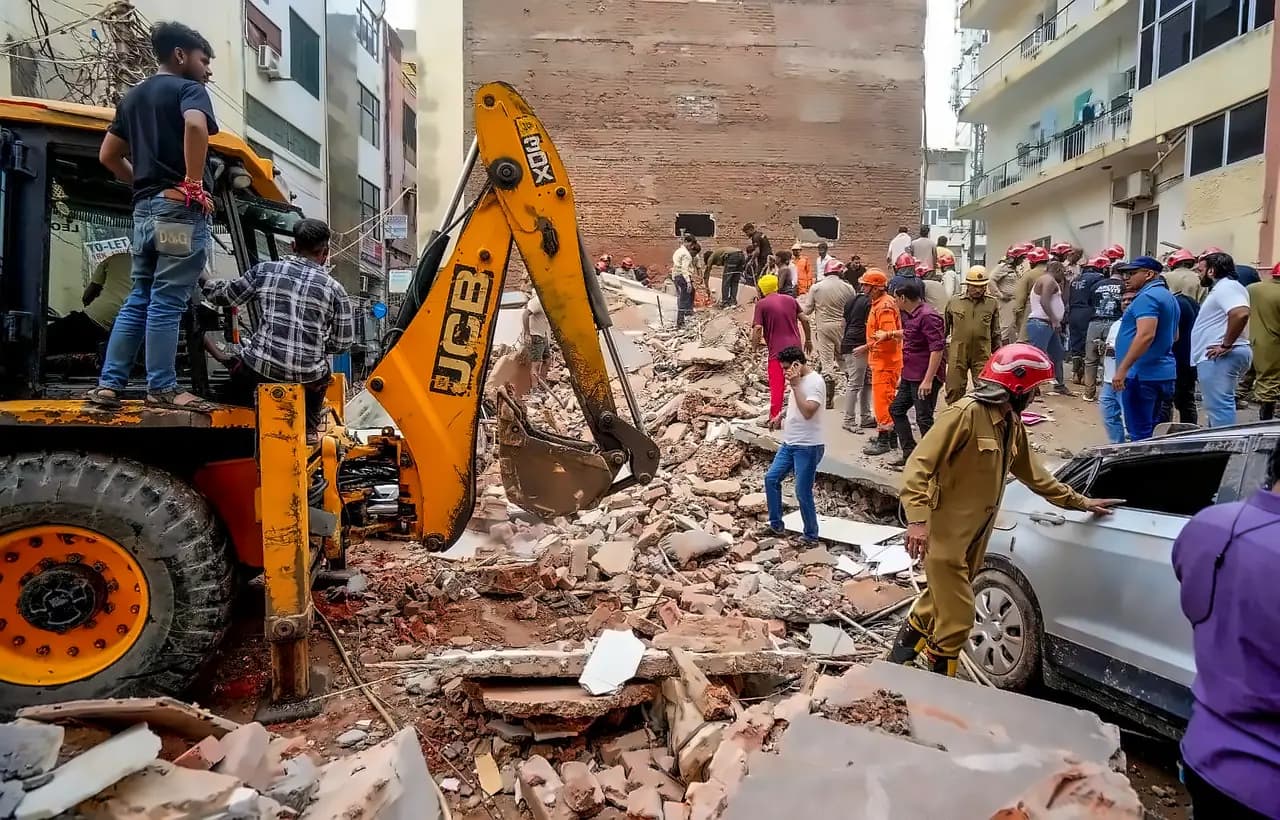
The sector faces significant regulatory ambiguity and safety challenges that have come into sharp focus recently. According to Business Standard reports, Purpose-built Student Accommodation (PBSA) often falls among residential, hostel, PG and hospitality classifications, with rules on land use, building norms, fire safety, approvals and taxation varying across states. The absence of standardised national norms and dedicated policy recognition for student housing further limits institutional investment and large-scale private participation. Recent incidents like the Satya Niketan tragedy in Delhi have highlighted the consequences of inadequate and poorly-regulated student accommodation, with security deposits sometimes paid without receipts or formal agreements. Venket Rao, founder of Intygrat Law, noted that the absence of regulations affects students, as promises on refunds, notice periods and facilities may remain verbal or on messaging platforms, making disputes harder to resolve.
Despite current challenges, industry experts see significant growth potential for organised student housing. As reported by Business Standard, Anarock expects student housing to grow at 10-12% compound annual growth rate in beds delivered over the next five years, with organised operators gaining share from the unorganised PG market. Suresh Rangarajan, founder and CEO of co-living platform Colive, noted that yields upwards of 12% are achievable with higher floor area ratio (FAR), reduced parking norms and public-private partnerships (PPPs). Under PPP models, universities and government institutions could provide land while private developers bring capital, construction expertise and professional operations. The segment could follow the broader shift towards organised rental housing, though its growth is likely to be slower than that of co-living due to fragmented demand, regulatory uncertainty and project economics.
The sector presents compelling investment opportunities as it transitions from fragmented rentals to branded, investment-grade student residences. According to Business Standard reports, key positives for investors include high occupancy resilience, operating leverage potential, and alignment with global institutional investment trends in alternative assets such as PBSA in the United Kingdom, United States, and Australia. Early movers with city-cluster strategies, efficient operating models and compliance-oriented facilities are best positioned to capture value as the market evolves towards organised, institutional-grade student accommodation. The market is expected to follow the broader shift towards organised rental housing, though its growth is likely to be slower than that of co-living due to fragmented demand, regulatory uncertainty and project economics.