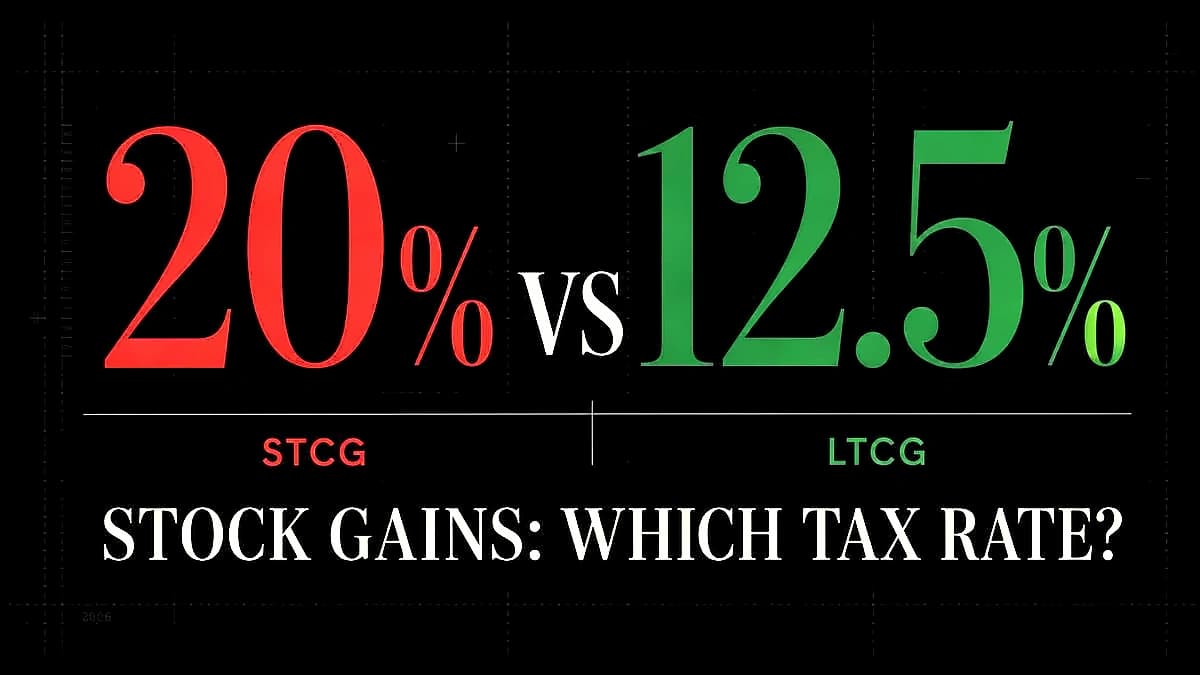
According to reports from Personal Finance News, taxpayers with Restricted Stock Units (RSUs) granted by US-based employers face specific tax implications when sold in India. The tax assessment occurs in India despite the shares being held and sold in the US. These RSUs are classified as long-term capital gains if the holding period exceeds 24 months, with taxation at flat 12.50% without indexation or 20% with indexation if acquired prior to July 23, 2024. Recent developments show that free shares granted to employees under incentives programs (including RSUs, performance shares, and employee stock purchase plans) are now taxed at 15% when linked to specific performance milestones or employment events, with no retention period required.
As reported by Personal Finance News, residential plot sales also qualify as long-term capital gains when held for more than 24 months. The taxation structure varies based on acquisition timing, with flat 12.50% without indexation or 20% with indexation for pre-July 2024 acquisitions. The taxpayer must invest the net sale consideration rather than just the capital gains realized to claim exemption under section 86. Recent changes have also introduced sales tax at 1‰ on shares listed on regulated markets in Greece under Law 4514/2018, regardless of whether transactions are executed within or outside these trading venues.
According to Personal Finance News, taxpayers can claim exemption under section 86 of the Income Tax Act 2025 by investing net sale proceeds in residential house property within prescribed timeframes. The exemption applies to both RSU gains and residential plot sales, but multiple residential house ownership disqualifies exemption eligibility. Since the taxpayer in this case does not own any residential house, they remain eligible for section 86 benefits. Recent developments show that certain capital gains are exempt from taxation, including gains from listed shares when the transferor holds less than 0.5% of share capital, as well as gains from Greek and EU/EEA UCITS mutual funds.
As reported by Personal Finance News, for self-construction projects, the construction timeline must be completed within three years from the date of RSU sale and residential plot sale. The exemption extends to plot land costs for self-construction purposes, but pure plot purchases without residential construction do not qualify for exemption. The unused amount must be deposited in a Capital Gains Account Scheme bank account for future residential house purchases. Recent changes have also suspended taxation of capital gains on immovable property until December 31, 2026 pursuant to Article 90 of Law 5162/2024.