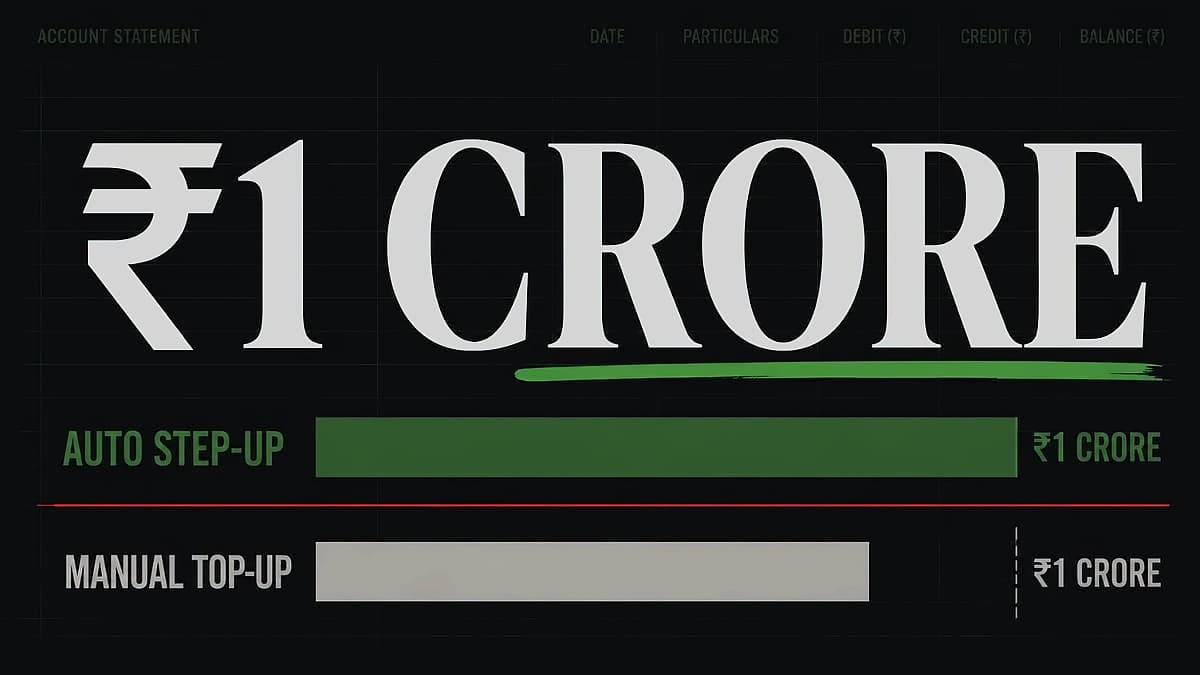
According to reports from [source], a flat ₹10,000 SIP investment can build a corpus of ₹2.1 crore over 20 years. However, a 10% step-up SIP with the same initial amount can generate significantly higher returns, reaching ₹11.71 crore over an extended 32-year period at an assumed 12% annual return. This represents a substantial ₹9.6 crore difference in final corpus value between the two investment strategies, demonstrating how step-up SIPs can supercharge wealth creation over longer investment horizons.
As reported by [source], the step-up SIP strategy involves increasing the monthly investment amount by a predetermined percentage over time. In this example, a 10% step-up means the SIP amount increases by ₹1,000 each year, starting from the initial ₹10,000 monthly investment. The systematic escalation allows contributions to grow alongside rising income and changing financial needs. Recent calculations show this progression: ₹10,000 (year 1) to ₹23,579 (year 10) to ₹61,159 (year 20) to ₹1.61 crore (year 32), with total investments of ₹24 lakh versus ₹68.73 lakh for the step-up strategy.
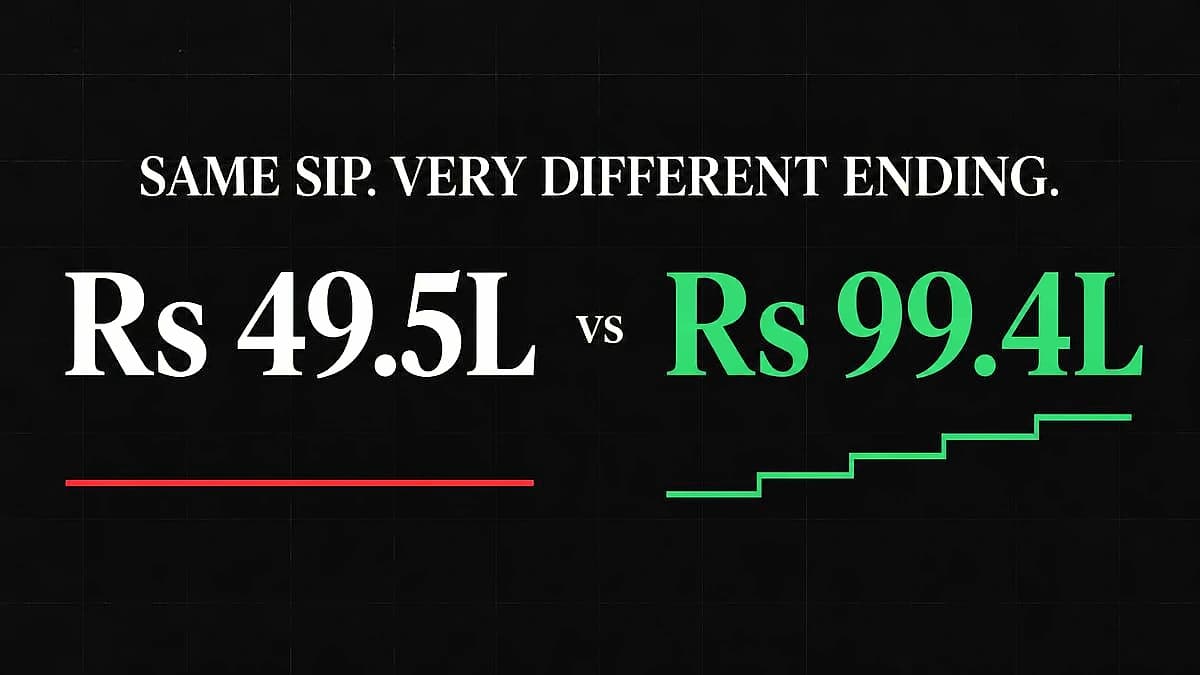
According to 1 Finance research, step-up SIPs provide crucial protection against inflation by automatically increasing contributions over time. The analysis considers a scenario where current 4.82% retail inflation could reach double digits by the investment's maturity. A ₹50 lakh goal today would require a much larger corpus 32 years later due to inflation-driven cost increases. The step-up SIP's ability to raise monthly contributions from ₹10,000 to ₹61,159 ensures larger amounts are invested during later years when they can compound more effectively. This strategy helps investors stay invested through market downturns, as larger contributions during recovery periods maximize compounding benefits.
The choice between direct and regular mutual fund plans significantly impacts final corpus growth. Recent calculations show that ₹1.61 crore can grow to approximately ₹1.46 crore under a regular plan with 1% commission deduction. This represents a substantial ₹15.29 lakh difference in final corpus, highlighting how ongoing commissions can reduce long-term returns. The compounding effect demonstrates how growth options and direct plans contribute meaningfully to building wealth over extended investment periods, making the step-up SIP strategy even more valuable for long-term financial goals.