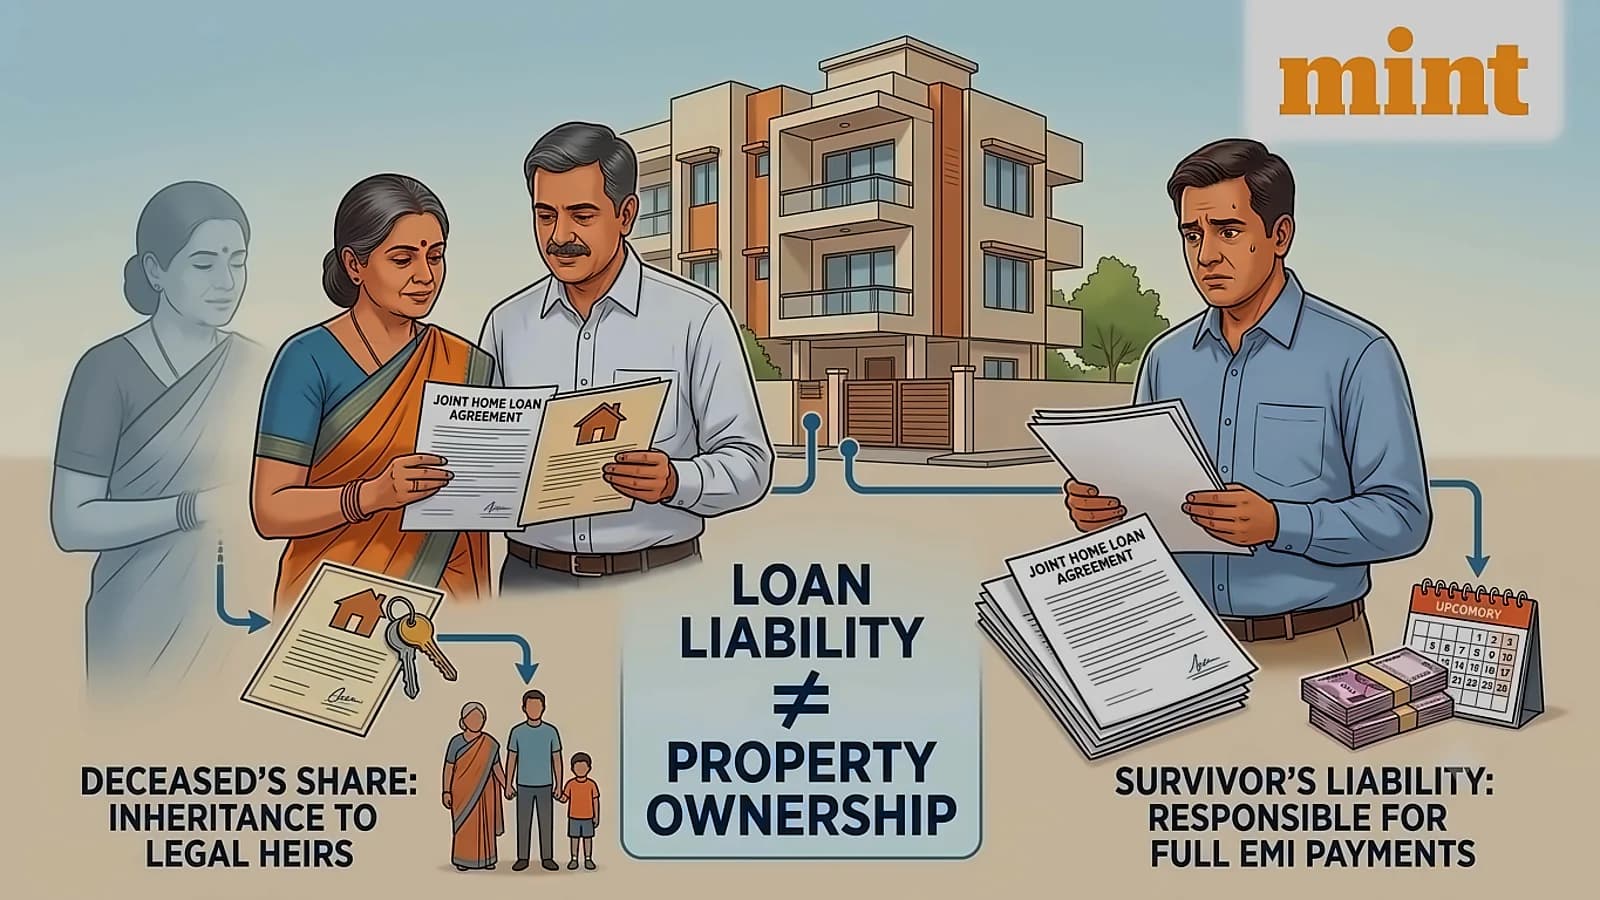
Under Indian law, marriage alone does not make a spouse liable for a deceased borrower's debt. According to Amit Kumar Nag, partner at AQUILAW, recovery depends on whether the spouse was a co-borrower or guarantor, or inherited assets from the deceased. The Securitisation and Reconstruction of Financial Assets and Enforcement of Security Interest (SARFAESI) Act does not specifically define 'co-borrower', with loan agreements determining the capacity in which the spouse signed. As reported by Business Standard, co-borrowers are generally jointly and severally liable for outstanding debt, with the death of the other borrower not extinguishing or reducing that liability.
A guarantor's liability is generally co-extensive with that of the principal borrower, unless the guarantee deed limits it. As explained by Nag, this obligation arises from the guarantee contract and generally survives the borrower's death. The lender need not first exhaust remedies against the borrower, the deceased's estate or the collateral and can proceed directly against the guarantor, subject to guarantee terms. According to King Stubb and Kasiva partner Nivedita Bhardwaj, recovery from inherited assets must follow due legal process under applicable laws including the SARFAESI Act, Recovery of Debts Act or through civil suit.
A spouse who is neither co-borrower nor guarantor has no personal liability for the loan. As reported by Business Standard, the debt survives against the deceased's estate, with recovery limited to the value of assets or estate inherited from the deceased. Bhardwaj explains that banks cannot recover dues from the spouse's separate property or savings, with the spouse's salary, savings and FDs generally not attachable unless the spouse guaranteed the loan. In jointly owned property, only the deceased borrower's share can be pursued, while in joint bank accounts, recovery is generally limited to the deceased's interest.
Family pension, provident fund and gratuity have statutory protection from recovery of deceased borrower's debts under various laws. According to BMR Legal partner Shankey Agrawal, life insurance policies taken out under the Married Women's Property Act for wife or children benefit are protected from husband's creditors. Proceeds from loan-linked insurance, such as credit-life cover, must go towards paying off the debt. As reported by Business Standard, if the estate cannot repay the loan, the bank can proceed against security, deceased's estate, co-borrower or guarantor, but recovery from spouse's independent assets is generally prohibited.
Before recovery, banks must establish their legal basis by examining loan documents, security, guarantees, insurance cover and assets forming part of the deceased's estate. According to Agrawal, the Allahabad High Court emphasized that recovery must follow due legal process, with banks not having the right to simply debit protected funds. Couples should understand each person's liability when taking loans, with co-borrowers having direct financial liability and merely being co-owners not necessarily creating the same obligation. As reported by Business Standard, spouses should carefully review loan terms including mortgaged assets, lien, set-off and cross-default clauses covering borrower's death.