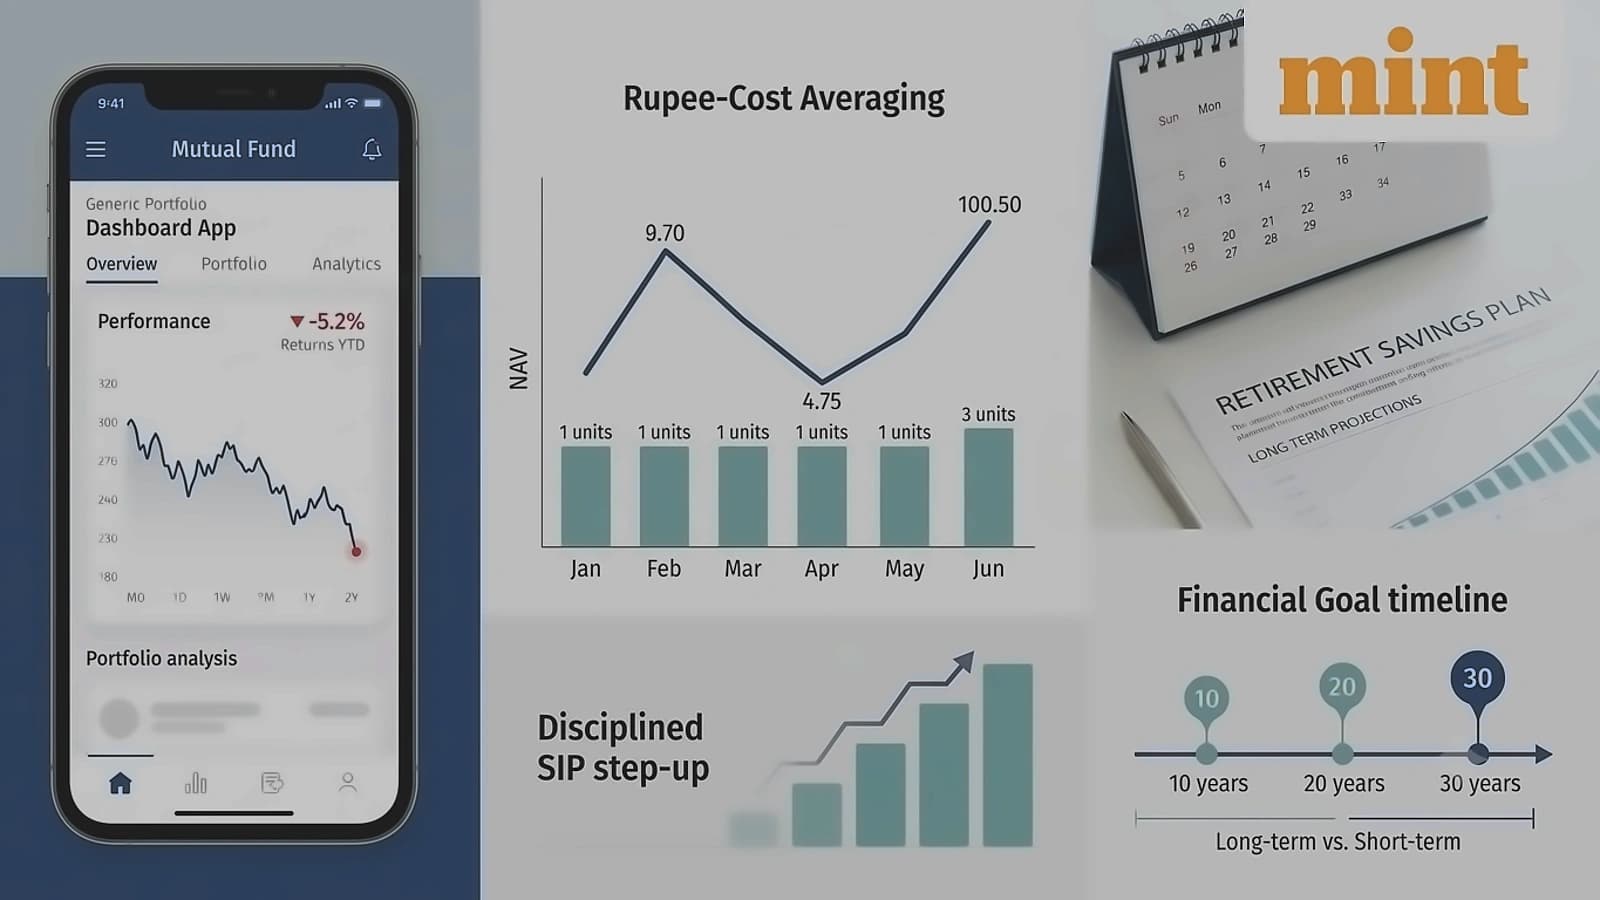
A Systematic Investment Plan (SIP) in mutual funds can help parents build an education fund over time by investing a fixed amount regularly. According to financial planning guidance, parents should consider whether to continue investing in equity mutual funds until the month college fees are due, with the answer depending on investment timeline, risk tolerance, and accumulated funds. While equity investments may help generate long-term growth, market returns are not guaranteed, making protection of college money increasingly important as the deadline approaches.
For a ₹30 lakh college fund target over 12 years, financial experts suggest starting early provides more time for investments to grow through compounding. As reported by financial planning sources, assuming an annual return of 12%, a monthly SIP of around ₹10,000 for 12 years could grow to approximately ₹32 lakh. The total investment would be ₹14.40 lakh, with expected returns of ₹17.82 lakh and a maturity corpus of ₹32.22 lakh. These figures are approximate estimates based on monthly investments and a 12% annualised return, with actual returns varying and not guaranteed.
Recent market data reveals significant shifts in mutual fund investor preferences, with small-cap funds attracting over 10 times more net inflows than large-cap schemes. According to AMFI data, monthly SIP contributions reached ₹32,490 crore in September 2026, compared with ₹32,297 crore in August. However, these inflows are gross investments rather than net inflows into specific categories, as investors continue to redeem investments and adjust portfolios. The small-cap and mid-cap categories together received approximately 44% of total net inflows into equity-oriented mutual fund schemes, reflecting investor preference for growth potential despite higher volatility.
Rather than keeping the entire college fund exposed to equity-market fluctuations until fees are due, parents can implement a staged investment strategy. According to financial planning recommendations, Years 1-7 should focus on long-term growth through suitable equity-oriented mutual funds, while Years 8-10 should gradually reduce risk by moving portions from equity investments into relatively lower-volatility options such as high-quality debt investments or bank deposits. Years 11-12 should focus on keeping college expense money in stable and accessible investments, with withdrawals planned according to payment schedules.
Despite the growth in SIP investments, market performance shows that equity mutual fund assets under management declined from ₹39.21 lakh crore in August to ₹37.54 lakh crore in September 2026, even with net inflows of ₹38,306.55 crore. This demonstrates that SIP contributions alone cannot prevent market losses, as the decline in existing investment values outweighed positive effects of fresh inflows. For college fund planning, investors should maintain appropriate allocation across market capitalisations based on risk appetite, with cautious investors allocating 80% to large-cap, 15% to mid-cap, and 5% to small-cap funds, while moderate investors may consider 65% large-cap, 25% mid-cap, and 10% small-cap. The key is to maintain allocations that can be sustained during substantial corrections rather than assuming regular inflows will prevent market volatility.