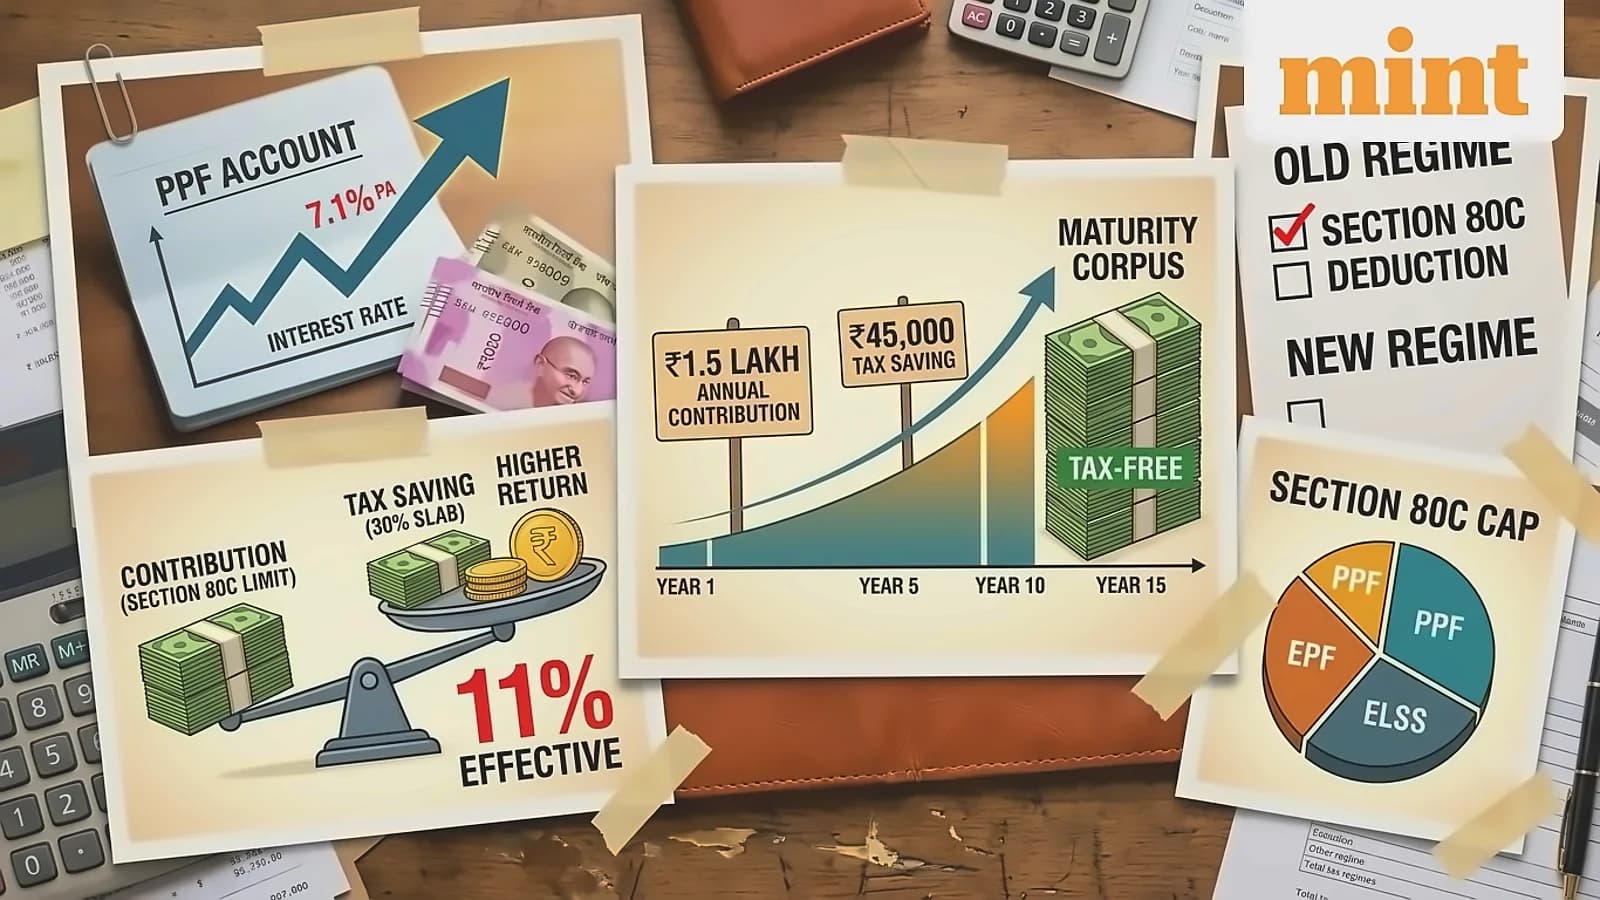
The Public Provident Fund (PPF) continues to be a cornerstone of prudent financial planning, offering a guaranteed 7.1% annual return under the Exempt-Exempt-Exempt (EEE) tax regime. According to recent reports, an annual investment of ₹1.5 lakh can grow to an estimated ₹40.68 lakh over 15 years, with ₹18.18 lakh in interest earned over the investment period. For investors in the 30% tax bracket, PPF's 7.1% tax-free return is equivalent to a pre-tax return of 10.1%, outperforming many debt instruments. The rate, fixed by the government quarterly, has remained stable since April 2020, providing a predictable growth path different from volatile market-linked investments.
Section 80C of the Income-Tax Act provides taxpayers with deductions of up to ₹1.5 lakh in a financial year to reduce their tax liability. According to reports from Mint, this provision is outlined under Section 123 in the new ITA 2025 implemented from April 2025, though it is only available under the old tax regime. The key advantage of Section 80C investments is that they offer dual benefits - tax savings while providing interest income simultaneously. Additionally, taxpayers can claim an additional ₹50,000 deduction under Section 80CCD(1B) on contributions to specified pension funds and Section 80TTB for tax-saver fixed deposits.
Several financial instruments qualify for Section 80C deductions, as reported by Mint. These include unit-linked insurance plan investments, tuition fees for up to two children, Sukanya Samriddhi Yojana (SSY), Senior Citizens Savings Scheme (SCSS), registration and stamp duty payments, Public Provident Fund (PPF), National Savings Certificate (NSC), National Pension Scheme (NPS), loan principal repayments, Life Insurance Corporation of India (LIC) premiums, Equity Linked Saving Scheme (ELSS), Employees Provident Fund (EPF), and five-year tax-saving fixed deposits.
According to Mint's analysis, taxpayers should invest early in the financial year to maximize compounding benefits and avoid last-minute tax filing complications. For PPF specifically, experts recommend investing before the 5th of each month to maximize interest earnings. However, missing key deadlines like the April 5 PPF deposit deadline results in money earning from May onwards, losing one full month of interest. The report recommends using the full ₹1.5 lakh limit strategically, such as investing ₹50,000 each in PPF, ELSS, and life insurance premiums while diversifying across schemes with varying interest rates, features, and risk levels. PPF accounts require a minimum yearly contribution of ₹500 to remain active, with deposits allowed monthly or yearly without fixed due dates.
As reported by Mint, taxpayers can extend their total deductions to ₹2 lakh by utilizing the additional ₹50,000 claim under Section 80CCD(1B) through NPS investments. The report emphasizes that all investments must be made under the taxpayer's name with relevant documents available during ITR filing. Different categories of taxpayers can allocate investments based on their specific needs - singles can focus on retirement, insurance, and equity investments, while parents can include school fees and child-focused schemes, and senior citizens can utilize tailored options like SCSS to maximize benefits. Recent analysis shows that maximizing Section 80C investments alone can result in total deductions exceeding ₹2.25 lakh, often crossing ₹4-5 lakh when combined with home loan interest and HRA exemptions.