The Pension Fund Regulatory and Development Authority (PFRDA) announced on Friday the launch of Retirement Income Schemes (RIS) and drawdown options under the National Pension System (NPS), aimed at giving subscribers greater flexibility in managing their pension savings after retirement. In a circular dated May 15, 2026, the pension regulator introduced these new retirement income options that build on earlier circulars and follow amendments to the PFRDA (Exits and Withdrawals under the NPS) Regulations, 2025. The initiative allows subscribers to withdraw a designated portion of their pension corpus in phases through different drawdown options during the decumulation phase, with the authority clarifying that withdrawals made under the RIS framework will not affect the mandatory annuitisation requirement under NPS.
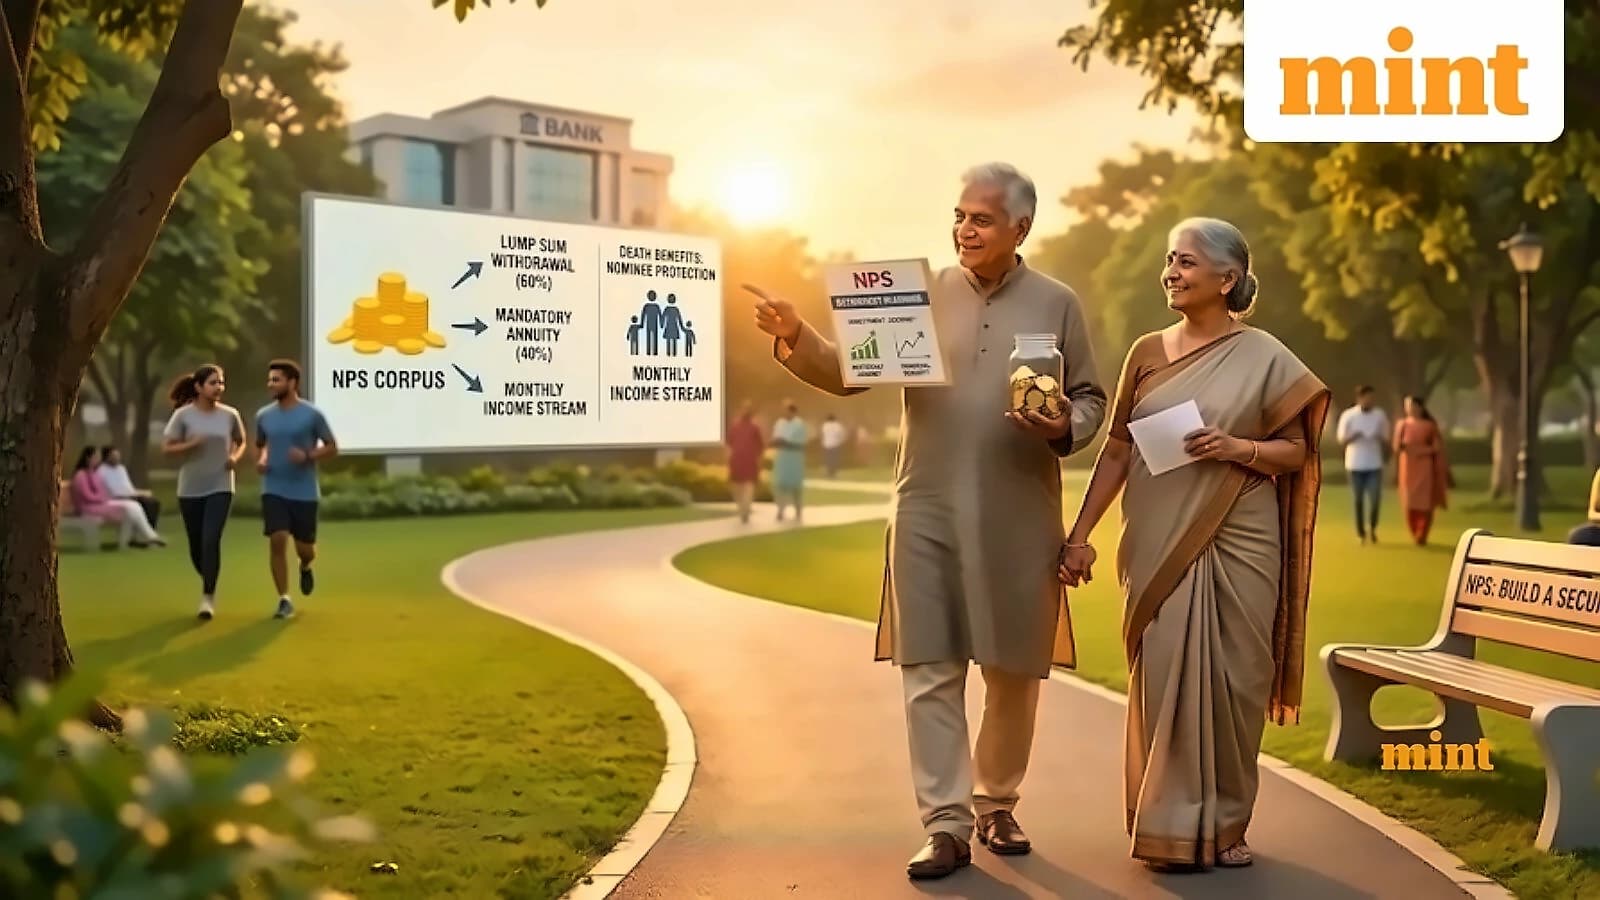
Under the new framework, subscribers will have significantly more withdrawal options than previously available. The drawdown facility will be available to both government and non-government subscribers under NPS, with subscribers having the option to receive payouts on a monthly, quarterly or annual basis. The payout period can continue up to the age of 85 years or according to the choice exercised by the subscriber at the time of exit from the pension system. This represents a major shift from the previous restrictions, where subscribers were required to use at least 40 per cent of their retirement corpus to buy an annuity, which then provided regular pension income after retirement. Recent guidance clarifies that for subscribers exiting before age 60, they can only withdraw 20% as a lumpsum, with 80% required for annuity purchase, though partial withdrawals are permitted for specific purposes like children's education, marriage, or first house purchase after 3 years of joining.
Despite the new drawdown options, subscribers are still required to meet mandatory annuitisation requirements under NPS. Subscribers are required to use the minimum prescribed portion of their corpus - 20 per cent or 40 per cent, depending on the category - for purchasing an annuity to ensure a lifelong pension. The regulator has clarified that these mandatory requirements remain in full force and effect, ensuring that retirees maintain long-term financial security through guaranteed income streams. The new drawdown options are designed to complement rather than replace the existing annuity framework, providing subscribers with multiple pathways to access their retirement savings while maintaining long-term financial stability. Recent developments also allow partial withdrawals for specific critical illnesses, including cancer, kidney failure, and heart surgery, with subscribers able to withdraw up to 25% of their own contributions for treating these conditions, subject to a 3-year initial wait period.
The new guidelines will come into effect from a date to be notified later, after the necessary system capabilities and operational framework are put in place. The circular was issued under the powers conferred by Section 14 of the PFRDA Act, 2013. This phased implementation approach allows PFRDA to ensure proper infrastructure and regulatory frameworks are established before the new options become available to subscribers, ensuring smooth transition and effective operation of the enhanced retirement income system.
This latest development builds on PFRDA's earlier regulatory relaxations, including the annuity surrender provisions announced in October 2024 that now allow surrender of annuity policies in select cases where the annuitant or family member is suffering from critical illness, or where the annuity policy was issued before October 24, 2024 and already carried an explicit surrender clause. The new drawdown scheme represents a comprehensive approach to retirement income management, combining the flexibility of drawdown options with the security of mandatory annuitisation requirements, providing subscribers with multiple pathways to access their retirement savings while maintaining long-term financial stability. Under the NPS structure, Tier 1 serves as the mandatory retirement account with strict withdrawal rules but high tax benefits, while Tier 2 acts as a voluntary savings account that allows anytime withdrawal with nil entry and exit loads, making it particularly attractive for liquidity needs and emergency situations.