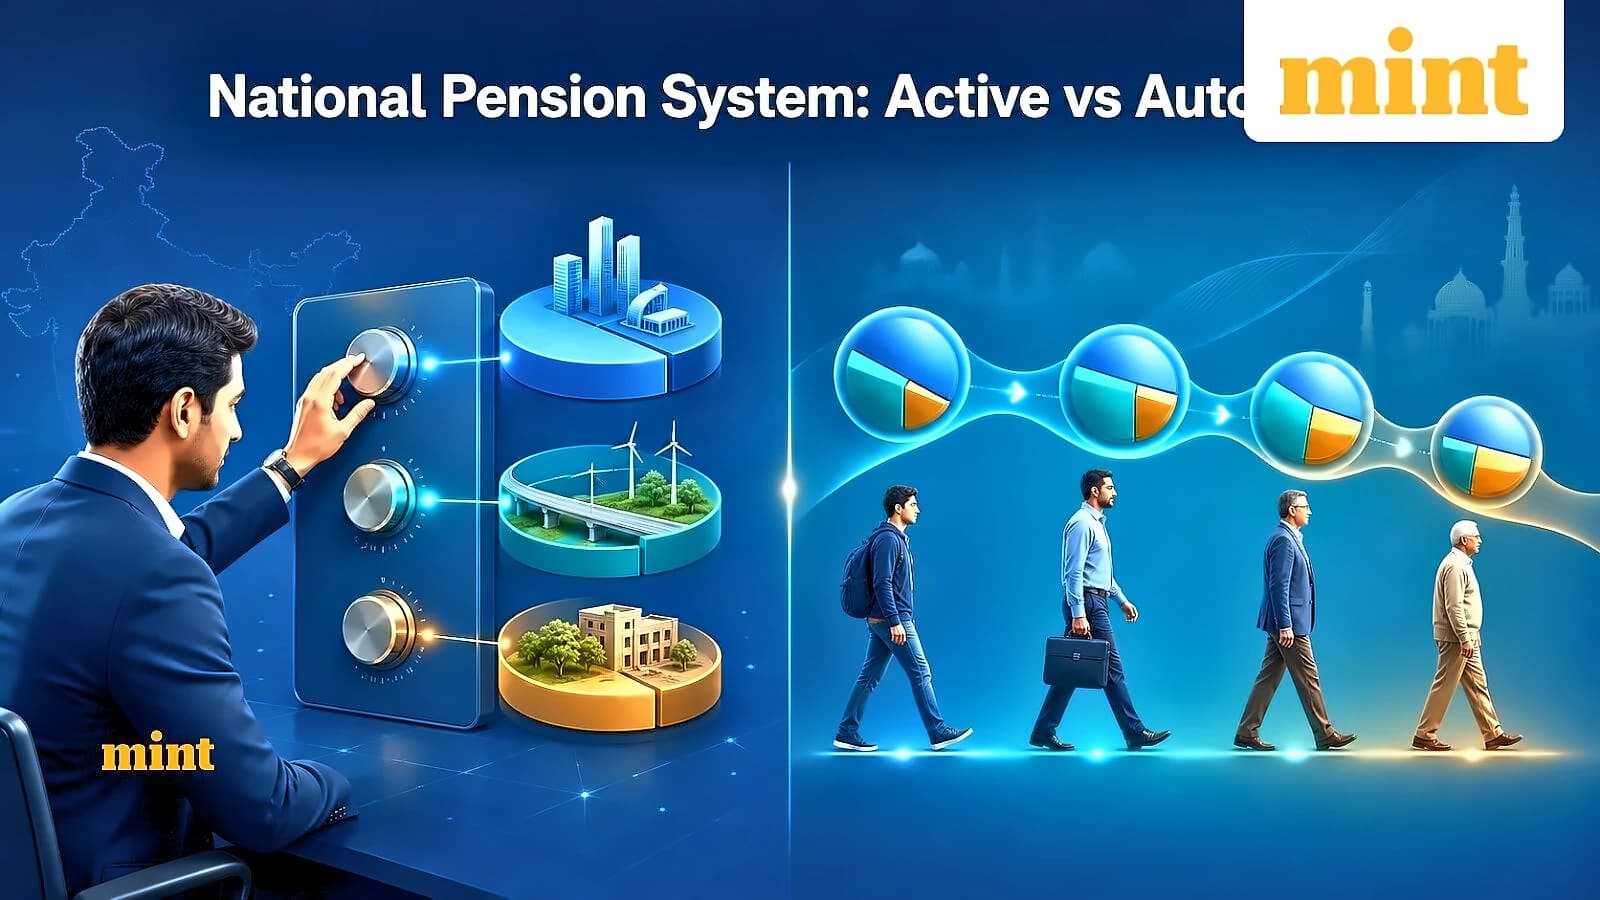
The National Pension System (NPS) offers two primary investment strategies that significantly impact portfolio allocation and risk management. According to reports from Mint, Active Choice allows subscribers to assign up to 75% of their portfolio to equities, while Auto Choice relies entirely on age-based formulas through life-cycle funds. As of August 2026, guidelines from the Pension Fund Regulatory and Development Authority (PFRDA) permit subscribers in Common Schemes to choose either strategy, with PFRDA offering Life Cycle 25, Life Cycle 50, Life Cycle 75 and Life Cycle Aggressive options under the Auto Choice framework. The choice determines how contributions are divided between equity, corporate bonds and government securities, with younger investors typically choosing higher equity allocations due to longer investment horizons, while those approaching retirement may prefer more debt and government securities. Zee News reports that Active Choice facilitates the choice of asset mix, with an equity limit of up to 75 percent, while corporate debt and government securities can have a limit of up to 100 percent.
Both retirement schemes offer different tax advantages and withdrawal options that impact overall financial planning. According to Zee News, EPF contributions are eligible for tax deduction under Section 80C up to ₹1.5 lakh annually under the old tax regime, while no such deduction is offered under the new tax regime. For PF contributions exceeding ₹2.5 lakh annually, the accrued interest becomes taxable. In contrast, NPS contributions are eligible for tax deduction under Section 80CCD(1) and Section 80CCD(1B), with 60 percent of the accumulated corpus being tax-free at the time of withdrawal. Under EPF, a part of EPF can be withdrawn using Form 31 for medical emergencies, marriage, home loans, and education, with the withdrawal amount and frequency subject to limits associated with the reason. Under NPS, after completing three full years of contribution, 25 percent of employee's contribution can be withdrawn for specific purposes including education, marriage, medical needs, or housing.
Recent analysis comparing both retirement schemes reveals significant differences in potential returns based on investment strategy. According to ETWealth calculations, an EPF subscriber with ₹10,000 monthly contribution (12% of basic salary) and 5% annual increases could generate an estimated retirement corpus of ₹4.43 crore over 30 years. However, NPS with Active Choice (75% equity + 25% bonds) and 12.7% returns could potentially yield a higher corpus of ₹5.30 crore. The NPS strategy offers more flexibility through its diversified equity and bond allocation, while EPF provides stability through government-reviewed interest rates. ETWealth notes that both calculations are assumption-based and actual returns may vary significantly based on future market performance and policy changes.
Investment professionals emphasize that higher equity exposure does not automatically guarantee better returns, particularly for younger investors. As reported by Mint, equities provide higher long-term growth potential but also experience greater short-term volatility. The appropriate allocation should reflect both investment horizon and individual ability to tolerate market fluctuations, with young investors who are uncomfortable with sharp market declines potentially better served by more balanced allocations than those who understand and accept higher volatility. A common mistake is to assume that the option with more equity is automatically better for a young investor, but the right allocation depends on how much fluctuation you can tolerate and how long the money will remain invested. Zee News notes that EPF follows a fixed framework that restricts the employee's choices in terms of asset distribution, while NPS provides flexibility in terms of asset allocation.
The optimal retirement strategy depends on individual risk tolerance, financial goals, and retirement timeline rather than age alone. As reported by Mint, Active Choice may be appropriate for investors who understand asset allocation, are comfortable reviewing their investments, and want greater control over equity and debt exposure. Conversely, Auto Choice could appeal to subscribers who prefer simplicity and want their asset allocation to adjust automatically as they approach retirement. The best strategy is not the one with the highest equity allocation, but the one you can stay with through both strong and difficult markets. Zee News suggests that the choice of one should not be made at the expense of the other; instead, one may choose to use a mix of the two instruments: EPF for stability and NPS for wealth growth through market exposure. This diversified approach allows investors to benefit from both schemes' strengths while managing their respective risks effectively.