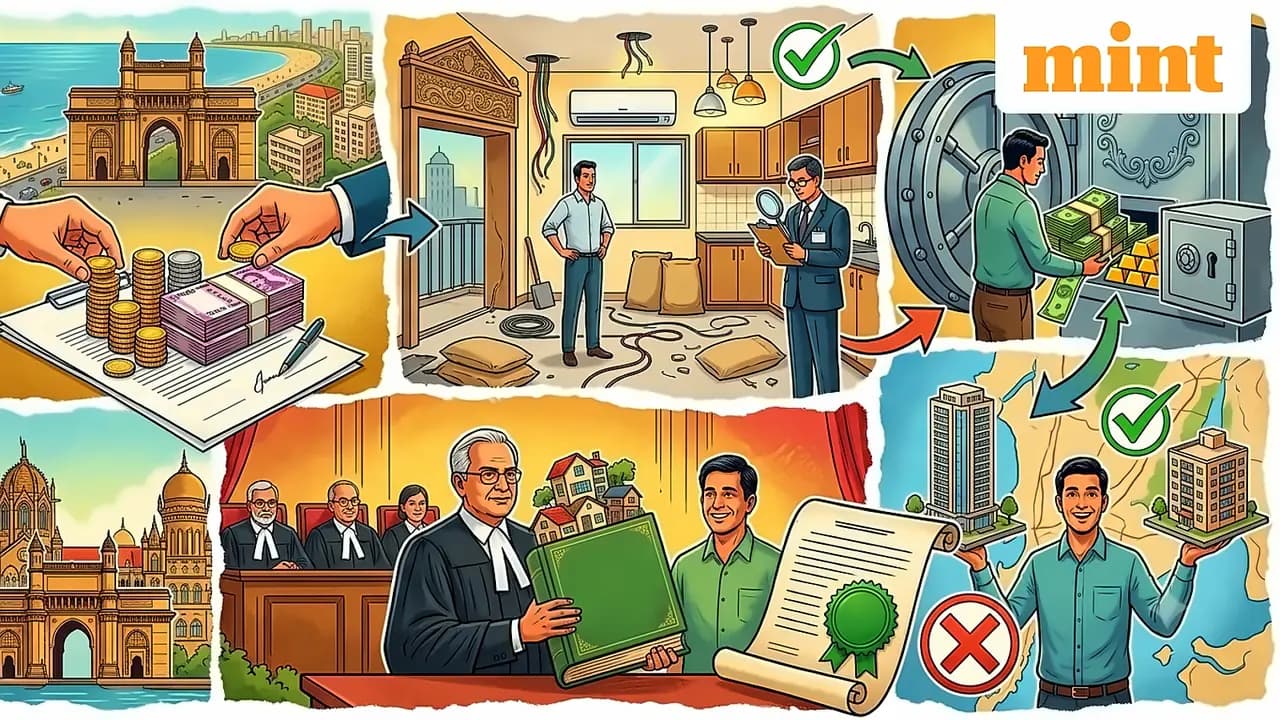
Manoj Devshi Chhadva, a tenant in a Mumbai housing society, received two flats valued at ₹1.38 crore for surrendering his tenancy rights in a redevelopment agreement. According to reports from Mint, the case began when Chhadva was renting four shops in a Mumbai housing society and the builder entered into a permanent alternate accommodation agreement with him. Under this arrangement, he received the two flats in the redeveloped building in exchange for surrendering his tenancy rights.
The income tax assessing officer from Parel invoked Section 56(2)(x) of the Income-tax Act, 1961, treating the entire stamp duty value of ₹1.38 crore as "income from other sources" in Chhadva's hands. As reported by Mint, this provision applies to receipt of money or property without consideration or for inadequate consideration if the value exceeds ₹50,000. The Commissioner of Income Tax (Appeals) upheld the tax addition, stating that Chhadva had effectively received valuable immovable property in return for giving up his tenancy rights.
After a long legal battle, the Income Tax Appellate Tribunal (ITAT) Mumbai ruled in Chhadva's favour on July 16, 2026. According to Mint, the tribunal stated that a Section 56(2)(x) tax notice cannot be sent to a tenant since he received the flats in exchange for surrendering his tenancy rights in a redevelopment building. The tribunal cited previous judgements about similar cases, holding that the Assessing Officer was not justified in invoking the provisions of Section 56(2)(x) of the Act. As reported by Economic Times, the Mumbai ITAT allowed Chhadva's appeal on 16 July 2026 for two key reasons: the redevelopment project remained incomplete with no occupation certificate and possession not yet handed over, and the allotment was consideration for valuable tenancy rights rather than a gift.
The ITAT Mumbai ruling establishes important precedent for similar cases involving housing society redevelopment agreements. As reported by Economic Times, the tribunal's decision clarifies that tenants who receive alternate accommodation in redevelopment projects should not be subject to taxation under Section 56(2)(x) provisions. The case highlights the complex tax implications of housing society redevelopment agreements and the importance of proper legal framework for such transactions. The ruling specifically addresses situations where redevelopment projects remain incomplete and possession has not been transferred, providing crucial guidance for similar cases involving tenancy right surrenders.