According to reports from The Economic Times, moneymaxxing is a modern internet term for the deliberate pursuit of better financial outcomes. As explained by Anuj Gupta, a SEBI-registered Research Analyst, it goes beyond investing to encompass what you earn, spend, save and invest, along with debt, taxes and the skills that can help you earn more. The social-media buzzword represents a comprehensive approach to financial optimization, combining traditional concepts like budgeting, investing and saving under one unified strategy.
As reported by The Economic Times, Shweta Shastri, CFP and founder at Finnora Wealth Studio, emphasizes that the first step is knowing where your salary goes. The strategy involves tracking income, expenses, EMIs and savings before deciding how much you can invest. However, she cautions against focusing only on cutting costs, stating that your salary is your biggest asset. According to the report, before investing a salary hike or bonus, individuals should prioritize building their emergency fund if they don't have at least three months of essential expenses set aside.
According to Abhishek Soni, CEO & Co-founder of Tax2win, salaried taxpayers should first compare the old and new tax regimes instead of immediately looking for tax-saving investments. As reported by The Economic Times, under the current new regime, salaried individuals receive a ₹75,000 standard deduction and eligible residents with taxable income up to ₹12 lakh can claim a rebate of up to ₹60,000. For those benefiting from the old regime, options include eligible 80C investments, HRA, home-loan interest, health-insurance deductions and NPS contributions. However, Soni warns against buying products solely for tax benefits, advising investors to consider returns, risk, lock-in, liquidity and charges before investing.
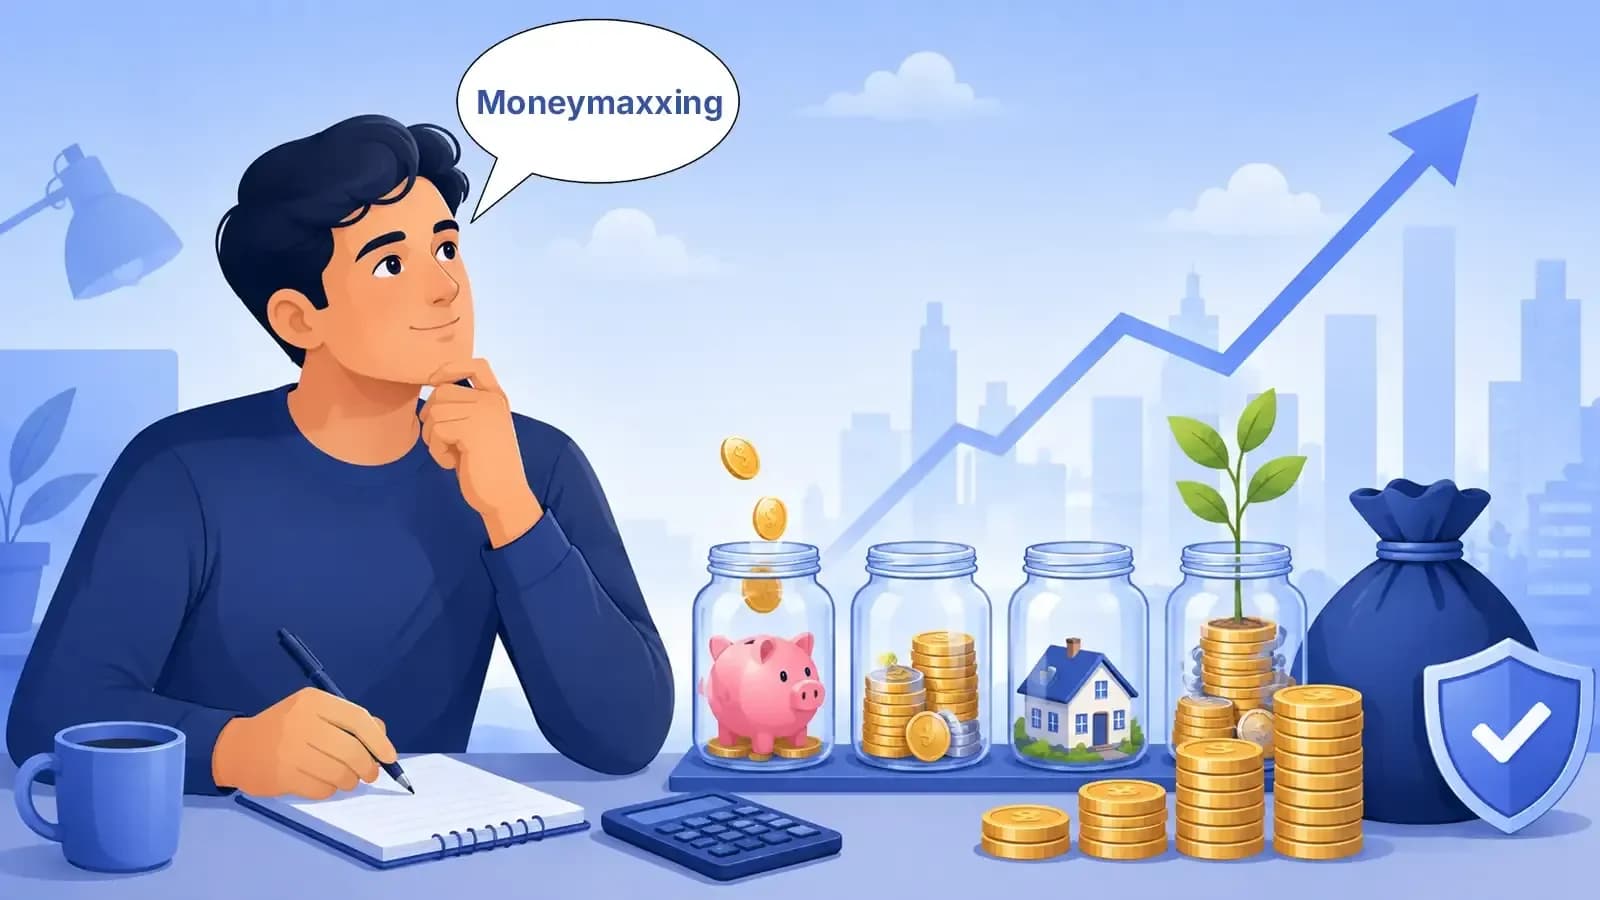
Ronak Morjaria, Partner at ValueCurve Financial Services, advocates for a goal-based investment strategy rather than product-focused approaches. According to The Economic Times, for goals six to seven years away, a larger share should go into equities through mutual funds depending on the investor's risk tolerance. For three to four-year goals, he prefers more debt through fixed deposits or short-term debt funds, with investors comfortable with additional risk considering equity savings funds. The report emphasizes matching investments to specific goals, noting that money needed in three years shouldn't be invested the same way as retirement money.
As reported by The Economic Times, employees often focus on CTC and take-home pay while overlooking employer benefits. Abhishek Soni suggests checking employer NPS, HRA, LTA/LTC, health insurance, company car arrangements and other benefits depending on the employer and applicable tax rules. He emphasizes that don't just negotiate your salary, optimize your salary structure. The report notes that while EPF and NPS can form important parts of retirement planning, they are less flexible than easily accessible investments, requiring investors to consider overall asset allocation instead of competing for the 'best' product.