When investing in mutual funds or purchasing insurance policies, investors are required to nominate a person to receive proceeds upon death. According to reports from Mint, there is no minimum age restriction for naming a nominee for insurance policies, mutual funds, fixed deposits, or the Employees Provident Fund (EPF). However, being named as a nominee does not necessarily determine who ultimately inherits the assets, as the nominee only acts as a custodian while the ultimate distribution is governed by the deceased's will or applicable succession laws. Nomination is primarily a mechanism for receiving or transferring assets after the account holder's death, but it does not automatically mean that the nominee is the ultimate owner of every asset. As reported by Moneycontrol, RBI's guidance makes clear that payment to a bank nominee is a valid discharge of the bank's liability, while the nominee receives the money as a trustee for the legal heirs.
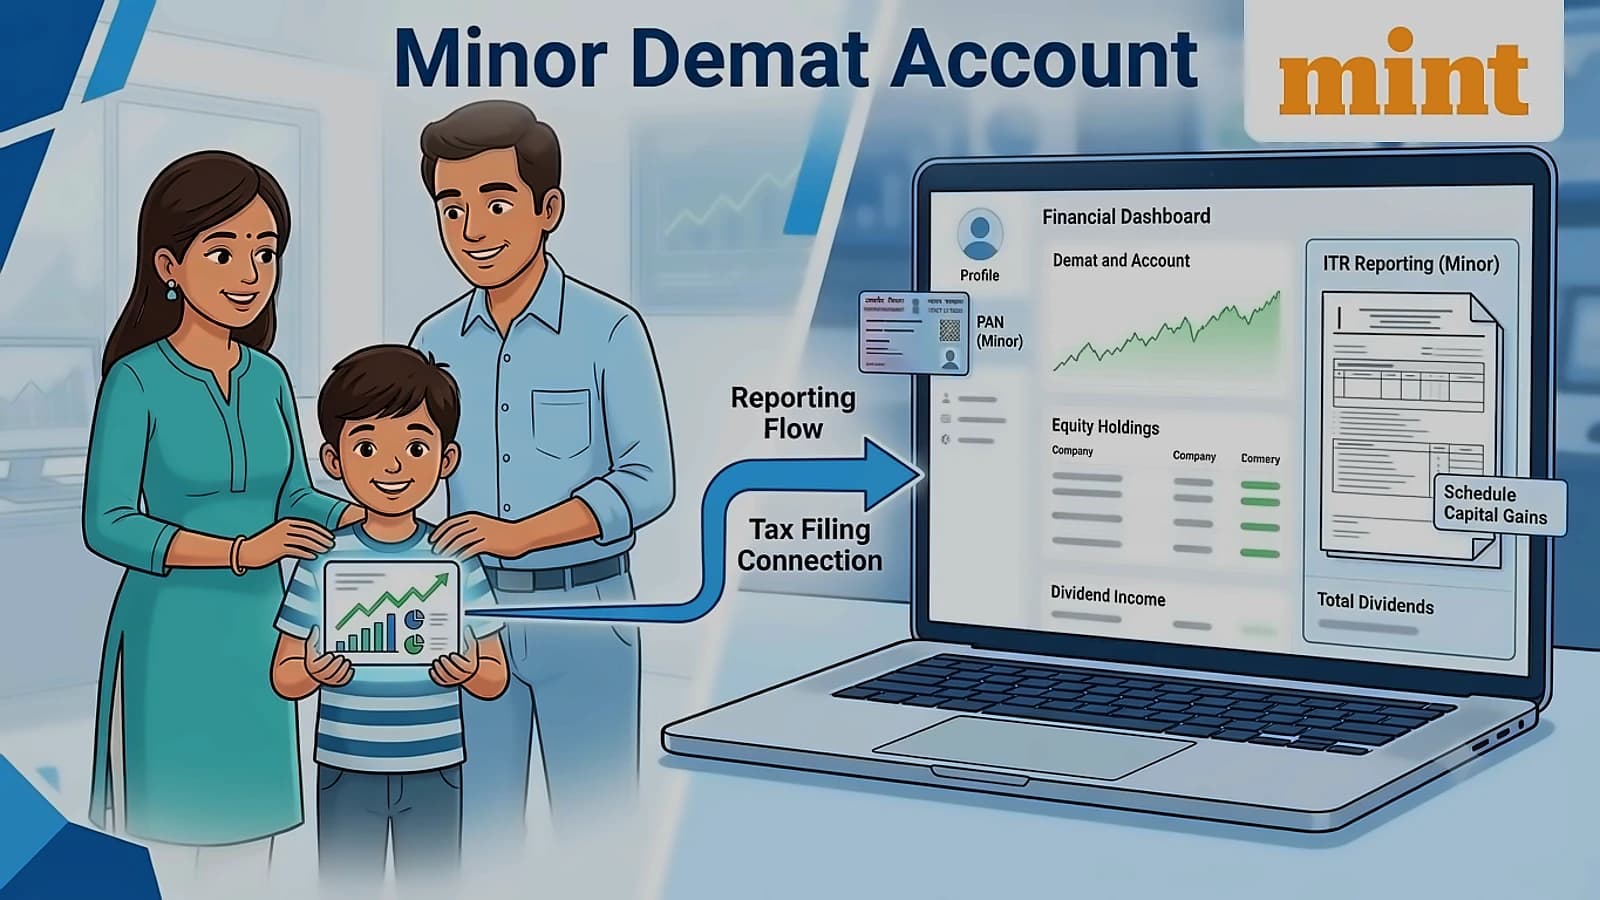
When a minor is nominated, applicable rules require a guardian or designated person to receive the proceeds on behalf of the minor. As reported by Mint, the guardian will receive and safeguard the payout until the minor turns 18 years old, at which point the funds must be transferred to the minor. This is particularly relevant for life insurance policies, where under the Insurance Act, a policyholder can nominate a minor and appoint a person to receive policy money on the minor's behalf while the nominee remains a minor. Parents sometimes name a young child as nominee without considering who will handle the money until the child becomes an adult, making guardian arrangements crucial for proper asset management during the minor's minority period.
If the guardian of a life insurance policy or other financial assets passes away before the nominee turns 18, the situation becomes complex. According to Digit Insurance reports cited by Mint, many financial assets allow for designation of an alternate guardian or trustee who would manage the proceeds until the nominee becomes an adult. If no alternate guardian is chosen, the court may appoint a new guardian or trustee to manage the funds, which can vary by state and potentially lead to delays in accessing the funds. As reported by Moneycontrol, even a perfectly completed nomination is of limited practical value if your family does not know where the accounts exist, emphasizing the importance of maintaining a secure inventory of financial assets.
The process of registering an appointee (guardian) varies depending on the financial asset, such as mutual funds, insurance policies, or fixed deposits. As reported by Mint, the documentation generally requires details of the minor and the appointed guardian, along with the guardian's KYC documents and proof of their relationship with the minor. Investors who do not wish to appoint a nominee can formally opt out by submitting the prescribed declaration through their broker, bank, or mutual fund platform account. SEBI's current framework allows up to three nominees for demat accounts and mutual fund folios, with allocation details where applicable, though each financial product and institution has its own specific nomination process. For SIP investments, investors typically need a PAN card for tax tracking, Aadhaar card for address verification, and bank proof for auto-debit mandates. Fund houses generally do not charge upfront fees to register SIPs, though expense ratios apply and some schemes may have exit loads for premature redemptions.
A properly drafted will can be important alongside nominations, as nomination alone does not settle succession rights. A nomination that made sense when you were single may not be appropriate after marriage, divorce, or the birth of children, making regular review essential. As reported by Moneycontrol, nominee details should be checked at least annually and whenever there is a major change in family circumstances or financial holdings. The arrival of children may change how you want your assets distributed, and marriage or divorce can make an old nomination inappropriate. RBI says banks should encourage nomination across eligible deposit accounts, while EPFO currently states that e-nomination can be filed and updated during the member's service period. Keeping nominee details accurate across bank accounts, investments, insurance and EPF can prevent avoidable delays when your family needs money most.