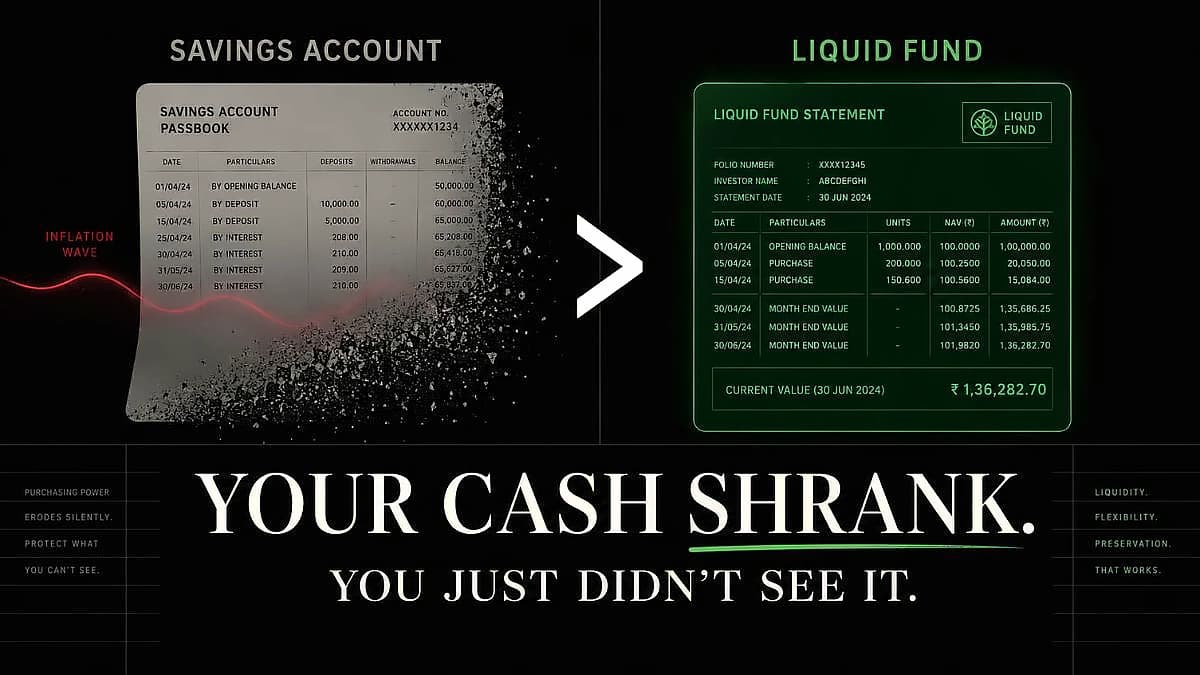
According to Mint, salary hikes may not increase savings if lifestyle expenses rise alongside income. As young professionals earn more, rising rent, lifestyle expenses and discretionary spending can absorb much of the additional income, leaving little money to build a financial cushion. The problem lies not in how much people earn, but how they manage the money that comes in each month. Uttam Agarwal, chief business officer at BajajCapital - La Premièr, explains that lifestyle expenses often rise alongside income as young professionals spend more on better housing, convenience, travel and new experiences.
According to reports from The Economic Times, lifestyle inflation extends beyond major purchases like laptops or furniture upgrades. Weekly dining out habits, frequent e-commerce shopping, and regular self-treats can significantly impact savings potential. In metro cities, the daily cost of convenience can eat into savings more substantially than traditional big-ticket expenses. The ease of access to goods and services through digital platforms has made it increasingly difficult for consumers to track their spending patterns.
As reported by The Economic Times, the convenience of online shopping and food delivery services has made it easy to lose track of spending. The availability of almost everything at just a few clicks has created a spending environment where monthly dining out frequency of four to five times can add up significantly. These everyday expenses often go unnoticed in traditional budget tracking methods, as they represent smaller, frequent transactions rather than large, infrequent purchases. According to Mint, recurring expenses like rent, loan EMIs, food deliveries, subscriptions, and eating out can gradually reduce the amount available for savings, making it difficult to see how much they add up to.
According to Mint, the key to preventing lifestyle inflation from eroding savings is to ensure that spending does not increase without a corresponding increase in savings. Agarwal recommends that working professionals aim to save and invest around 20-30% of their monthly take-home pay, depending on their financial obligations and lifestyle. For someone earning ₹1 lakh a month, this would mean targeting savings and investments of ₹20,000 to ₹30,000. The report emphasizes starting with an achievable savings amount and increasing it gradually as income rises, suggesting 20% of monthly take-home pay as a starting point for a 25-year-old, with the aim of moving towards 25-30% as earnings grow.
As reported by Mint, building wealth is difficult if unexpected expenses repeatedly force a person to dip into long-term savings. Agarwal recommends maintaining an emergency fund covering at least six months of essential expenses to help manage unexpected financial needs without immediately disrupting regular investments. The report emphasizes that adequate health insurance and term insurance can also help protect finances against unforeseen events, making these safeguards important alongside regular investing. The focus should be on balancing enjoying life today with securing one's financial future, allowing young professionals to direct part of each salary increment towards savings while maintaining room for lifestyle improvements.