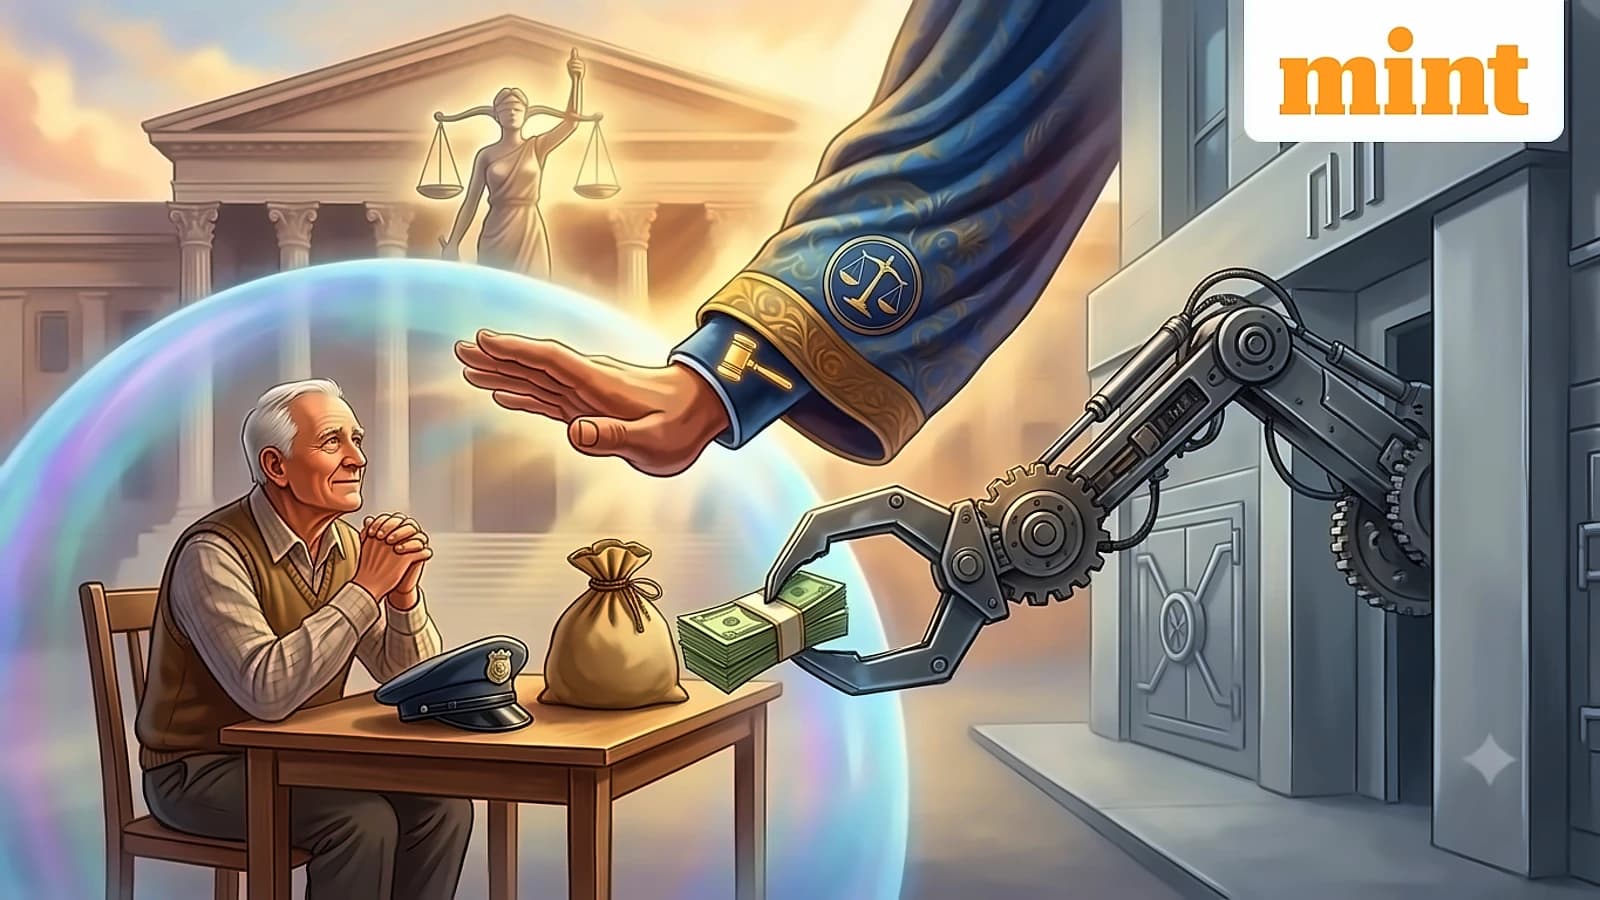
The Jammu and Kashmir and Ladakh High Court has held that pensionary benefits of a retired government employee cannot be subjected to coercive recovery measures for repayment of a loan borrowed by another person, even where the retired employee had stood as a guarantor for the loan. In its 13 November 2026 judgment in Nazir Ahmad Kuchay v. Jammu and Kashmir Bank Limited, Justice Moksha Khajuria Kazmi set aside an order of the trial court refusing interim protection and restrained Jammu and Kashmir Bank from deducting any amount from the appellant's pension account towards repayment of the loan obtained by the principal borrower. The court relied on the Supreme Court's judgment in Radhey Shyam Gupta v. Punjab National Bank, which recognised protection for pension and retiral benefits against attachment and coercive recovery measures. The High Court observed that pension is a welfare measure intended to secure the financial interests of a retired employee and his family, protect them from dependence, vagrancy and destitution, and cannot be subjected to coercive recovery merely because the employee had stood as a guarantor during his service. The court held that such a benefit could not be subjected to coercive recovery measures merely because a borrower, for whom the retired employee had stood as guarantor during his active service, had defaulted on repayment.
Kuchay, a retired police personnel and senior citizen, had stood as guarantor for a loan taken by another individual from Jammu and Kashmir Bank. When the borrower defaulted in repayment of the instalments, the bank began deducting the outstanding amounts from the appellant's bank account. By then, the appellant had retired from government service and was dependent upon his pensionary benefits for his livelihood and that of his family. The case record shows that Kuchay had approached the bank and informed it about his retirement and dependence on the pension account, but the deductions allegedly continued despite his assurances. The court noted that the appellant was admittedly a senior citizen and retired government employee, managing his and his family's sustenance on the sole income of his pension, emphasizing his vulnerable financial position. Kuchay had submitted that pension was his sole source of livelihood and that the bank had initially assured him that no further deductions would be made after he brought his retirement to its notice. However, the deductions allegedly continued, compelling him to approach the civil court seeking recovery of money and an injunction against further deductions.
The High Court observed that pension is a welfare measure aimed at securing the interests of the retired employee and his family, and could not be subjected to coercive recovery measures because of the principal borrower's failure to repay financial assistance. It noted that the appellant had stood as guarantor when he was still in active government service and was maintaining a different bank account at another branch. The court emphasized that pension is a regular payment made to a Government employee upon his superannuation as a financial assistance so that the said Government employee does not feel dependent on someone else and he is protected from vagrancy and destitution in his olden days. The court consequently restrained Jammu and Kashmir Bank from recovering any amount from the appellant's pension bank account towards repayment of the financial assistance obtained by the principal borrower, while clarifying that the bank remained free to recover the outstanding debt from the principal borrower through legally permissible means. The High Court observed that the trial court's refusal to grant interim relief was not based on sound reasoning or the true spirit of law.
Legal experts emphasize that while the ruling provides pension protection, it does not remove guarantor liability under contract law. As per Business Standard, Manu Kumar Jha, associate at PSL Advocates & Solicitors, noted that "While banks cannot dip into a pension account to recover a loan, standing as a guarantor remains a real and enforceable liability under contract law." Under Section 128 of the Indian Contract Act, 1872, a guarantor's liability is generally equal to that of the principal borrower, unless the guarantee agreement provides otherwise. Kiran Devrani, advocate at the Delhi High Court, stated that retirement security should not be jeopardised by another person's debt or default, while Supriya Majumdar, partner at Elarra Law Offices, highlighted the court's recognition of "the importance of protecting pension income, particularly when it is the family's primary source of livelihood." However, Mohit Mansharamani, counsel at SKV Law Offices, pointed to legal uncertainty as earlier single-judge decisions of the same High Court had taken a contrary view, holding that pension may lose its statutory protection after being credited to a bank account. The High Court has protected pension income from such coercive deductions while leaving the bank free to pursue the actual borrower through lawful recovery measures.
The November ruling contrasts with another judgment delivered by the same High Court in February 2026 in Chuni Lal v. Jammu and Kashmir Bank Limited. In that case, the court held that pension loses its statutory protection against attachment once it is credited to the pensioner's bank account. The February ruling allowed the bank to recover dues from the account of a retired Forest Department officer who had guaranteed a ₹15 lakh housing loan, having recovered ₹4.64 lakh after borrowers defaulted. The conflicting judgments highlight the importance of examining individual circumstances rather than assuming pension accounts are always immune from recovery. The latest order does not address these conflicting decisions, leaving uncertainty over the legal position until a larger bench or the Supreme Court settles the issue.
The judgments emphasize that pensioners should understand the financial implications before guaranteeing another person's loan, as a borrower's default can expose them to significant financial and legal consequences even after retirement. The High Court's latest ruling clarifies that pensionary benefits are protected from coercive recovery measures and constitute a welfare safeguard for retired government employees. Regarding Kuchay's claim for refund of the amounts already deducted, the court left the matter to be adjudicated by the trial court on the basis of evidence, granting him liberty to pursue the relief before it. The trial court was directed to decide the matter independently on its merits without being influenced by the observations made by the Court. Legal experts recommend that borrowers and guarantors should read guarantee agreements carefully, understand that guarantors can be pursued for repayment if borrowers default, maintain records showing pension credit sources if deductions are disputed, and seek legal advice if banks make unauthorized deductions from pension income. The cases demonstrate the complex interplay between loan guarantees, pension protection, and the financial vulnerability of retired government employees.