Varun Hemant Keskar, a Singapore-based NRI, filed his income tax return for assessment year 2024-25 on June 26, 2024, declaring total income of ₹17,73,990, which included ₹17,15,446 in long-term capital gains from mutual fund sales. According to reports from The Economic Times, the return was processed by the Central Processing Centre on September 6, 2024, accepting the declared income without any adjustments. The capital gains were subjected to tax, resulting in a liability of ₹1,70,372, which was adjusted against his TDS credit.
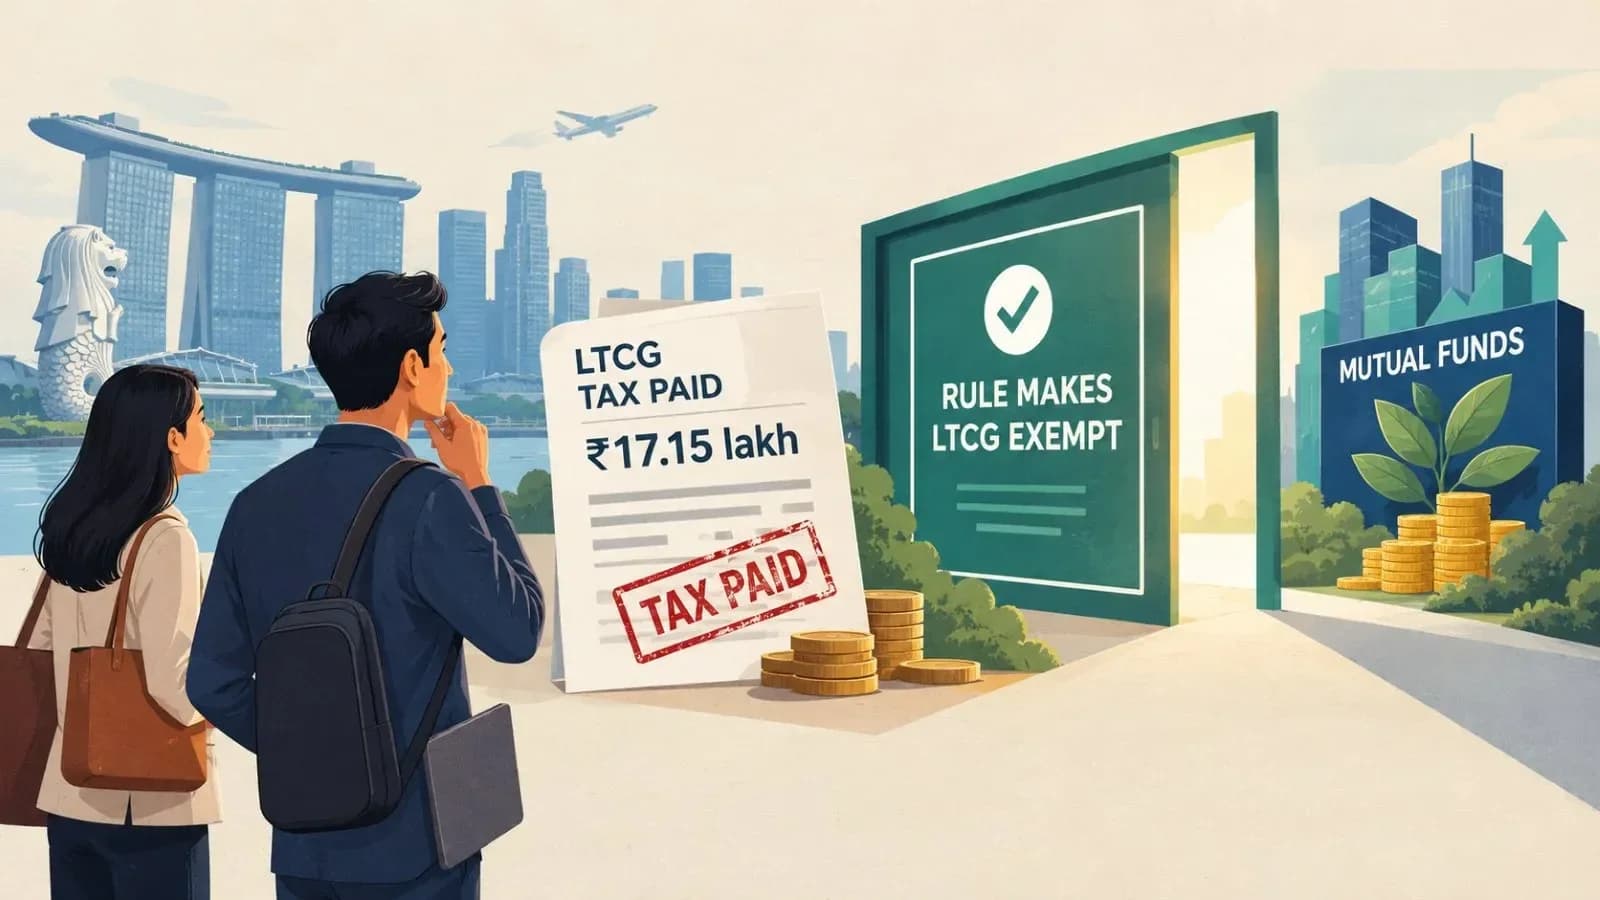
When Keskar appealed to the first appellate authority, contending that the gains were exempt under Article 13(5) of the India-Singapore Double Taxation Avoidance Agreement (DTAA), the CIT(A) dismissed the appeal on jurisdictional grounds. As reported by The Economic Times, the appellate authority held that the remedy lay in a revised return under section 139(5) or an application for condonation of delay under section 119(2)(b), stating that appellate jurisdiction could not be invoked as a substitute for these statutory remedies.
The Income Tax Appellate Tribunal (ITAT), Pune, took a different approach and set aside the CIT(A)'s refusal on October 12, 2026. According to the tribunal's order, Keskar had shown the capital gains as taxable in his return and later learned of the coordinate bench's decision in Mrs. Anushka Sanjay Shah v. ITO, where the tribunal treated the impugned capital gain as exempt under Article 13(5) of the India-Singapore DTAA. The ITAT relied on the Bombay High Court's judgment in CIT v. Pruthvi Brokers & Shareholder, which allowed new claims not made in the return, and noted its own recent decisions allowing claims raised for the first time before the CIT(A).
Rather than declaring the capital gains exempt or ordering a specific refund, the ITAT directed Keskar to furnish a revised computation of his capital gain income before the jurisdictional assessing officer. As reported by The Economic Times, the officer is required to re-compute the tax liability afresh and as per fact and law in light of the coordinate bench decision in Mrs. Anushka Sanjay Shah and grant any refund arising to the assessee after due verification of documents. The assessee has been directed to respond to notices and produce documents without seeking adjournments.
This ITAT ruling establishes important precedent for non-resident Indians who pay tax in India and later discover treaty benefits or favorable decisions. According to The Economic Times, the decision confirms that appellate authorities can entertain fresh claims not made in the return, and that the tax officer's inability to do so does not bind appellate forums. However, the relief is procedural in nature, requiring the assessee to submit revised computations and evidence, with substantive treaty benefits being applied only after verification by the assessing officer.