A pharmaceutical and medicines retailer based in Delhi faced an income tax notice after depositing ₹2.47 crore in cash into his own bank accounts. According to reports from The Times of India, the deposits were made in three savings accounts and questioned by the Income Tax Department as unexplained cash. The shop owner's explanation was initially rejected by the tax department and CIT(A), forcing him to subsequently appeal in the Income Tax Appellate Tribunal (ITAT), Delhi.
The medicine shop owner submitted comprehensive financial documents to support his explanation, as reported by The Times of India. These included an audited balance sheet, VAT returns, and sample sales invoices, demonstrating that the deposited cash came from sales generated by his pharmacy and was properly recorded in business books. The tribunal noted that the shop owner had placed several financial records before authorities to establish the source of the cash deposits, including financial statements, balance sheet, profit and loss account, bank statements, VAT returns and sample sales bills.
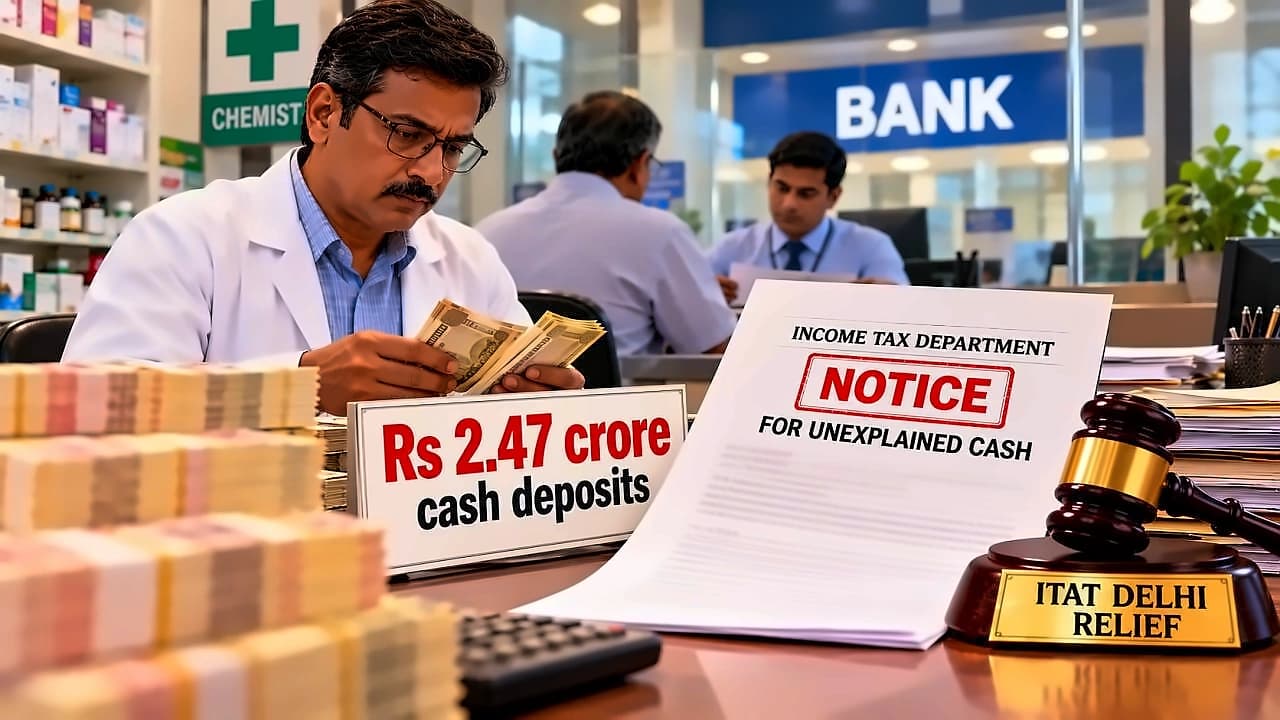
The Assessing Officer (AO) rejected the shop owner's account, stating that expenses recorded in the profit and loss statement did not have corresponding debit entries in bank accounts, and that salary and bonus payments had not been made regularly. According to The Times of India, the Commissioner of Appeals (CIT(A)) also upheld this assessment and rejected the medicine shop owner's explanation. The tribunal found that neither authority had identified any defect in the documents and evidence furnished by the man, nor had they rejected his books of accounts under Section 145.
Following a prolonged legal battle, the shop owner secured a favourable decision from ITAT Delhi on July 7, 2026, as reported by The Times of India. The tribunal concluded that the cash deposited could be directly linked to sales made during the demonetisation period, considering he operated a retail business dealing in medicines and pharmaceuticals. The ITAT Delhi ruled: "We noted that the explanation submitted by the assessee along with evidence regarding the availability of cash is enough to prove the assessee's claim, and we find no infirmity in the same."
According to Chartered Accountant Ashish Niraj, Partner at A S N & Company, as reported by The Times of India, during scrutiny of cash transactions relating to the demonetisation period, income tax officials examined each deposit with suspicion, placing the responsibility on taxpayers to establish that the transactions were genuine. Niraj explained that the tribunal was satisfied with the material placed before it and accepted that the assessee had been able to establish the source of the deposits through cash withdrawals, his personal savings and savings belonging to family members. He noted that this judgement gives learning that even if you have done cash transactions in crores, if supporting documents are properly kept, negative assessment can be challenged and won.