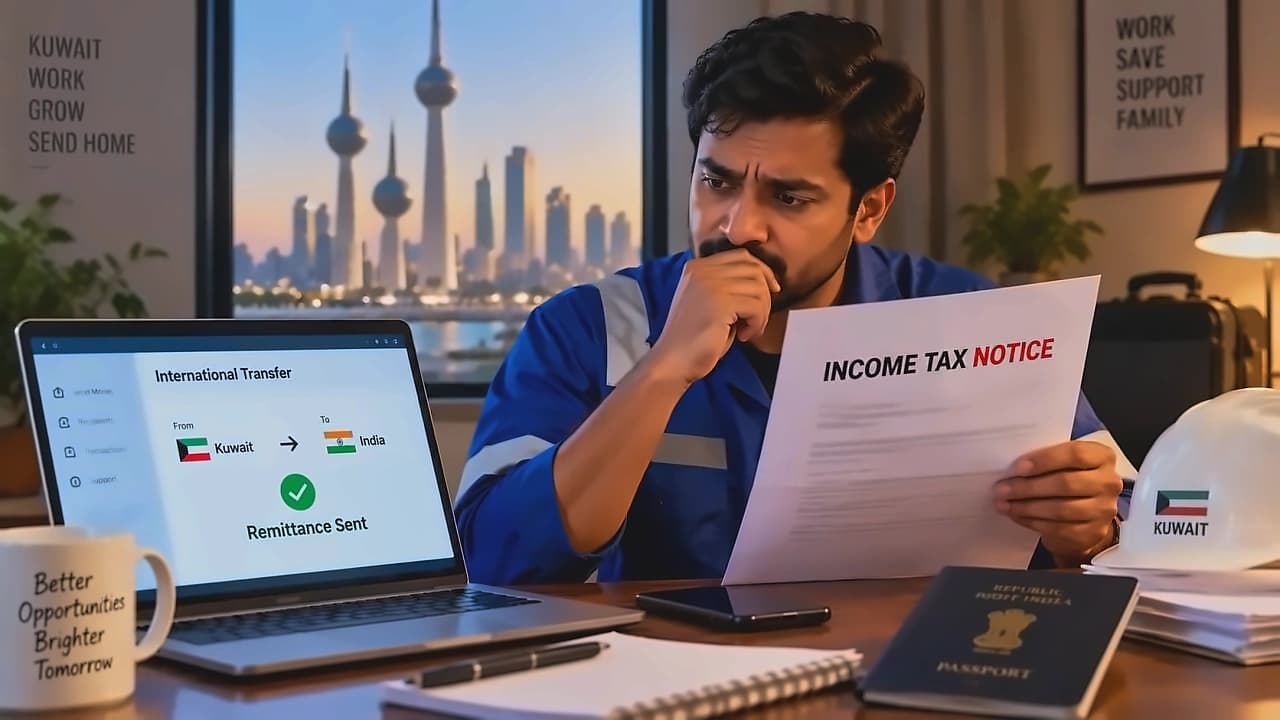
An Indian working in Kuwait received an income tax notice after failing to file an Income Tax Return (ITR) despite remitting more than ₹1 crore to his bank accounts in India. According to reports from The Times of India and Mint, the man had moved to Kuwait to work in the oilfields at Mina Al-Ahmadi and was earning a decent salary. His salary was credited to his account with the National Bank of Kuwait, from where he transferred funds to his ICICI and HDFC Bank accounts in India, including NRE and NRO accounts. The situation could have been easily resolved if the man had filed an ITR explaining this money, but the problem escalated because he had not filed any original Income Tax Return. As reported by Mint, the case was filed under ITA 394/AHD/2026 with the Assessment Year being 2019-20.
As reported by The Times of India and Mint, the Income Tax Department's SFT/Insight system showed that as of December 31, 2018, he had ₹2.49 crore with HDFC Bank, ₹1.09 crore with ICICI Bank and an insurance policy worth ₹3.77 lakh with ICICI Prudential Life Insurance Company. The Income Tax Assessing Officer treated the entire ₹3.63 crore reported through SFT as unexplained money under Section 69A, since there were no documents establishing that the funds represented foreign remittances, accumulated savings or another identifiable source. His assessed income was consequently determined at ₹3.63 crore and taxed under Section 115BBE. The real complications started because the taxpayer had not filed an original income tax return and initially filed a return declaring 'nil income' but did not provide complete bank statements, account details and reconciliations.
According to The Times of India and Mint, the man challenged the assessment and filed an application under Rule 46A seeking admission of additional evidence. The documents included statements of his National Bank of Kuwait account, salary details from his employer, Indian NRE account statements and other records intended to establish the movement of his Kuwait earnings into his Indian accounts. During remand proceedings, the AO examined the additional evidence and issued notices to ICICI Bank, HDFC Bank and ICICI Prudential Life Insurance Company to verify the SFT-reported figures. The remand report highlighted that while the source of certain deposits, particularly fixed deposits with ICICI Bank, were explained, the figures reported under SFT could not be reconciled with actual bank statements. In the case of ICICI Bank, although statements and FD details were furnished and an amount of ₹1.04 crore was verified as explained through foreign remittances and FD rollovers, the balance money could not be correlated.
As reported by The Times of India and Mint, the ITAT Ahmedabad D Bench, comprising Smt Annapurna Gupta and Mr Siddhartha Nautiyal, passed its order on April 24, 2026, granting partial relief. The tribunal relied on two Gujarat High Court rulings - Anilkumar Ramabhai Patel v. ITO and Nitin Mavji Vekariya v. ITO - establishing that where funds in an NRE account are shown to have originated from foreign earnings, Section 69A cannot be applied to treat those funds as unexplained money. According to Mint, during the appeal before ITAT Ahmedabad, the taxpayer submitted his Kuwait bank statements, salary details, Indian bank records and other essential documents as directed. The tribunal found that the ₹5.52 lakh addition relating to ICICI Bank and the insurance policy could not be treated as unexplained merely because SFT figures did not reconcile with bank records, and therefore deleted this addition. However, the tribunal retained the ₹2.49 crore HDFC Bank addition and ₹5.52 lakh as unexplained money. Regarding the HDFC Bank amount of approximately ₹2.50 crore, ITAT Ahmedabad noted that the addition was based solely on a cumulative figure reported through SFT, without any transaction-wise details or supporting material.
According to The Times of India and Mint, the tribunal took a different view of the approximately ₹2.50 crore reported in relation to HDFC Bank, noting that the addition was based on a cumulative SFT figure without transaction-wise details. The remand report recorded that the Insight portal no longer contained detailed underlying data for these figures, further complicating verification. The tribunal directed that no addition should be made if the funds are found to represent foreign income remitted to India or subsequent redeployment of those funds, and sent the HDFC Bank issue back for fresh verification rather than deleting the addition outright. The ruling did not grant final relief concerning the entire amount, but it protected the man from an addition founded solely on unverified SFT data and placed an obligation on the Assessing Officer to establish the underlying facts before invoking Section 69A. The appeal was partly allowed for statistical purposes, with the addition of ₹5.52 lakh deleted while the addition of approximately ₹2.50 crore was remanded for fresh examination. As reported by Mint, this ruling clearly highlights that foreign salary remittances cannot be automatically categorised as 'unexplained income' and emphasizes the importance of maintaining proper records for NRIs.