A Mumbai woman has secured relief after the Income Tax Department treated part of her precious assets as unexplained income. According to reports from The Times of India, the Mumbai bench of the Income Tax Appellate Tribunal deleted tax additions totalling ₹11.23 lakh in its order dated 14 July 2026 (ITA No. 3073/Mum/2026), accepting her explanation that the jewellery and silver had accumulated through marriage gifts, inheritance and family acquisitions over several decades. As reported by Surana & Surana, the tribunal's ruling was particularly significant as it clarified that CBDT Instruction No. 1916 does not create an absolute tax exemption or statutory ceiling for jewellery holdings, but rather provides a practical benchmark for assessing family possession.
During the search at her residence and bank lockers maintained with Saraswat Sahakari Bank, officials found 392.71 grams of gold jewellery, 27.4 carats diamond jewellery containing 161.33 grams of gold, and 800 grams of silver articles and coins. The two bank lockers contained another 10.4 kg (10kg+400 grams) of silver-mix articles. The Income Tax Department had initially suspected that Mrs Kelkar might have several high-value gold, diamond, and silver jewellery items, leading to multiple tax notices before the comprehensive search operation. The precious articles were valued at approximately ₹29.49 lakh, representing a substantial portion of her total wealth.
The Assessing Officer accepted purchase bills for 195.996 grams of gold jewellery and applied CBDT Instruction No. 1916 to another 231.714 grams. According to Surana & Surana, the AO considered a 700-gram family benchmark, comprising 500 grams for a married woman and 100 grams each for her husband and son. However, the AO treated certain gold and silver articles as unexplained and made an addition of ₹19.4 lakh under Section 69A, assessing unexplained income at this amount along with penalties. The Commissioner of Income Tax (Appeals) later deleted the addition relating to diamond jewellery but sustained ₹8.10 lakh for 258 grams of pure gold and ₹3.12 lakh for silver articles. Mrs Kelkar, represented by Chartered Accountant Punit Shah before ITAT Mumbai, successfully appealed the remaining additions.
The tribunal examined the silver articles in the context of Kelkar's long married life, inheritance and customary family acquisitions. As reported by Surana & Surana, ITAT Mumbai found it inconsistent to accept ordinary gold jewellery and diamond-studded gold jewellery forming part of the same family holding, but treating the pure gold as unexplained solely because of its physical form. More importantly, the tribunal noted that neither the AO nor the CIT(A) had brought any material on record to establish that the pure gold was a fresh acquisition during the relevant year from undisclosed income. The mere absence of old purchase bills was not considered conclusive where Mrs Kelkar's explanation was based on marriage gifts, inheritance and accumulation over several decades. After excluding the 195.996 grams supported by purchase bills, the remaining ordinary jewellery, gold in diamond jewellery and pure gold totalled 651.044 grams, within the 700-gram benchmark recognised by the AO.
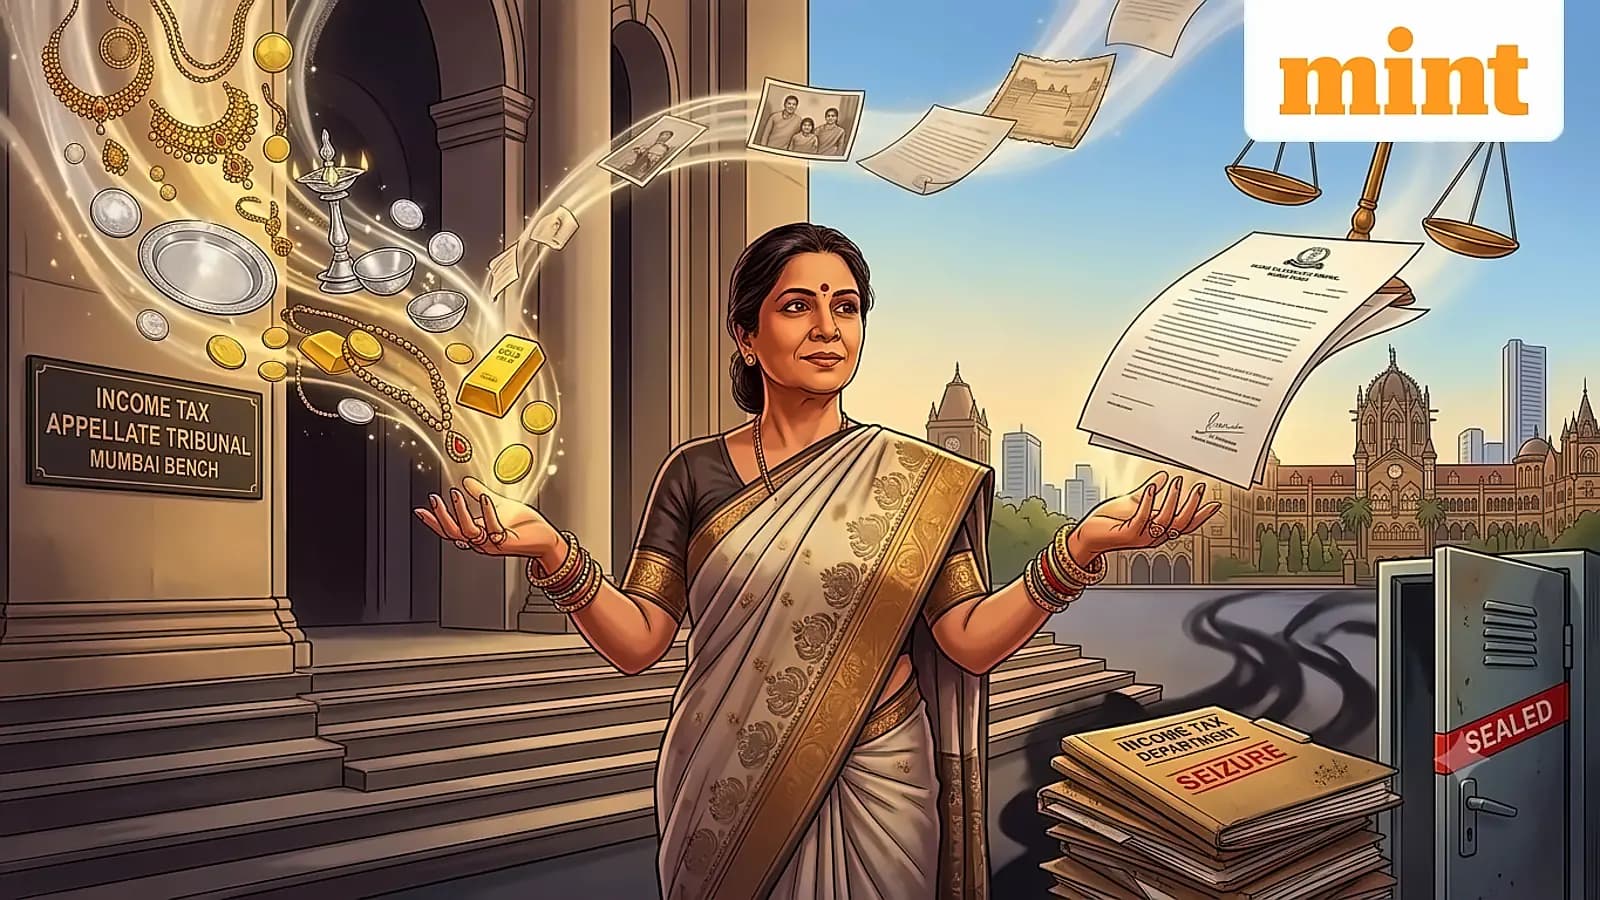
According to The Times of India, Kelkar and her husband had reported aggregate gross total income of about ₹4.55 crore over five assessment years. The ITAT clarified that its decision was based on the facts of this case and does not mean that all pure gold or bullion automatically gets the benefit of CBDT Instruction No. 1916. As reported by Surana & Surana, ITAT Mumbai relied upon the Indore ITAT ruling in Dinkar Laxman Mujumdar v. DCIT concerning silver articles and found that the Revenue had not brought sufficient material to establish that Kelkar's silver represented a recent acquisition from undisclosed income. The tribunal emphasized that this assessment must take into account the taxpayer's period of marriage, family customs, inheritance, streedhan, social and financial status and other surrounding circumstances.