The Income Tax Appellate Tribunal (ITAT) has clarified that renovation and re-modification expenses of an existing residential house are exempt under Section 54F of the Income Tax Act, provided they constitute construction of a residential house. As per the latest ITAT ruling in Juveria Begum Vs ITO (ITAT Hyderabad), the Tribunal held that such expenses are allowable as they would amount to construction of a residential house, with the only requirement being that construction should be completed within three years from the date of transfer of the original asset. The ruling specifically addressed cases where taxpayers had purchased existing residential properties and subsequently invested in renovation work, with the ITAT noting that the CIT(A) had incorrectly followed decisions against the assessee while ignoring favorable decisions from Karnataka and Calcutta High Courts.
A Mumbai bench of the Income Tax Appellate Tribunal (ITAT) has allowed a taxpayer's claim for Section 54 exemption on investments made in more than one property, while also allowing expenses incurred to make a newly purchased flat habitable. The ruling, in Vivek Juneja v. ACIT, ITA No. 8512/Mum/2025, concerns Assessment Year 2013-14 and was pronounced on 29 May 2026. The case involved an immovable property jointly owned by Juneja and his mother, after which he received ₹23.76 crore representing his 50% share of the sale consideration.
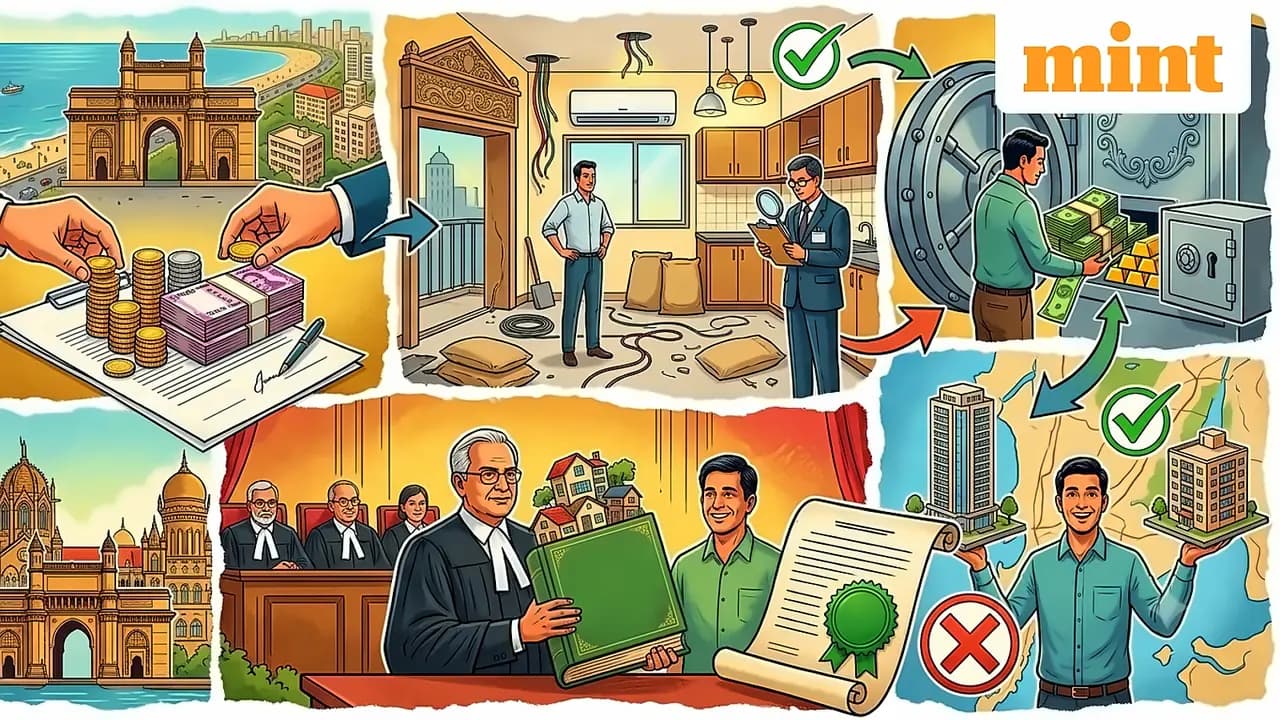
Juneja purchased a new flat in Raj Classic for ₹4.90 crore and incurred ₹40.44 lakh on work in the property. The remaining ₹8.43 crore was deposited in the Capital Gains Account Scheme (CGAS). He subsequently withdrew amounts from the CGAS and invested in two other properties. The Assessing Officer questioned both the expenditure on the new flat and the taxpayer's claim for Section 54 relief on subsequent investments, particularly regarding ₹20.44 lakh spent on air conditioning, painting, polishing, furniture, kitchen cabinets and appliances. The CIT(A) also upheld the disallowance treatment, allowing only ₹20 lakh on an estimated basis and disallowing the remaining ₹20.44 lakh.
The ITAT disagreed with the Assessing Officer's assessment, noting that the flat was not habitable when Juneja acquired it and that documents and invoices showed the disputed expenditure was towards civil and electrical work. The Tribunal found that the department's conclusion was not supported by the evidence and directed the AO to delete the entire ₹20.44 lakh disallowance. Regarding the larger dispute, the ITAT rejected the AO's argument that once Juneja had already claimed Section 54 relief for the Raj Classic flat, he could not claim further relief for additional properties. The Tribunal also noted that the tax authorities had allowed the taxpayer's mother's identical claim arising from the same sale transaction, which further supported the taxpayer's case.
The ITAT focused on the wording of Section 54 applicable during AY 2013-14, which referred to investment in 'a residential house'. The law was subsequently amended to use the expression 'one residential house in India', with effect from 1 April 2015, applicable from AY 2015-16 onwards. The Tribunal relied particularly on the Bombay High Court's decision in Krishnagopal B. Nangpal v. DCIT, noting that courts had interpreted 'a residential house' in the pre-amendment provision as capable of including more than one residential house. The Tribunal held that under the earlier law applicable to this case, Section 54 did not restrict the taxpayer's exemption to investment in only one residential house, and that investment in more than one qualifying residential property could receive the benefit, subject to other conditions of Section 54.
The ruling is consequently relevant primarily to older property transactions governed by the pre-April 2015 Section 54 provision. It should not be read as permitting multiple-house Section 54 claims under the post-amendment regime. The ITAT held that the taxpayer could not be denied the Section 54 benefit for AY 2013-14 merely because the capital gains were invested in more than one property, and that the amount deposited in the CGAS was not taxable in the year under consideration merely because the taxpayer had already claimed Section 54 relief on the Raj Classic property. The ruling can support taxpayers with pending disputes for such earlier assessment years, particularly those involving properties sold up to 31 March 2014.