According to SEBI's Investor Survey 2025, Indian households are demonstrating a more strategic approach to money management. Households set aside about one-quarter of their monthly income, with 15% going towards savings and 9% towards investments. Among households that invest in securities-market products, 17% goes into investments. The survey reveals how closely financial decisions are linked to life goals, with children's education leading as the primary objective, followed by supporting family, growing wealth, and buying a house. Retirement emerges as the top goal for just 4% of households. This evolution suggests a different starting point: not the product, but the purpose - what does this money need to achieve, and when will it be needed.
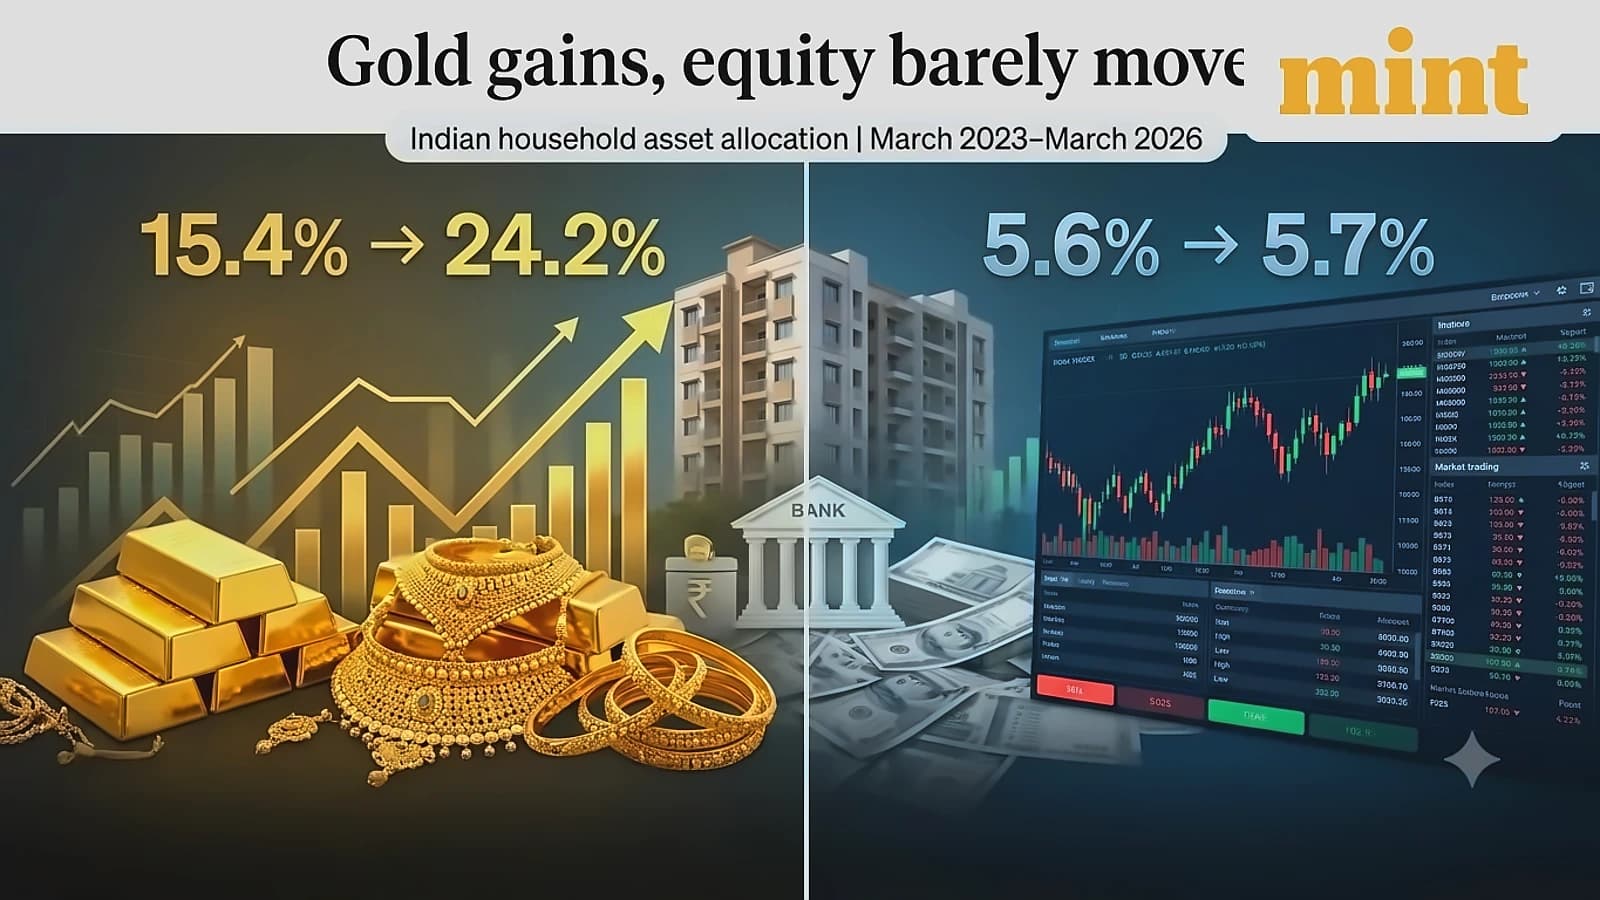
The World Gold Council (WGC) reports that India's gold demand fell 6% year-on-year to 131 tonnes in April-June 2026, yet spending on gold hit a record for that quarter at ₹1.98 lakh crore, up 50% as domestic prices rose nearly 60%. As reported by the WGC, ₹1 lakh bought about 10.5 grams of gold a year earlier, but only about 6.6 grams now. Consumer behavior is adapting to these price pressures, with a WGC-Kantar survey finding consumers opting for lighter, lower-carat jewellery and smaller purchases. The survey indicates that buyers are becoming more conscious of how gold purchases fit into their broader financial planning, with the question no longer only about how much to save or spend, but also about what that money is meant to achieve.
According to AMFI data, SIP contributions reached a record ₹32,297 crore in August 2026, up 14% year-on-year, while SIP accounts making contributions crossed 10 crore for the first time. This growth demonstrates how investing has become a visible part of household finances. However, SEBI's survey found that 62% of investors make some or most decisions based on finfluencer recommendations, highlighting the need for informed decision-making processes. The easier access to information means investors can move from a market headline to a stock tip within minutes, but the challenge lies in knowing what deserves attention and whether it fits into their financial plans.
The analysis suggests that festive spending should be approached with clear purpose in mind. A practical approach involves splitting festive bonuses into three categories: money for immediate expenses, a cushion for emergencies, and money that can be invested for longer-term goals. This methodology helps ensure that each festive purchase serves a specific financial purpose rather than being treated as discretionary spending. The report emphasizes that traditional money practices like gold buying during festivals can continue while evolving into more strategic financial decisions. This becomes more relevant as investing becomes easier, with regular investing now a visible part of household finances.