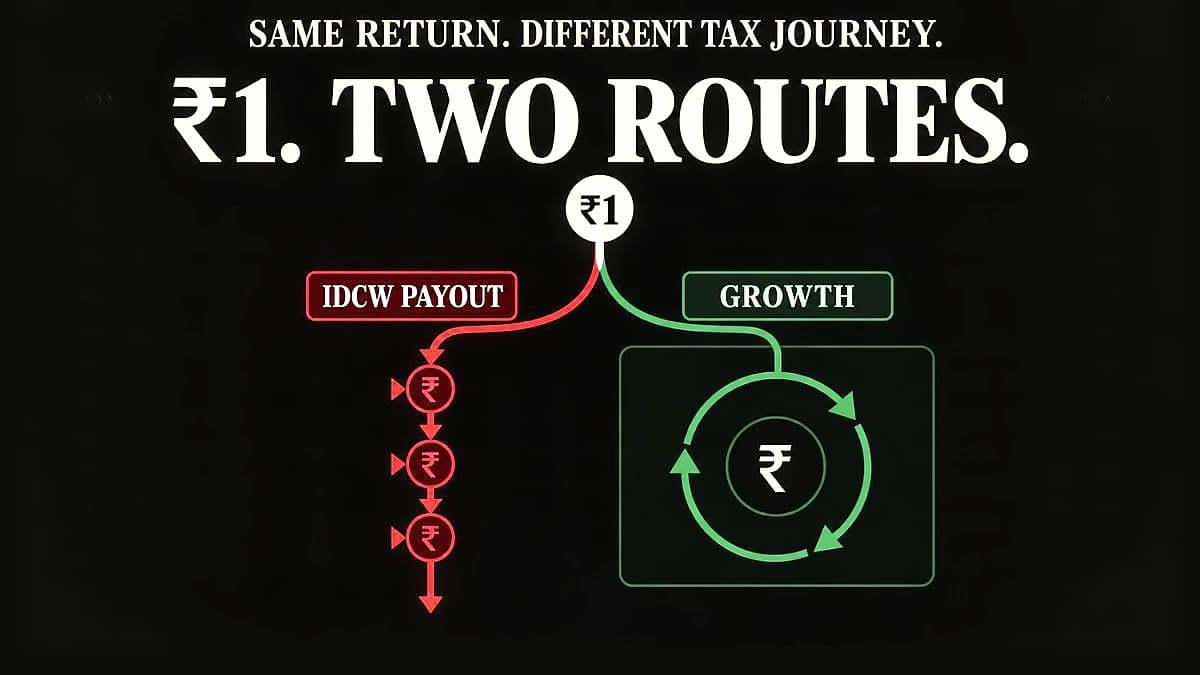
The Individual and Dependent Children's Welfare (IDCW) scheme and Growth Option present distinct tax treatment approaches for mutual fund investors. According to reports from IDCW vs Growth Option, IDCW is taxed at slab rates, while Growth Option defers taxation until redemption. This fundamental difference in tax timing creates significant implications for investors' overall tax liability.
The tax deferral advantage of Growth Option becomes particularly evident when analyzed in real rupee terms. As reported by IDCW vs Growth Option, the deferred tax payment allows investors to reinvest their returns, potentially compounding the benefits over time. However, this advantage comes with the risk that tax liability may increase significantly upon redemption, depending on market performance and the investor's tax bracket at that time.
Both investment options operate under specific tax deduction at source (TDS) regulations that investors must understand. According to reports from IDCW vs Growth Option, TDS rules vary between the two schemes, affecting the immediate cash flow from mutual fund investments. The regulatory framework governing these tax treatments provides the foundation for comparing their long-term financial implications.
A critical factor in the comparison involves the Section 87A exception, which provides specific tax benefits for certain mutual fund investments. As reported by IDCW vs Growth Option, this provision can significantly impact the overall tax efficiency of both investment options. The Section 87A exception offers potential tax savings that investors should evaluate when making their choice between IDCW and Growth Option schemes.