According to tax expert Balwant Jain, inherited property can be transferred to a Hindu Undivided Family (HUF) as a gift, but with important tax implications. Before June 17, 1956, inherited assets were treated as ancestral property with shared ownership among family members. However, after June 17, 1956, all inherited assets became personal property of the individual inheriting them, making them ineligible for direct HUF treatment. The property must be gifted to the HUF rather than transferred as ancestral property.
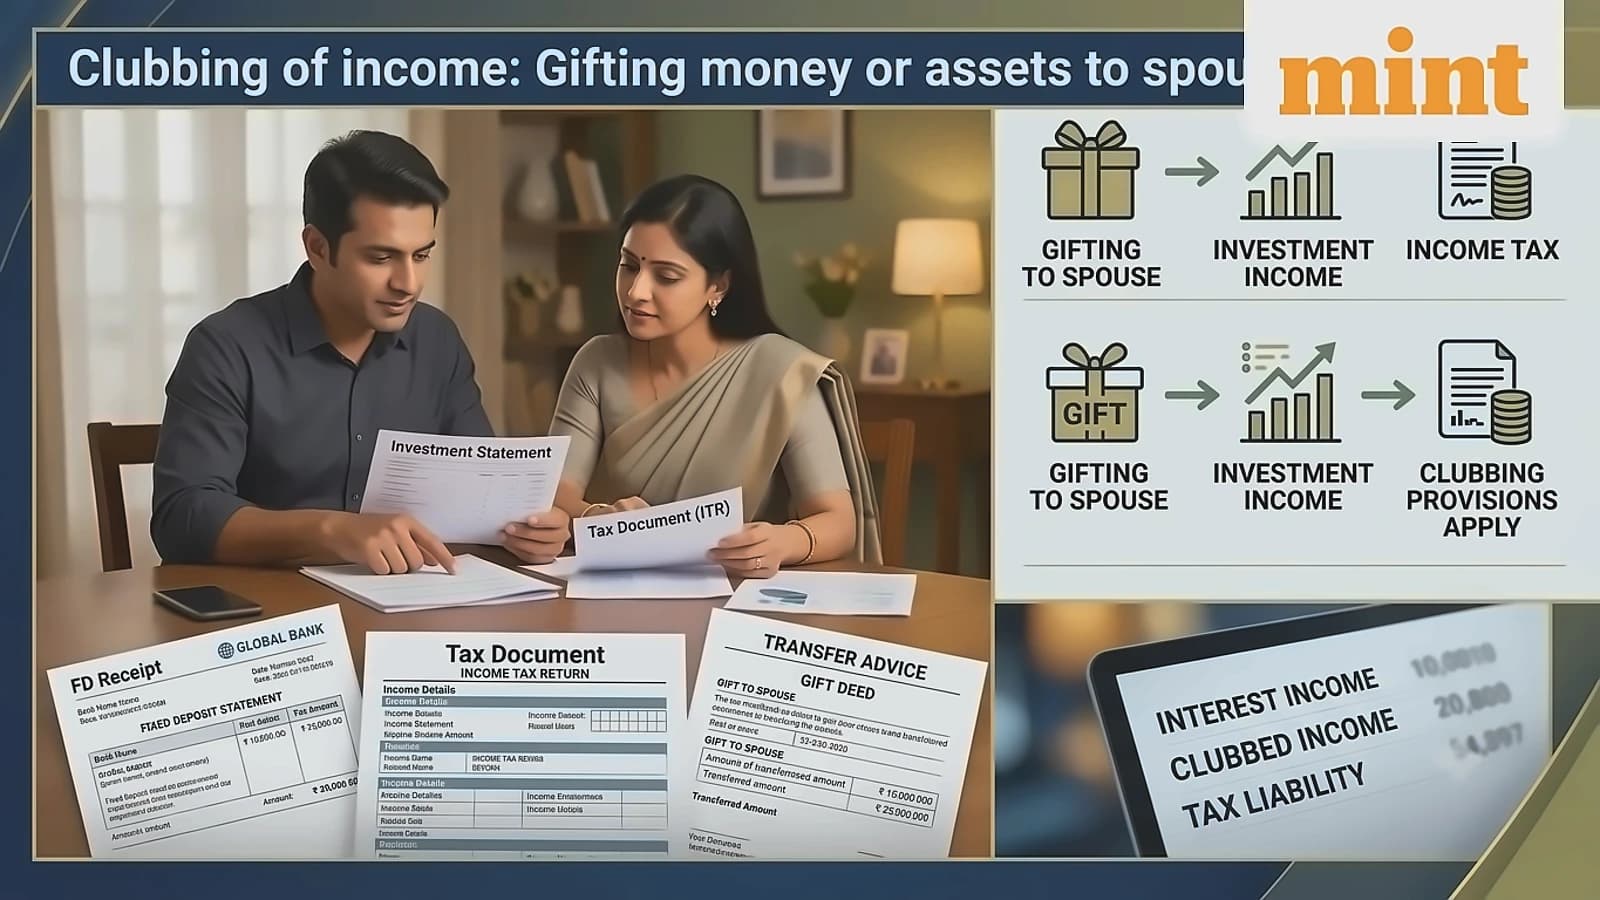
As reported by Balwant Jain, Section 99(3) of the Income Tax Act 2025 introduces clubbing provisions that apply to income accruing from gifted property. The clubbing provisions continue to apply until the HUF is fully partitioned. Even after full partition, clubbing provisions remain applicable for income arising from the spouse's share of the asset. These provisions apply regardless of whether the property is sold or converted into other assets, ensuring ongoing tax implications for the family unit. The HUF is not subject to taxation along with its members, creating a distinction between individual and family earnings.
According to the tax expert, HUF creation cannot be established by party agreement and requires proper documentation. The HUF existed on the birth of the elder son and came into existence naturally without requiring formal deeds. For tax purposes, an affidavit is required when applying for a PAN card, which must include details of members, coparceners, and the date of HUF formation. This documentation serves as the official record of the family's HUF structure for tax compliance. An HUF is automatically deemed to exist in eligible Hindu families after marriage, but requires obtaining a PAN card in the HUF's name and moving eligible assets to the HUF.
As explained by Balwant Jain, gifts received from relatives are not treated as income for HUF purposes, eliminating immediate tax complications. However, the clubbing provisions ensure that income from gifted property remains part of the family's combined taxable income. The HUF can avail deductions under Section 80C for eligible investments and expenses, Section 80D for health insurance premiums, and Section 24(b) for home loan interest on property. An HUF can be partitioned either fully or partially, with full partition resulting in the HUF no longer being a taxable entity. After partition, the HUF will be subject to regular tax filing obligations as applicable to all eligible taxpayers.