Spouses generally gift money or assets to each other, but such transfers do not automatically shift the tax liability to the recipient. According to reports from Mint, the Income-tax Act contains clubbing of income provisions that can require income from assets transferred to a spouse to be taxed in the hands of the spouse who made the transfer. Isha Sekhri, Founder of Isha Sekhri & Associates LLP, explained that these provisions are an anti-avoidance mechanism designed to prevent taxpayers from reducing their tax liability by transferring income-generating assets to a spouse in a lower tax bracket, while reducing the family's overall tax liability.
The provisions generally apply when one spouse transfers money or an asset to the other without adequate consideration, subject to certain conditions. As reported by Mint, clubbing can apply when the asset or money is given without payment, or for less than its fair value. The couple must be married when the transfer is made and when the income is earned. Sekhri noted that transfers made before marriage are not covered, and transfers made for adequate consideration (payment at fair value) can also fall outside the clubbing provision.
The income arising from the gifted asset is included in the income of the spouse who originally gave it. According to Mint reports, the income should be disclosed in that spouse's ITR under Schedule SPI, with the other spouse's PAN reported as required. For example, if a husband gifts ₹10 lakh to his wife and she invests the money in an FD, the interest earned would be clubbed with the husband's income and reported in his ITR. The husband will pay tax on this interest, even though the FD is in the wife's name. The same principle applies to dividends or capital gains from investments made with the gifted money.
Sekhri pointed out that clubbing applies to the income directly earned from the gifted money or asset, while income earned by reinvesting that first-generation income is treated differently. As reported by Mint, for example, if ₹10 lakh is gifted by the husband and generates ₹70,000 of FD interest, and the wife subsequently invests that ₹70,000 and earns another ₹5,000, the second-generation income is her own income and is not clubbed. She emphasized that if the money genuinely belongs to the spouse receiving it—for example, from their own salary, inheritance or assets owned before marriage—there is no clubbing issue. Nishant Shanker from Navraj Global Advisors explained that under Section 99(1)(a)(ii) of the Income-Tax Act, 2025, if money gifted to a spouse is invested, the resulting interest or income is generally taxable in the donor's hands, though income earned from reinvesting such income is generally taxable in the recipient's hands.
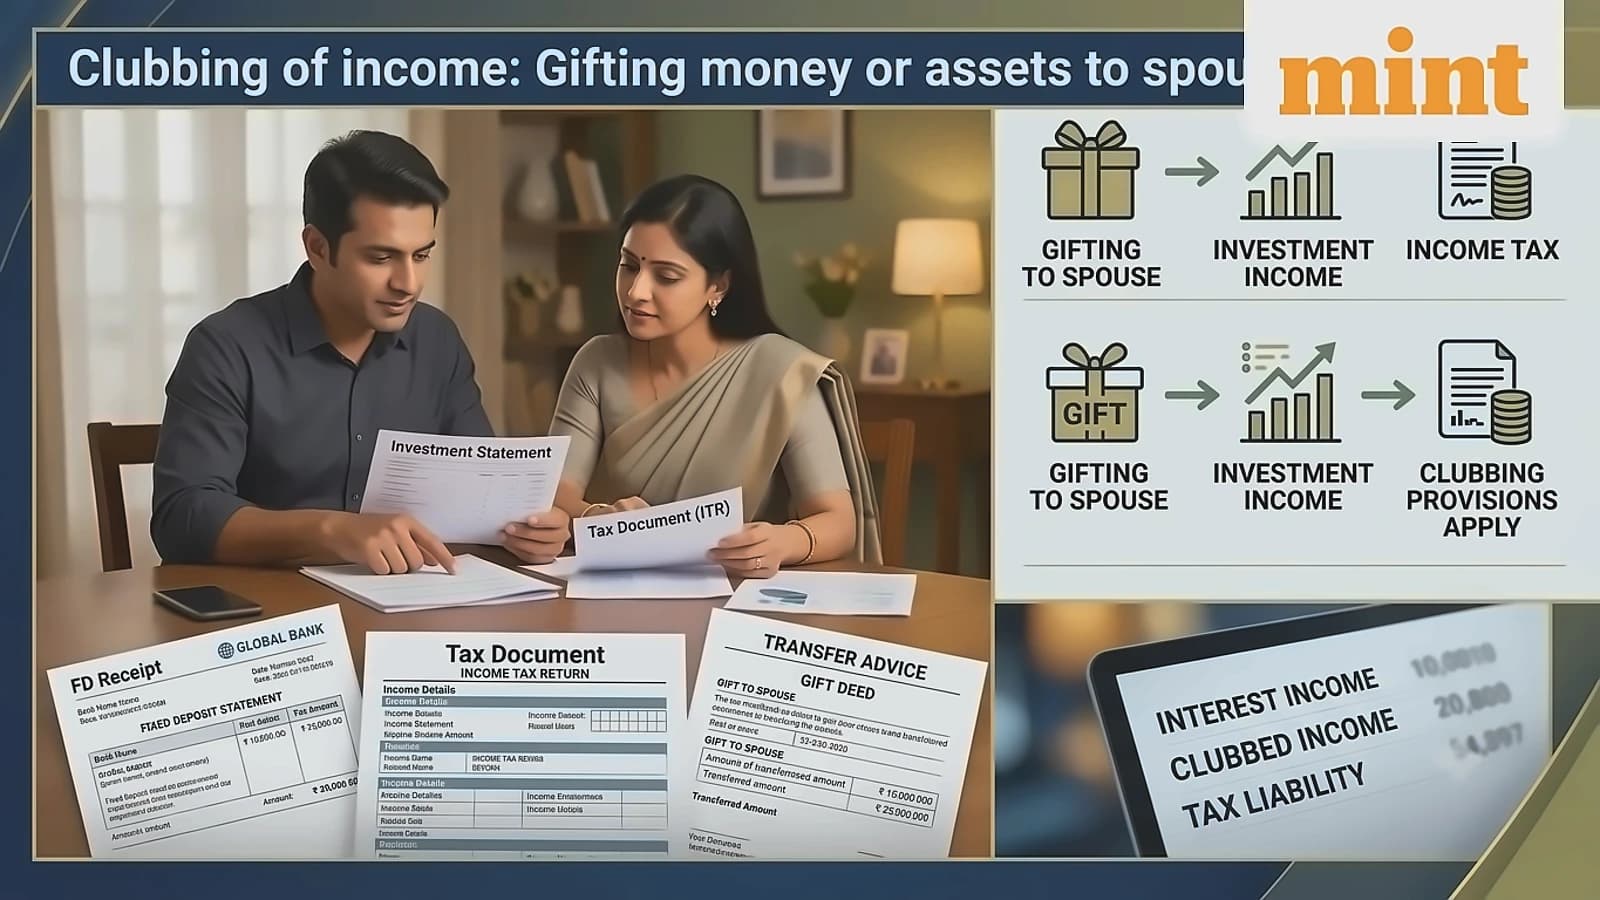
Sekhri recommended maintaining a clear documentary trail for all transactions. According to Mint reports, taxpayers should retain the loan agreement and evidence of interest being charged or accrued for loans, and maintain the gift deed and bank records for gifts. Taxpayers should also retain FD, demat and mutual fund account-opening documents showing the source of funds and maintain separate workings for first-generation and second-generation income. She noted that if one spouse funds an investment held in the other spouse's name, it can attract an income tax notice, and the income tax department may examine information reported in AIS, TIS and Form 26AS, including FD, mutual fund and demat transactions appearing against the two PANs. The key takeaway is that gifting money to a spouse does not automatically transfer tax-related liabilities on the income it generates, with the source of the investment and the nature of the income being crucial factors in determining applicable tax treatment.