India now has 1,687 individuals with a net worth of ₹1,000 crore or more, according to the M3M Hurun India Rich List 2025. As reported by Mint, two-thirds of them, or 1,115 people, are self-made, up from 1,008 the previous year. Reinforcing this trend, 74% of new entrants are first-generation entrepreneurs. Below this threshold, many more Indian founders are crossing into high-net-worth individual (HNI) status through IPOs and secondary stake sales. In their work with first-generation wealth creators, financial experts frequently encounter a similar pattern where net worth is concentrated largely in one operating business, along with a sizeable listed stake, some real estate, a few private investments made on instinct, and increasingly assets abroad.
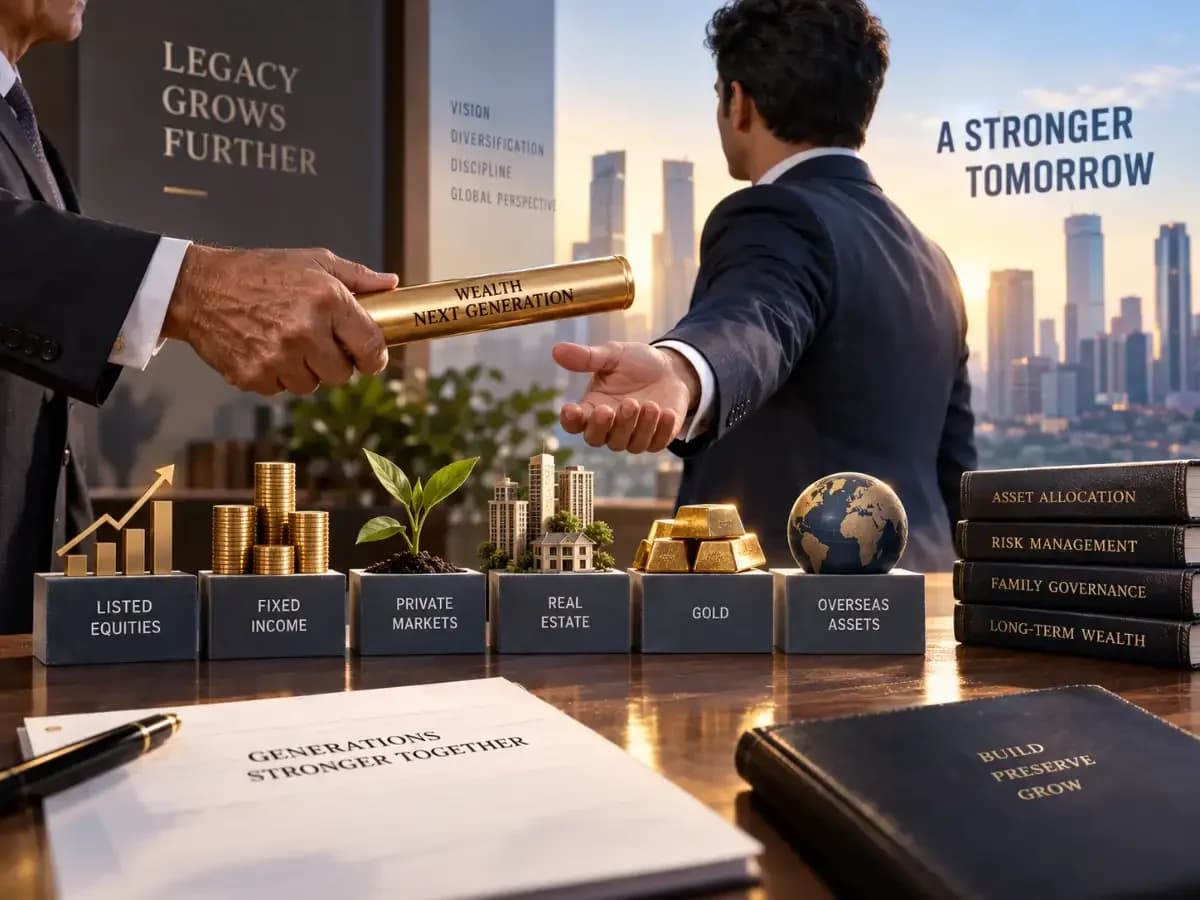
According to Mint, the challenge shifts from creating wealth to protecting, diversifying and transferring it across generations as wealth compounds. Most founders understand the building blocks: diversification, liquidity, risk management and estate planning. The real transition is from being an operator of a business to becoming a steward of family wealth, preserving the entrepreneurial instinct that built the fortune while ensuring the family balance sheet is resilient, well-structured and built to endure. A tailored financial framework for a founder can include diversification across multiple asset classes, maintaining liquidity buffers, and implementing structured risk management strategies.
As reported by Mint, at ₹10 crore, chasing an extra percentage point of return feels meaningful. At ₹500 crore, avoiding a single portfolio accident matters more. This requires a customised "investment charter" that defines family objectives, risk thresholds and other non-negotiables, while setting a timeline for gradually moving wealth out of the operating business and into a diversified portfolio. The core portfolio should be anchored in equity, fixed-income and multi-asset strategies, while entrepreneurs can leverage their domain expertise for high-conviction, non-traditional opportunities. Building a business demands extraordinary boldness, but preserving wealth across generations requires structured governance, unemotional discipline and risk management, underpinned by the core principles of preparedness and simplicity.
According to Mint, promoter stakes often come with lock-in periods, pledged-equity obligations and market scrutiny around any promoter sale. Private investments can take years to deliver exits. The HNI portfolio should maintain a dedicated 10–15% liquid buffer in high-grade, accessible instruments to ensure the family is never forced to liquidate long-term assets during critical situations or market downturns. This liquidity cushion provides the flexibility to navigate market volatility and capitalize on opportunities while maintaining the family's financial security.
As reported by Mint, PwC's latest Family Business Survey found that 36% of Indian family businesses have no clear succession plan, compared with 28% globally. For first-generation founders, separating business control from family wealth can be new and unfamiliar territory, while cultural discomfort around discussing death can make the process even more difficult. As a result, wills are often deferred, nominations are mistaken for estate plans, and joint holding is assumed to ensure continuity. However, joint holding ensures continuity of access, not necessarily continuity of ownership. The deceased holder's share may still be governed by applicable succession laws. These tools can transform succession from an event into a well-governed transition: a Will that clearly defines inheritance, a Family Trust that preserves and governs family wealth across generations, and a Family Constitution that establishes principles for ownership, decision-making and family governance. Where family members or assets span multiple countries, these structures must also work seamlessly across jurisdictions, ensuring a legacy is not disrupted by borders.