A 26-year-old earning ₹40,000 per month should prioritize adequate health insurance coverage over premium cost considerations, according to industry experts. As reported by Mint, the first priority should be choosing an adequate sum insured, as medical expenses can rise significantly during hospitalization, surgery, or prolonged care. Rather than selecting plans solely based on low premiums, buyers should compare coverage offerings and restrictions that could affect claims, including room-rent limits, co-payments, disease-specific sub-limits, waiting periods, exclusions, and the insurer's cashless hospital network.
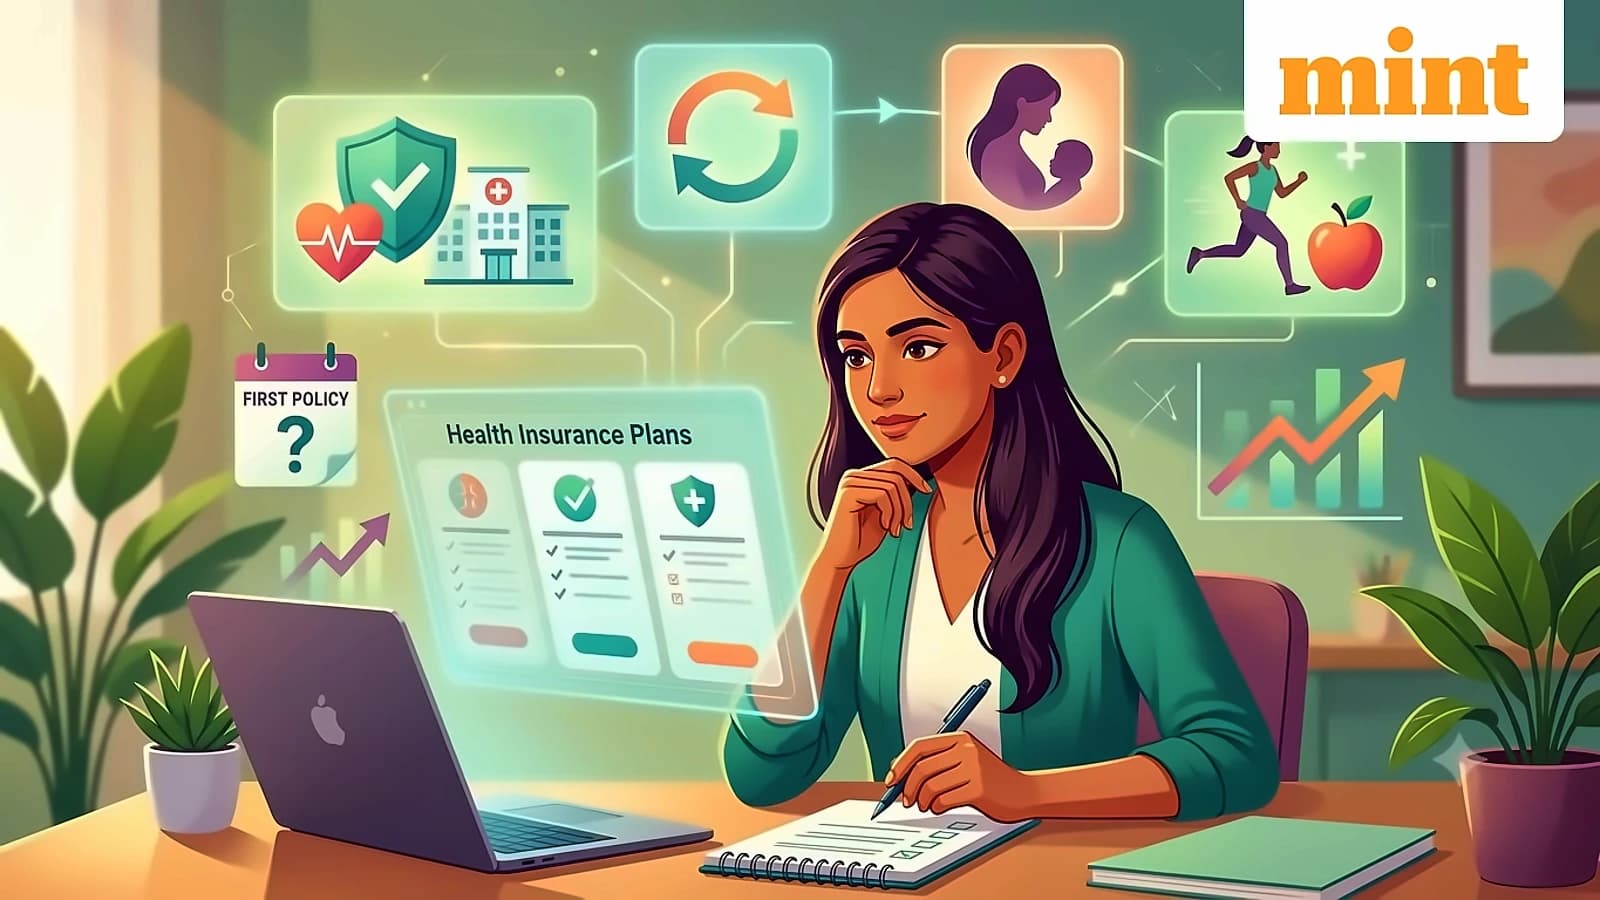
For young buyers on limited budgets, not every add-on is essential when purchasing their first policy. According to Mint, focus should be on benefits that meaningfully improve coverage without unnecessarily increasing premiums. A restoration benefit replenishes the sum insured if exhausted during the policy year, while a no-claim or cumulative bonus can increase available coverage over time for claim-free policyholders. A super top-up policy can increase coverage at potentially lower cost than buying a larger base policy, covering eligible expenses after a specified deductible is crossed.
Even if maternity expenses are not immediate concerns, evaluating maternity benefits when comparing policies is recommended, as reported by Mint. Maternity coverage typically comes with waiting periods, so purchasing only when planning pregnancy may not provide immediate access to benefits. Plans offering support for women's health needs at different life stages should be evaluated against likely needs rather than treated as essential features in every plan.
Health insurance plans may offer preventive health check-ups, teleconsultations, nutrition guidance, fitness programs, mental wellness support, and access to health coaches, according to Mint. These features may be useful if they align with healthcare needs and lifestyle, but buyers should verify whether they are included in base premium or require additional payment. Outpatient department (OPD) coverage can help pay for routine consultations and diagnostic tests, but the additional premium should be weighed against coverage limits and expected usage.