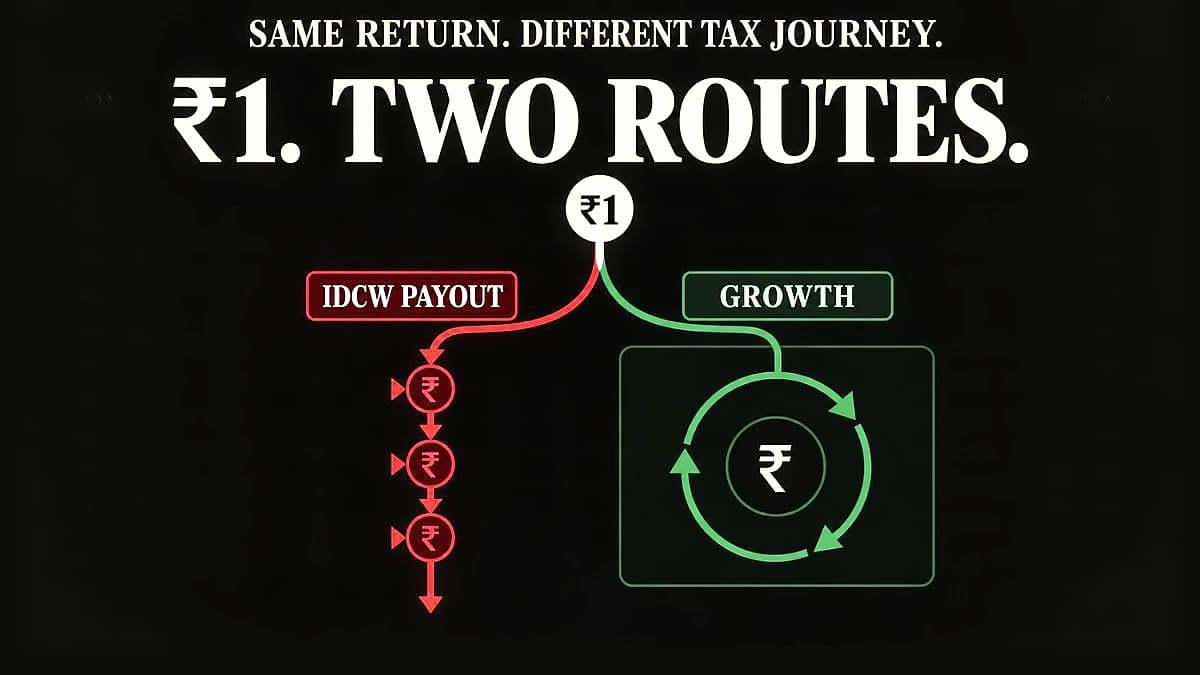
Equity mutual fund investments offer two primary options: growth and dividend (IDCW) schemes. According to MIRA Money's Rohan Goyal, growth is the superior choice for most investors as it allows profits to compound over time without interruption. Investors seeking long-term wealth creation typically prefer the growth option, as it enables the full power of compounding to work without any capital withdrawal. However, dividend schemes are suitable for investors requiring regular cash flows and disciplined spending mechanisms.
The most significant difference between options lies in Net Asset Value (NAV) performance. As reported by MIRA Money's Goyal, dividend funds distribute profits to unitholders, causing NAV to decline by the exact amount paid out. Current market data shows stark differences: HSBC Multicap Fund (Growth) NAV at ₹18.74 vs IDCW at ₹15.48, Motilal Oswal Large and Mid-Cap Fund (Growth) at ₹38.03 vs IDCW at ₹26.88, and Bank of India Flexicap (Growth) at ₹39.8 vs IDCW at ₹33 (all NAVs as of April 21, 2026). The gap continues to widen over longer periods, with IDCW options always underperforming growth options due to capital withdrawal and compounding effects.
Tax implications favor the growth option significantly. According to Avisa Wealth Creators' Aditya Agrawal, growth option investors pay tax only when redeeming units as capital gains, allowing gains to compound tax-efficiently. Short-term capital gains are taxed at 20% if redeemed within one year, while long-term capital gains are taxed at 12.5% with exemptions up to ₹1.25 lakh annually. In contrast, dividends are taxed at the investor's applicable income tax slab, making them less tax-efficient, especially for higher tax bracket investors who face 30% tax on dividend payouts. The growth option provides flexibility over redemption timing and full control over tax liability.
Young investors are highly recommended for growth options due to their longer investment horizons and ability to benefit from compounding effects. As noted by MIRA Money's Goyal, a ₹1 lakh investment growing at 12% CAGR over 25 years grows to nearly ₹17 lakh in the growth option, while the same investment under IDCW would accumulate significantly lower amounts. Dividend options are typically not ideal for younger investors who generally don't require regular income and can benefit more from compounding potential. The choice depends on whether investors need periodic cash flows or prefer long-term wealth creation without capital withdrawal.