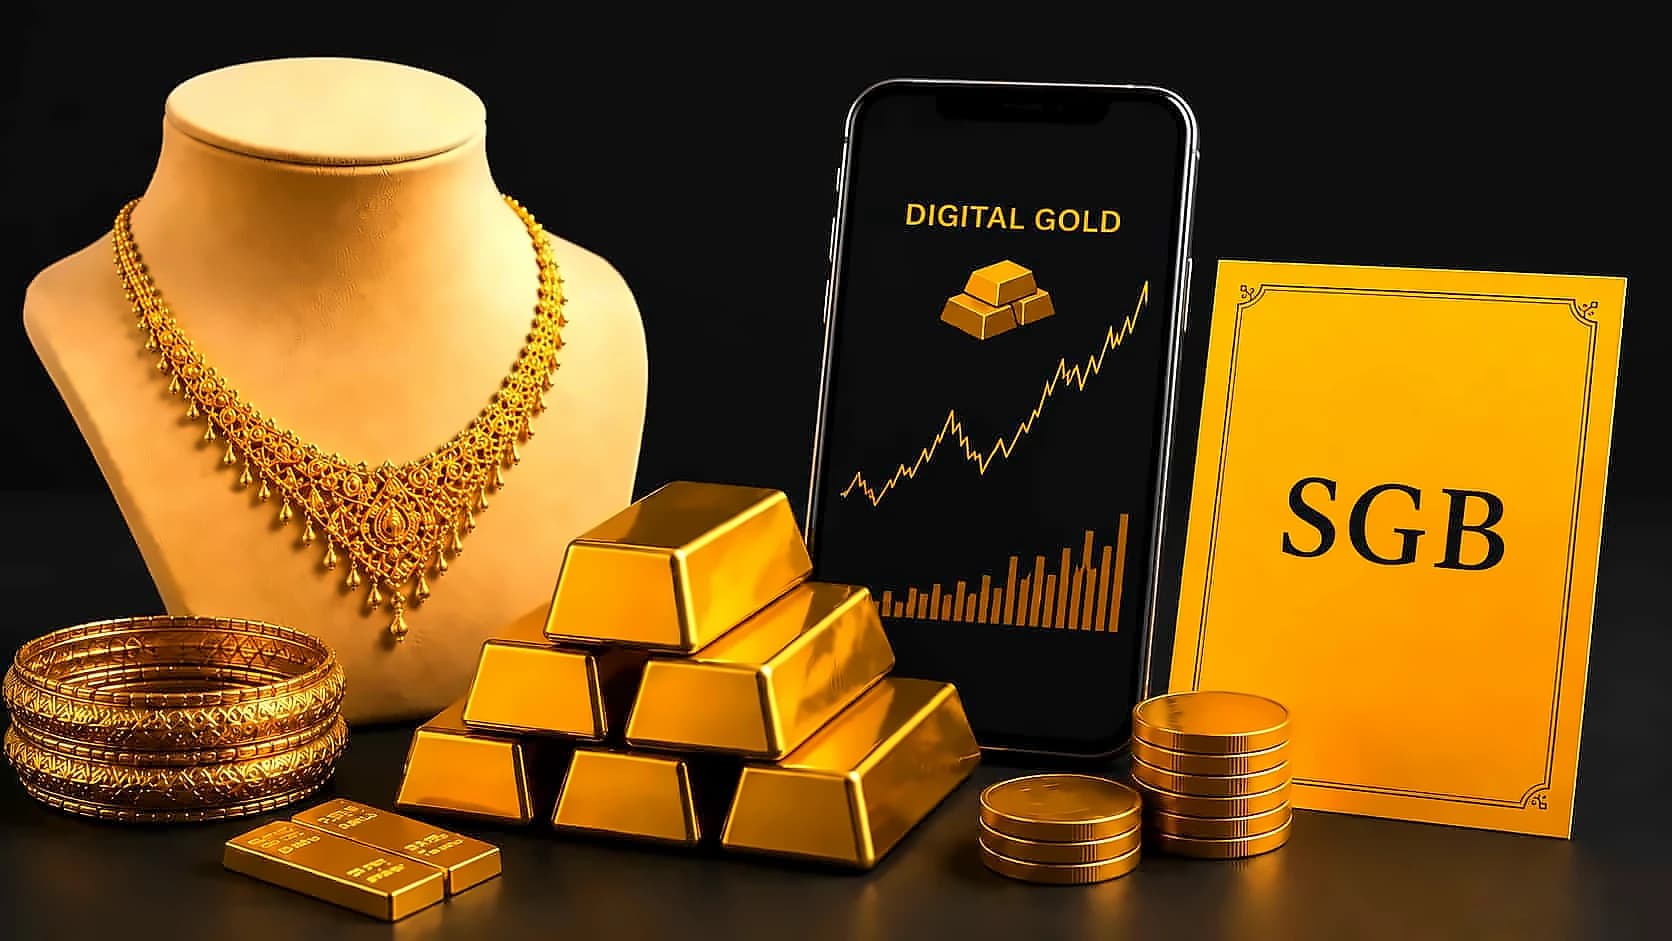
Physical gold, including jewellery, coins, and bars, is treated as a capital asset under Indian tax laws. According to reports from Mint, if sold within 24 months of purchase, any gains are classified as short-term capital gains and taxed at the individual's income tax slab rates, which differ between new and old tax regimes. For holdings exceeding two years, gains are treated as long-term capital gains and taxed at 12.5% without indexation benefit. Notably, making charges on jewellery are not separately deductible for tax purposes, and sales may require documentation to establish acquisition costs. The indexation benefit no longer exists for calculating capital gains, with all long-term gains now taxed at a flat 12.5% rate as per Budget 2024 changes. The initial cost of owning physical gold is approximately 10% of the gold value, making it the most expensive option among gold investment modes.
Gold ETFs are market-linked instruments traded on stock exchanges that allow investors to gain gold exposure without physical holding. As reported by Mint, these funds are taxed similar to mutual funds when redeemed, with short-term capital gains applicable for holdings under 12 months at normal income tax slab rates. For holdings exceeding 12 months, a flat 12.5% tax rate applies. Investors require a demat account to buy and sell ETFs, with returns depending entirely on gold price movements. The cost efficiency of Gold ETFs makes them attractive, with investment costs ranging between ₹50 to ₹100 depending on unit prices, compared to physical gold's initial cost of approximately ₹6,000 for a 1 gram gold coin. However, Gold ETFs do not provide the additional 2.5% annual interest that Sovereign Gold Bonds offer.
Digital gold platforms like PhonePe, Paytm, and Jupiter enable online gold purchases in small denominations without requiring a demat account. According to Mint reports, digital gold is backed by physical reserves held by providers, with investors able to sell digitally or convert to physical form. However, government bodies such as RBI or SEBI have no regulatory authority over this investment type, creating significant risks for investors. The Indian digital gold market is currently controlled by just three major players—Augmont Gold, MMTC-PAMP India, and SafeGold, thereby amplifying overall investment risk. Digital gold operates without regulatory supervision from entities like the Securities and Exchange Board of India (SEBI) or the Reserve Bank of India (RBI). The taxation follows standard gold investment rules, with short-term capital gains applying to holdings under 24 months at applicable income tax slab rates, and long-term capital gains taxed at 12.5% for holdings exceeding 24 months with applicable cess.
Sovereign gold bonds (SGBs) issued by the RBI offer unique tax advantages among gold investment options. As reported by Mint, these fixed-income instruments provide 2.5% annual interest paid semi-annually, with an eight-year maturity period and exit option after five years. The capital gains tax on redemption is exempt from tax for investors holding units till maturity, according to the RBI. However, Budget 2026 restricted this exemption to SGBs bought through original RBI issues and held till maturity. Any premature redemption, even by original subscribers, will be taxed as capital gains at 12.5% for long-term gains and applicable slab rates for short-term gains. The minimum investment requirement for SGBs is approximately ₹5,000, equivalent to 1 gram of gold, with a maximum investment limit of 4 kg. If held for at least five years, redemptions are tax-free, and upon maturity after eight years, the redemption proceeds are also exempt from taxation.
The taxation differences across gold investment modes in India provide investors with multiple options based on their risk tolerance and liquidity needs. Physical gold remains popular during festive seasons like Dhanteras and Akshaya Tritiya, while ETFs offer market-linked exposure without physical storage requirements. Digital gold provides accessibility through online platforms, though regulatory oversight is limited. SGBs combine gold exposure with fixed income through RBI backing, though they require longer holding periods for optimal tax benefits. For investors seeking exposure to gold with a shorter investment horizon (up to three years), gold mutual funds and gold ETFs offer better liquidity and cost efficiency compared to physical gold. Gold investment should not exceed 10% of the total portfolio for risk-averse investors, as gold primarily serves as a hedge against inflation and market volatility rather than a primary growth driver. The varying tax structures across these investment modes allow investors to align their gold investments with their specific financial objectives and risk management strategies.