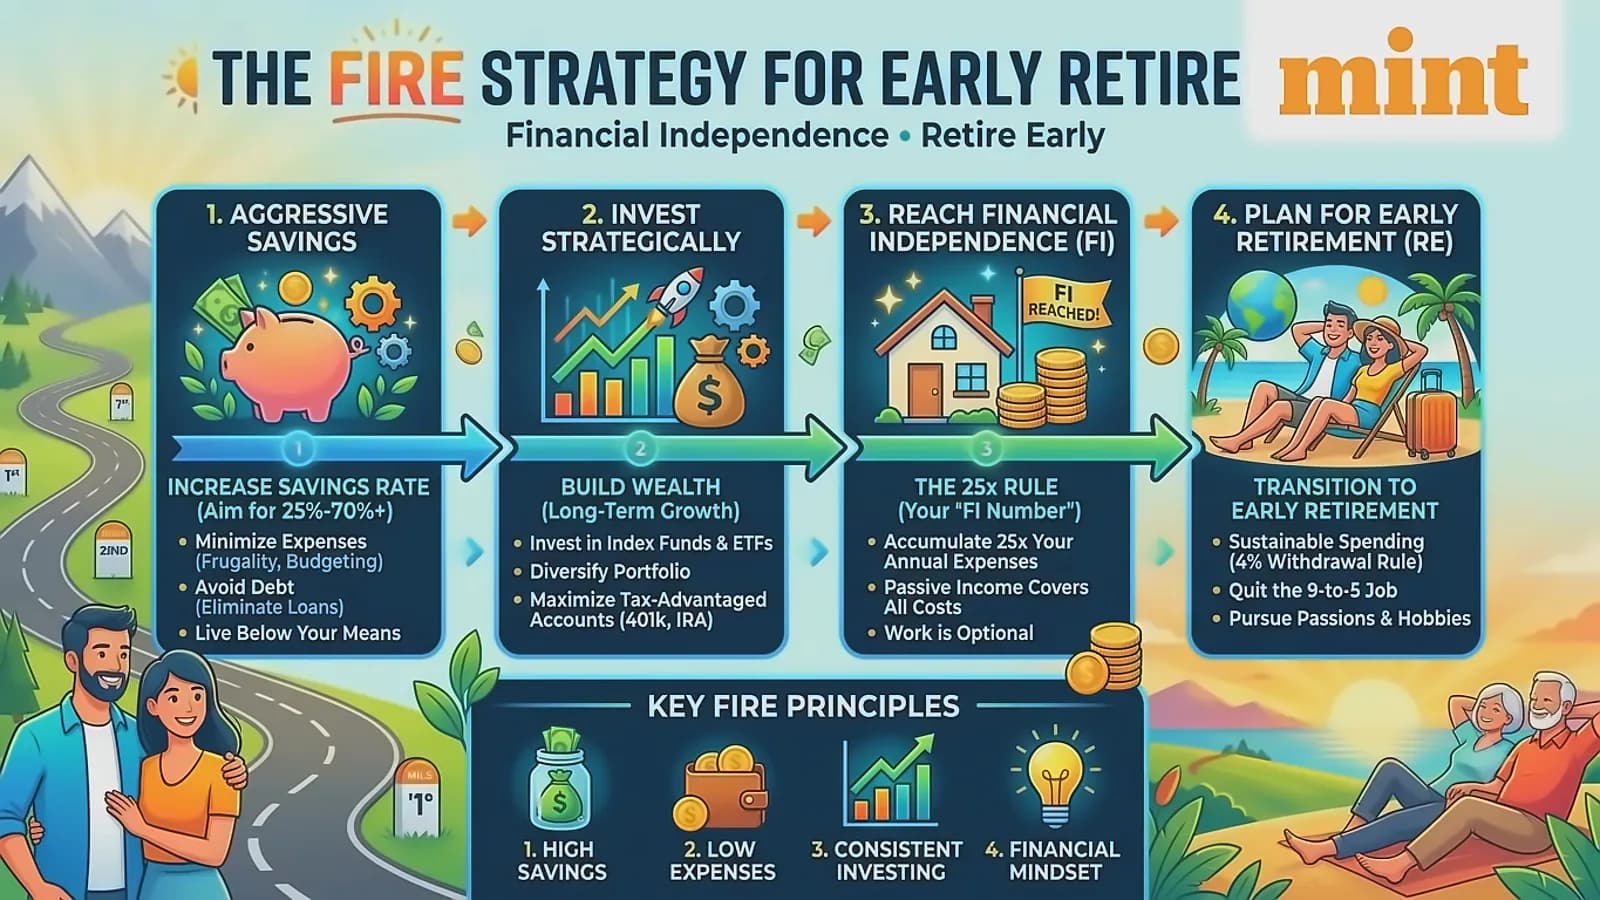
The desire for early retirement among Indian professionals has reached significant levels, with 7 in 10 urban Indians expressing willingness to exit the workforce early if financial constraints were removed, according to the recent Bharosa Talks: India Retirement Index Study 6.0 (IRIS 6.0). However, as reported by Mint, only 11% of those surveyed were confident their retirement savings would provide lifetime financial security. This gap between aspiration and preparedness highlights the growing need for structured financial planning approaches like the Financial Independence, Retire Early (FIRE) method.
The core FIRE strategy involves multiplying current annual expenses by 25 to determine the required corpus for retirement. For practical implementation, consider a professional with ₹75,000 monthly expenses compounding at 6% inflation. With this scenario, future annual living expenses at age 45 will reach ₹21.57 lakh. Applying the 4% Safe Withdrawal Rate (SWR), the target FIRE Number becomes ₹5.39 crore (₹5,39,22,600). For higher expense levels, the requirements scale significantly: ₹1 lakh monthly expenses require ₹2.5 crore corpus, ₹1.5 lakh expenses need ₹3.75 crore corpus, and ₹2 lakh expenses necessitate ₹5 crore corpus for the same 45-year retirement period.
The Coast FIRE milestone represents a critical threshold where investments cross a specific amount, eliminating the need for additional contributions to achieve retirement. In the example scenario, the Coast FIRE milestone is ₹0.99 crore, requiring a monthly SIP of ₹74,324 in equity index mutual funds at 12% CAGR to reach the target FIRE corpus. With an existing portfolio of ₹30 lakh, this SIP strategy can help professionals achieve early retirement by age 45. The approach provides ₹1.20 lakh per month in inflation-adjusted passive income, requiring investment over 15 years until age 45.
The FIRE method requires high savings rates, consistent long-term investing, and disciplined spending while accounting for factors like inflation, healthcare costs, and taxes. The strategy allows for personalization through various investment vehicles including bank fixed deposits, equity investments, SIPs, mutual funds, and government savings schemes. The approach emphasizes that no rigid 'one size fits all' solution exists, requiring individuals to mix, match, and personalize their investment strategies based on their specific financial needs and goals. With proper planning and execution, the FIRE method can help working professionals achieve early retirement by age 45 while maintaining financial security throughout their post-retirement years.