According to a comprehensive survey by debt resolution platform Expert Panel, 60% of borrowers have EMIs that either exceed or nearly equal their total monthly family income, while 40% use new loans or credit cards to manage existing EMIs. This alarming data reveals that festive-season borrowing can add to existing debt stress rather than providing financial relief. The survey found that borrowing is often linked to essential expenses rather than discretionary spending, with medical emergencies accounting for 26% of loan-taking cases - the most frequently cited reason. Additional borrowing for family expenses (22%), business requirements (18%), and household needs (15%) demonstrate how borrowing serves multiple purposes for many households.
Debt-to-income ratio (DTI) is an important measure lenders consider when assessing loan applications, comparing monthly debt payments with gross income to indicate a borrower's existing debt burden. According to Mint, the formula is DTI = (Total monthly debt payments ÷ Gross monthly income) × 100. For example, if someone earns ₹80,000 per month and pays ₹18,000 towards a home loan, ₹8,000 towards a car loan, and ₹4,000 as credit card minimum payment, their total monthly debt obligation would be ₹30,000, resulting in a DTI of 37.5%. Many lending institutions generally prefer a DTI of 40-43%, though this threshold can vary based on loan type and borrower profile. The Expert Panel data shows that job loss or salary reduction accounts for 31% of cases where borrowers cannot repay, highlighting the risks of adding new debt obligations.
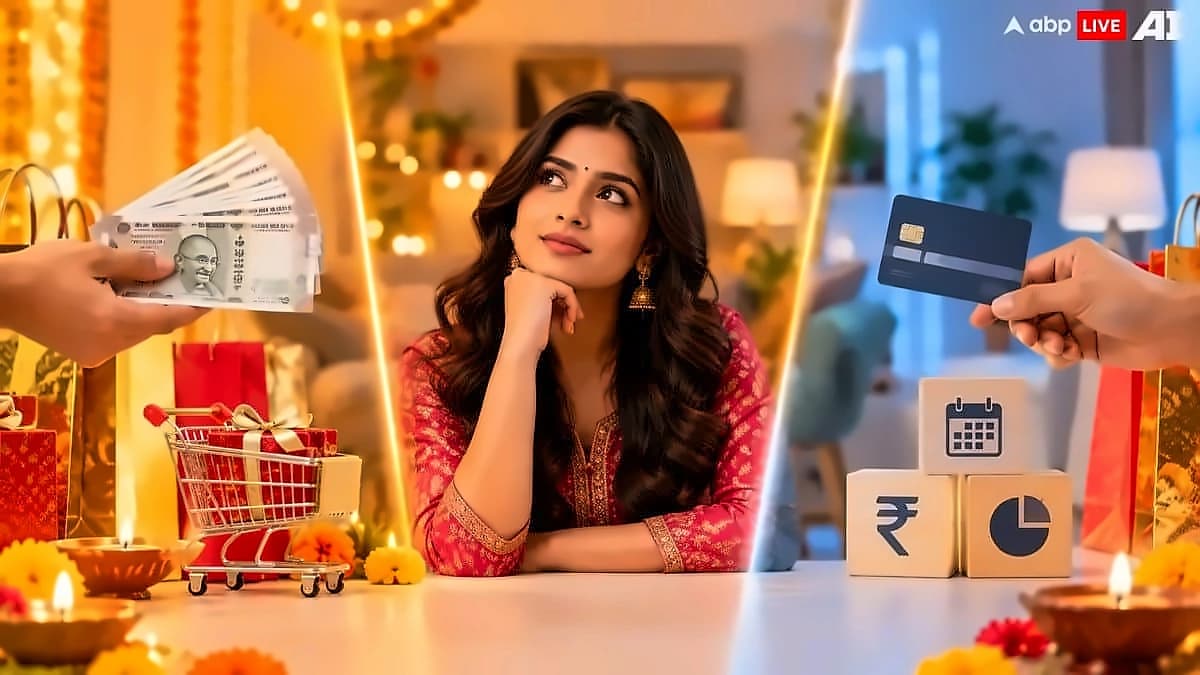
The festive season brings a flurry of planned purchases including home renovations, electronics, gifts, and family travel. According to reports from BankBazaar.com, the primary financial question arises: should you pay for these expenses upfront with cash, or spread the costs over time? Each approach has distinct advantages regarding immediate aspirations and long-term financial stability. Paying upfront with cash ensures you buy only what you can afford today, leaving you free of future monthly liabilities and interest charges. However, relying solely on cash can heavily deplete your bank balance, potentially drawing from emergency funds or regular savings.
As reported by BankBazaar.com, paying upfront with cash is a traditional method that ensures immediate affordability. However, if your festive shopping draws from your emergency fund or regular savings, you may find yourself financially vulnerable after the celebrations end. A robust cash cushion is essential for handling unexpected medical costs or sudden household emergencies. Therefore, before choosing to pay upfront, calculate how much liquid cash you will have left for emergencies to ensure financial security. The Expert Panel survey highlights that 35% of borrowers are facing some form of harassment, while 17% report severe harassment involving threats, abusive calls, or home visits, demonstrating the real-world consequences of financial stress.
As reported by BankBazaar.com, spreading costs requires disciplined planning and careful evaluation of existing financial obligations. Before taking on new monthly commitments, calculate your debt-to-income ratio by comparing your current EMI commitments against your monthly net income. It is generally recommended to keep your total EMIs well below 40% of your take-home pay. According to Mint, borrowers can improve their DTI by paying down existing debt, avoiding new borrowing, increasing income, and checking credit reports for accuracy. The key is finding a balance that suits your unique financial situation while keeping long-term financial health in mind. The Expert Panel survey emphasizes that 20% of borrowers have received legal notices from lenders, while 39% report recovery calls or abusive language, demonstrating the escalating pressure when borrowers struggle to repay.
The Expert Panel survey highlights four critical factors borrowers should evaluate before additional credit: calculate total existing EMIs, consider credit-card dues, personal loans, and BNPL obligations, understand complete repayment costs, and check whether your income can absorb additional EMI if unexpected expenses arise. Anurag Mehra from Expert Panel emphasizes that "Festive spending is often driven by emotion, social expectations and the desire to make the occasion special, but a loan converts that one-time expense into a recurring financial commitment." The data shows that 20% of borrowers have received legal notices from lenders, while 39% report recovery calls or abusive language, demonstrating the escalating pressure when borrowers struggle to repay. With 60% of borrowers already having EMIs that match or exceed their family income, the festive season may be a good time for consumers to pause before adding another EMI to their household budget.