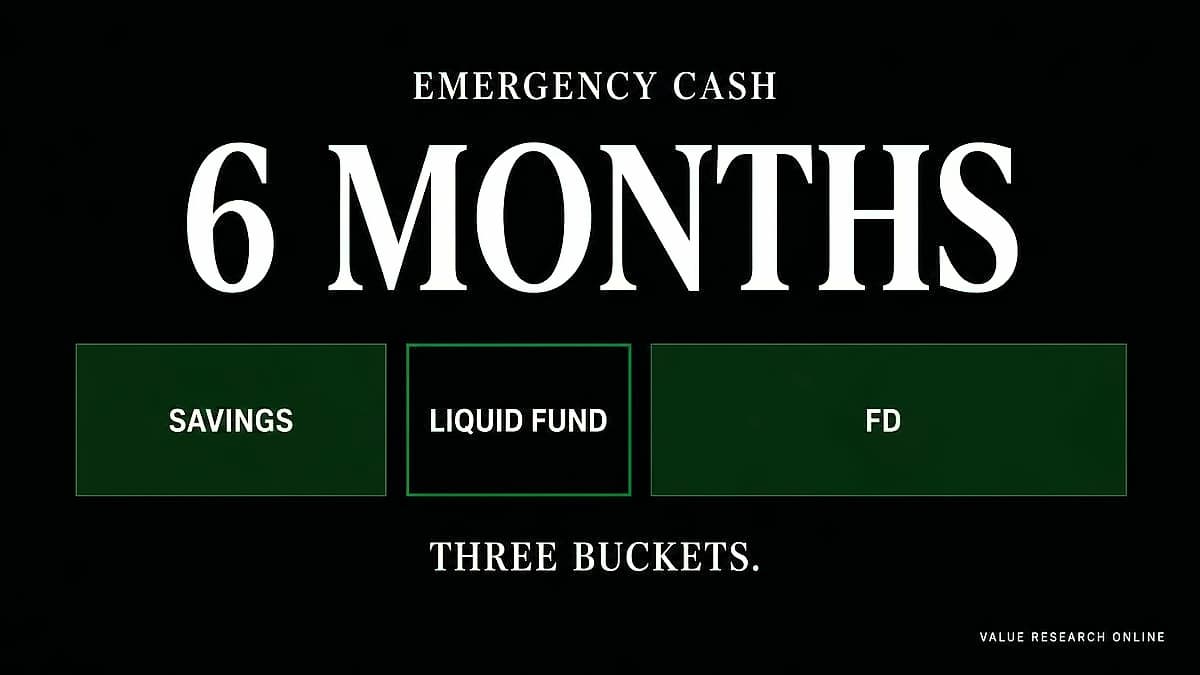
The traditional emergency fund rule of saving 3-6 months' expenses faces challenges in 2026 amid artificial intelligence concerns and job market disruptions. According to reports from Mint, this textbook recommendation may no longer be sufficient for modern financial planning. The guidance comes as companies like Oracle have recently fired 30,000 employees with immediate effect, including approximately 12,000 employees from India who were laid off over a 6 AM email. This demonstrates the rapid pace of workforce changes and the need for more comprehensive emergency planning.
Financial experts recommend a more individualized approach to emergency fund planning rather than following fixed rules. As reported by Mint, Chintan Kamdar, QPFP®, Director of Digi-Finmart Private Limited, emphasizes that the 3-6 months' expenses rule is a starting point but not a one-size-fits-all formula. The recommended calculation involves identifying essential monthly expenses including rent, EMIs, groceries, electricity, school fees, insurance premiums, and healthcare costs. Additionally, individuals should estimate realistic recovery time based on their skills, industry stability, and family dependencies.
Financial advisors suggest extended emergency fund periods for certain categories of workers facing greater income uncertainty. According to Mint reports, Kamdar recommends 9-12 months of emergency savings for workers in unstable industries, business owners, self-employed professionals, and families dependent on single income sources. The approach focuses on actual recovery time rather than arbitrary targets, with the goal of maintaining family financial stability until earnings return. This extended coverage period reflects the current job market volatility and AI-related disruptions affecting various sectors.
The location and structure of emergency funds require careful consideration beyond traditional savings accounts. As reported by Mint, Kamdar emphasizes that emergency funds should prioritize liquidity, accessibility, and capital preservation. The money should remain safe and easily accessible without depending on favorable market conditions during emergencies. Insurance serves a different purpose and cannot replace emergency savings, which cover immediate cash needs during income disruption or unexpected expenses while reducing the need to withdraw from future-focused investments.
Emergency fund planning requires regular reassessment as circumstances change over time. According to Mint reports, financial experts recommend revisiting emergency fund amounts when earnings, job security, family responsibilities, loans, or lifestyle changes occur. The approach emphasizes that emergency funds should reflect actual financial needs rather than comparisons with friends or colleagues, with the ultimate goal of maintaining family financial stability during unexpected income disruptions.