According to The Economic Times, Sahil Kapoor, Executive Director, Investment Strategist and Head of Product at DSP Mutual Fund, argues that investors should shift focus from chasing the next multibagger to building portfolios capable of surviving market crashes and extended periods of underperformance. Kapoor emphasizes that identifying tomorrow's biggest winners in advance is far more difficult than it appears in hindsight, making diversification and avoiding permanent losses more important than trying to predict extreme winners. As reported in the latest ETMarkets Smart Talk interview, Kapoor explains that buying the dip is the right cue, but it can't be applied to narrow themes and ideas - it's a broad concept that relies on staying invested over a long period with broad diversification.
As reported by The Economic Times, Kapoor highlights that 81% of historical 10-year SIPs saw negative returns at some point, while 97% temporarily underperformed debt. The mathematics of SIP wealth creation can be unrealistic when using absolute numbers, as ₹10,000 today is equivalent to only about ₹1,536 twenty years ago when adjusted for per-capita income. According to the latest interview, Kapoor warns that Excel-sheet extrapolation is not how life unfolds - life is fuzzy and random, and investors need to keep ample margins for the unknown. The report emphasizes that successful long-term investing can feel unsuccessful for surprisingly long periods, with 99% of the 10-year SIPs eventually beating debt, yet 81% going negative at some point.
According to The Economic Times, Kapoor explains that silver returned about 98% while the money-weighted investor return was only about 18%, with the largest monthly ETF inflow of ₹11,761 crore arriving around the price peak. As reported in the latest interview, Kapoor warns that FOMO can turn a good asset into a poor investor experience simply through timing, especially when that timing is based on recent high returns and the expectation that investors may miss out. The report suggests that buying the right asset after most returns are already gone is less about buying the wrong asset and more about poor timing based on recent high returns.
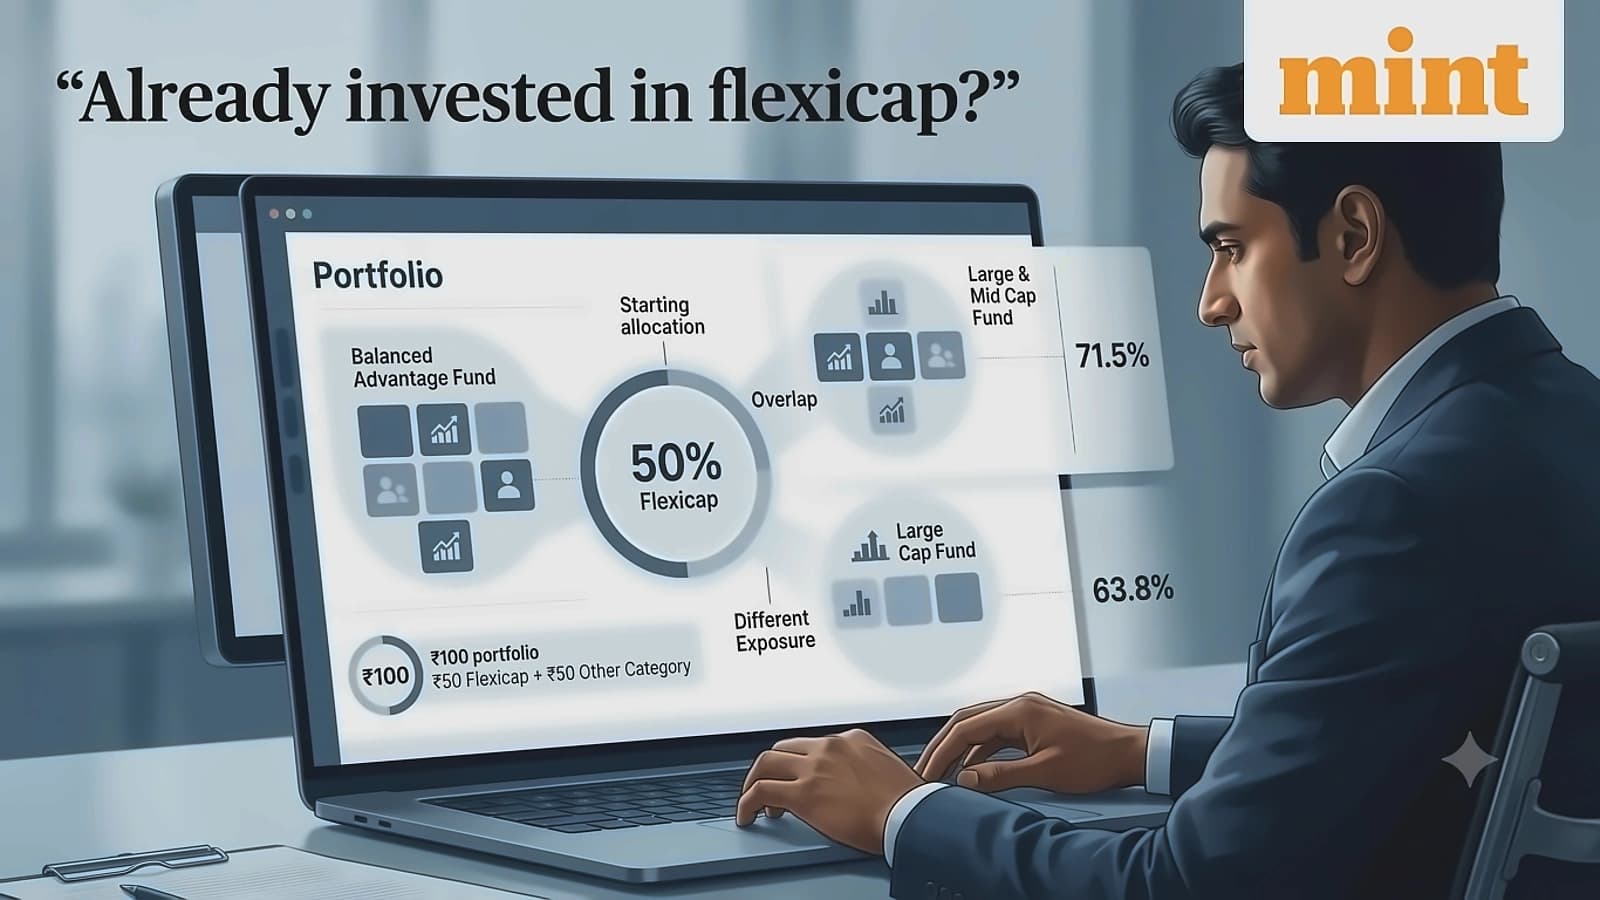
As reported by The Economic Times, Kapoor addresses the question of when diversification becomes counterproductive, explaining that adding other categories to an existing Flexi Cap portfolio leaves only roughly 25–36% different exposure in physical-equity books. According to the latest interview, Kapoor explains that when another fund adds labels rather than genuinely different exposures, it becomes mechanical. He emphasizes that diversification is an expression of the fact that investors cannot know everything and serves as an antidote to errors. The report notes that globally, just 2.39% of firms accounted for all $75.7 trillion of net wealth creation, while in India only 24.2% of stocks beat the value-weighted market.
According to The Economic Times, Kapoor warns that frequent profit-taking can be one of the biggest enemies of compounding when activity creates unnecessary taxes, costs and mistiming. As reported in the latest interview, Kapoor advises that the lesson is not 'never sell,' but do not confuse activity with value addition - repeatedly realizing gains shrinks the capital base available to compound. He advises investors to distinguish between great stories and great investments by looking for demonstrated cash flows, balance-sheet strength, returns on capital and a margin of safety. The report emphasizes that every bull market creates powerful stories, but investors should focus on evidence that economics justify prices rather than compelling narratives that require many things to go right.