College students are increasingly relying on credit cards to cover basic living expenses, with credit card use among undergraduates jumping to 54% in 2025 from 43% in 2018, according to nonprofit higher-education research firm Trellis Strategies. Nearly 9 out of every 10 students who use credit cards report doing so to pay for essentials like food, housing, and gas. Kayla Hill, a junior at Morgan State University, exemplifies this trend, accruing more than $5,000 in debt across three credit cards despite her tuition being covered by scholarships and loans. As reported by MarketWatch, she worries about her high utilisation rate potentially hurting her credit score, which she describes as "connected to quite literally everything else I would want to do," including future car loan interest rates.
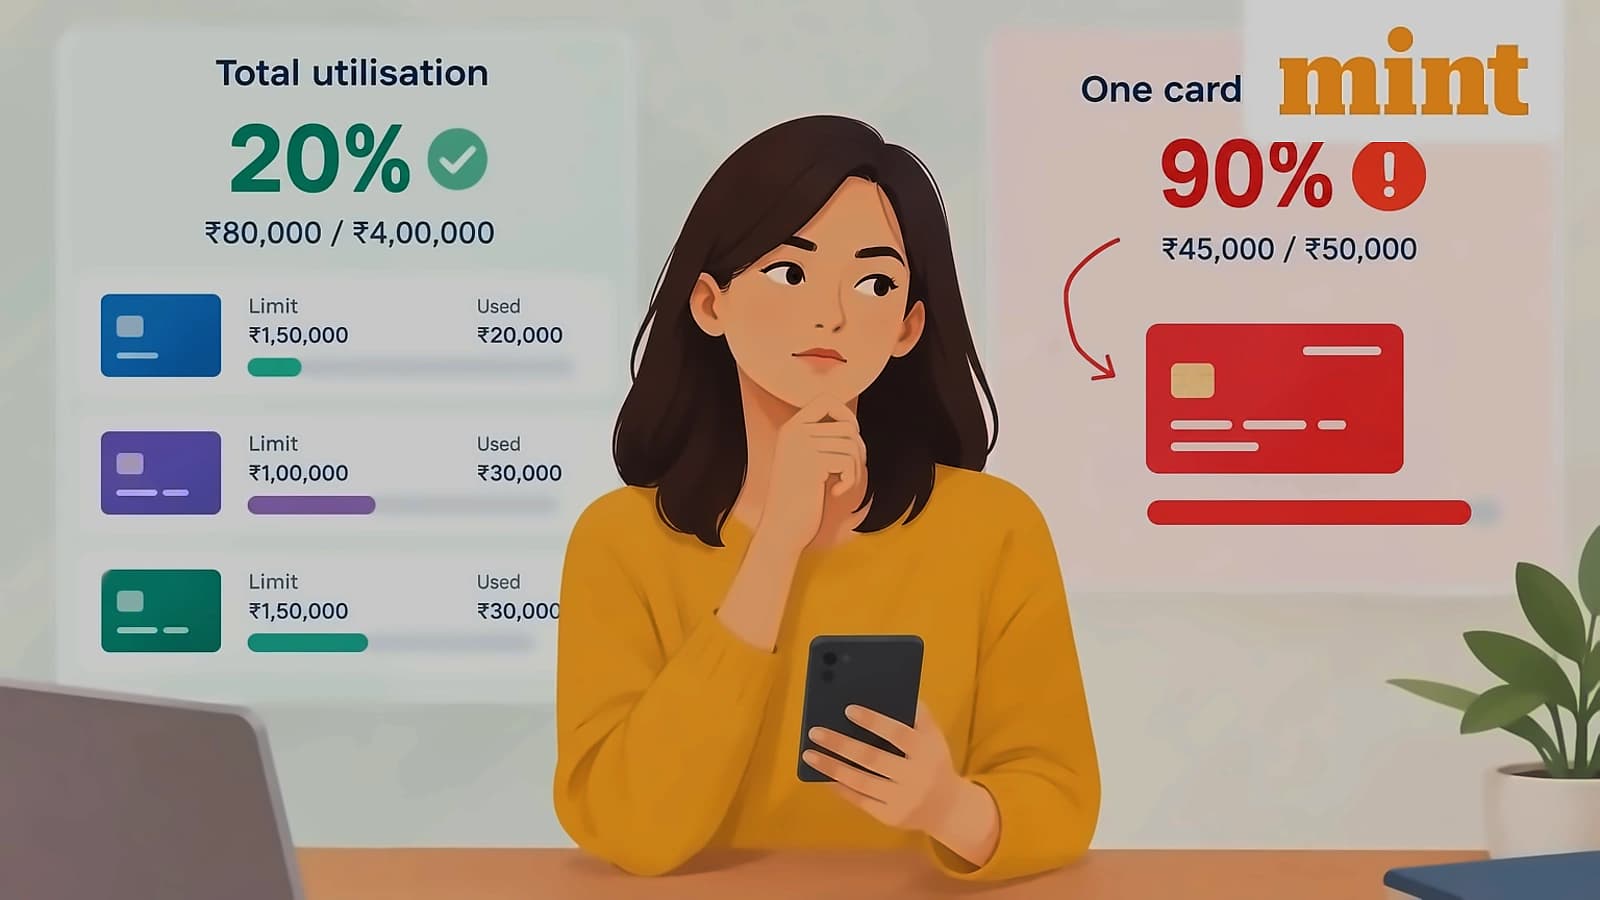
Two individuals spending ₹30,000 monthly on credit cards may experience vastly different credit score outcomes depending on their credit limits. According to reports from Mint, the difference lies in credit utilisation rates, which measure the percentage of available credit being used. When both individuals have different credit limits, their utilisation rates become the determining factor for credit score impact rather than the absolute spending amount. This becomes particularly critical for students like Hill, who must balance essential expenses against maintaining healthy credit scores for future financial needs.
Credit utilisation rate is calculated by dividing outstanding credit card balance by total available credit limit. As reported by Mint, lending institutions closely monitor this metric because consistently higher utilisation may indicate financial stress or reliance on credit for daily expenses. The metric is reflected in credit assessments by lenders and credit bureaus including TransUnion CIBIL, Experian, and CRIF High Mark. For students like Hill, this means credit card usage for necessities like $20 more for a tank of gas than at the beginning of the year, or unexpected expenses like dental procedures costing several hundred dollars.
Maintaining credit utilisation below 30% is generally recommended to preserve healthy credit scores. According to CRIF High Mark guidance, exceeding this threshold can negatively affect scores, particularly when high utilisation persists over time. The metric affects future loan accessibility, credit limits offered, and interest rates on borrowings. For students facing budget gaps between inflation and new borrowing caps, maintaining this threshold becomes crucial for long-term financial health and future creditworthiness.
Effective credit utilisation management involves multiple strategies including making multiple payments throughout the month instead of waiting for due dates, reducing unnecessary spending, and maintaining open credit accounts. As reported by CRIF High Mark, cardholders should avoid closing unused accounts as this reduces total available limit and increases utilisation ratios. The focus should be on demonstrating credible financial management rather than maximising available credit limits. For students like Hill, who are balancing essential expenses with credit score maintenance, strategic approaches become essential for managing debt accumulation while maintaining financial flexibility for future needs.