Recent market developments show improving investor sentiment with risk aversion reaching its lowest level since early 2024, according to latest market indicators. The Market Regime Indicator (MRI) has improved modestly, supported by tighter credit spreads and lower implied equity volatility. Despite ongoing geopolitical tensions and elevated energy prices, investor sentiment has remained resilient due to softer inflation readings and favorable economic data. This improved environment supports a modestly larger equity overweight allocation, with Pacific equities, US small caps, and gold gaining favor among risk-averse investors. However, as Business Standard reports, left alone, the stock market will eventually turn your carefully designed plan into something entirely different through asset allocation drift, requiring disciplined annual rebalancing to maintain target allocations.
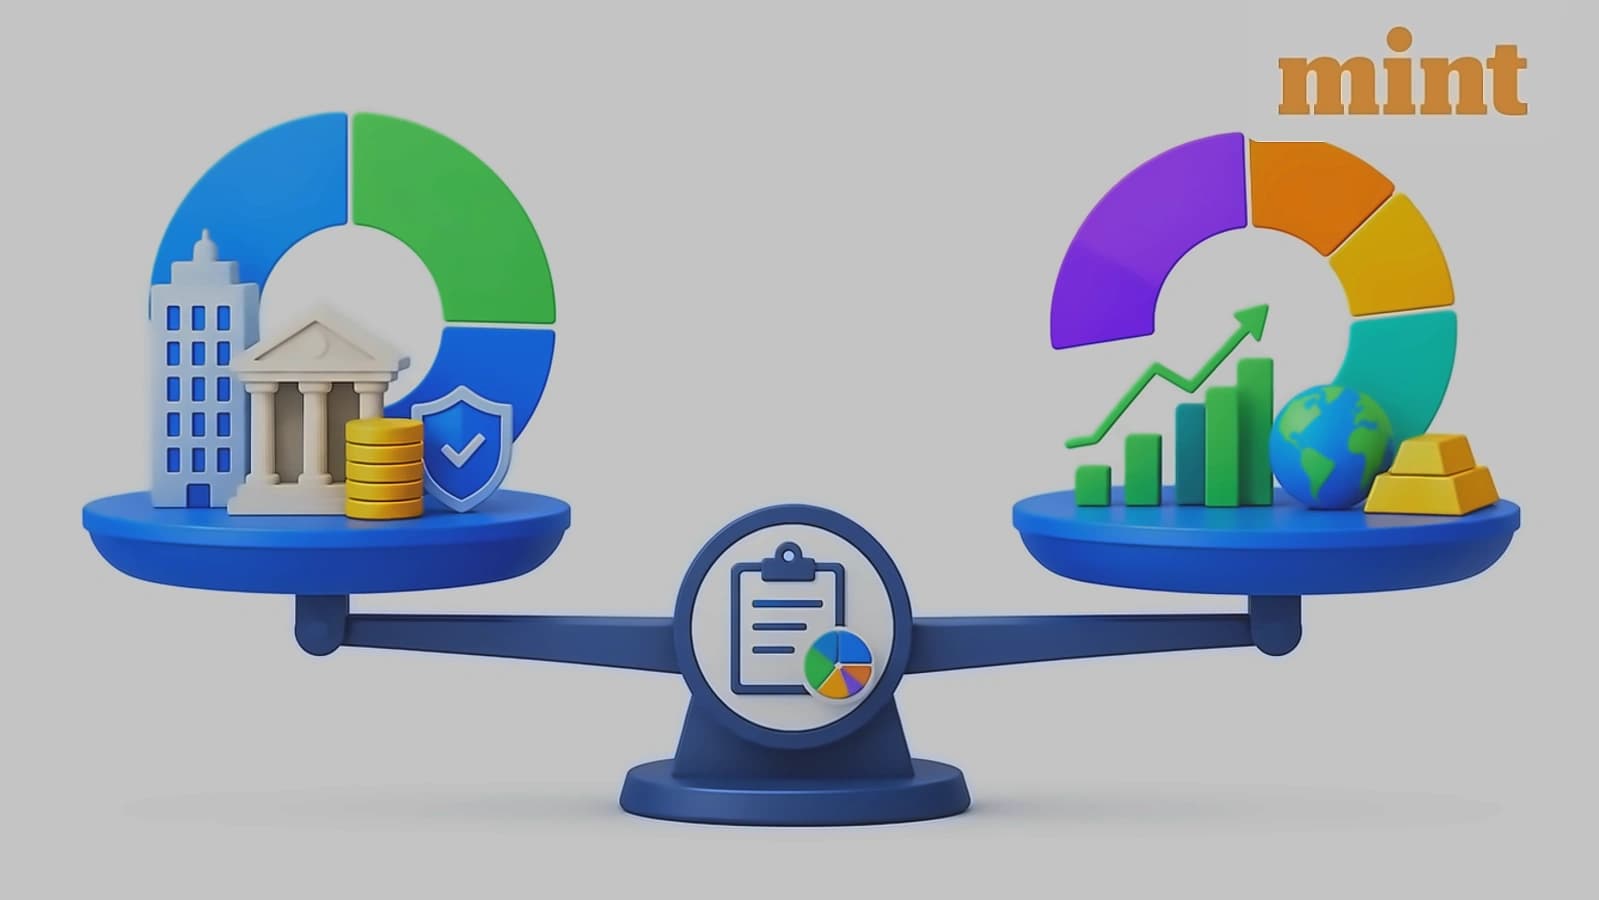
According to Business Standard, annual rebalancing helps investors correct asset-allocation drift, manage risk and restore their target portfolio mix without reacting to market noise. The foundation requires defining your target blueprint based entirely on your goal and time horizon - if retirement is 20 years away, target 75% equity and 25% debt, while for child's education in 5 years, target 30% equity and 70% debt. The core metric tracked is asset allocation drift, where even without market movements, portfolio percentages can change significantly - for example, ₹10,00,000 portfolio growing to ₹13,20,000 with equity at 68% instead of target 60% represents a dangerous drift beyond acceptable risk parameters. The 5% rule should be implemented - only rebalance if an asset class drifts by more than 5% from its target, with minor drifts of 2-3% requiring no action.
As reported by Business Standard, the portfolio structure includes a stability core of debt funds, fixed deposits, and high-quality corporate bond mutual funds that offer predictable, steady returns without crashing during market panics. The growth engine consists of large-cap index funds, specifically Nifty 50 funds that buy the 50 largest, most stable companies in the country. For investors who find managing the equity-debt mix stressful, balanced advantage funds (BAF) are available as automated solutions that shift money between equity and debt based on market conditions. Recent market analysis suggests Communication Services and Health Care remain preferred sectors, while Energy has replaced Industrials in the top tier rankings due to improving sentiment and stronger momentum. The strategy emphasizes consolidating holdings to 3-4 broad funds to make rebalancing manageable and avoiding comparison risk by accepting that the portfolio is designed for resilience, not bragging rights.
According to Business Standard, annual rebalancing should be treated as an annual chore like servicing your car, rather than a daily obsession. The process involves calculating current percentages, comparing to target blueprint, and executing fixes via cash flow (pausing equity SIPs) or selling (mathematical approach). The hardest part is psychological - selling winning equity funds feels like a mistake, buying underperforming debt funds feels like throwing money away - but rebalancing mathematically forces 'buy low and sell high' on autopilot, removing disastrous human instincts. The portfolio should be reviewed exactly once a year in April to maintain target allocations, with investors advised to uninstall stock market tracking apps and schedule annual audits instead of constant monitoring. Recent market signals show improving risk appetite with sentiment measures moving from slightly risk-off to neutral, while trend and risk-support indicators remain supportive of continued risk-taking.
As reported by Business Standard, a conservative hybrid approach for low-stress investors allocates 10% to absolute liquidity (cash/savings for emergencies), 60% to stability (PPF, Employees Provident Fund, corporate bonds), and 30% to growth (large-cap equity) to ensure the overall portfolio beats the 6% inflation rate. The strategy emphasizes ignoring 1-year trailing returns of individual funds as they hide risk taken to achieve high returns, focusing instead on whether blended portfolio return is beating personal inflation rate by 3-4%. When reviewing annually, investors should check tax implications before selling equity to verify if gains qualify for tax-free long-term capital gains allowance, and avoid reviewing more frequently than once a year as it triggers unnecessary tax liabilities and behavioral anxiety. Recent market analysis supports this approach, with economic activity remaining resilient due to stable labor market conditions, healthy corporate fundamentals, and continued business investment.