According to financial experts speaking on Zee Business, corporate bonds may appear attractive amid volatile equity markets and range-bound precious metals, offering interest rates between 6-8% that compete with traditional fixed deposits. However, Abhishek Bhasin, Head-Fixed Income at Kotak Mahindra Asset Management Company, and certified financial planner Poonam Rungta emphasize that investors must look beyond interest rates as corporate bonds contain risks that can harm investments. The experts stress that bonds can provide portfolio cushioning during volatile equity markets, making them a strategic consideration for investors seeking regular income.
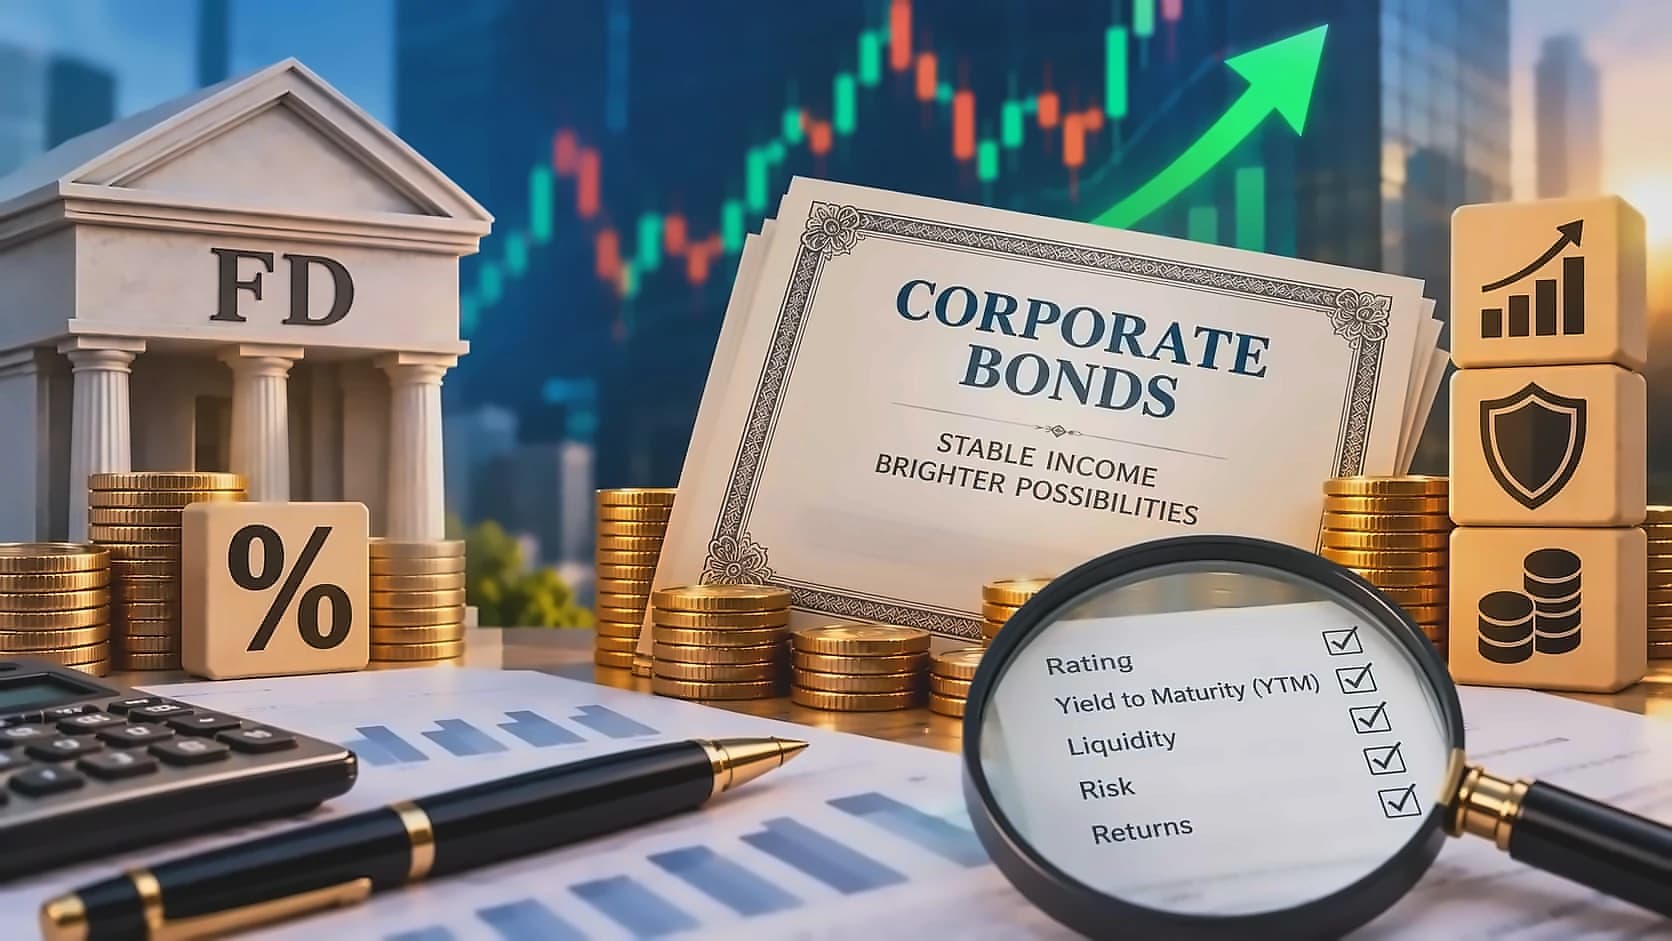
As reported by the experts, investors should prioritize credit rating and default risk over high interest rates alone. Rungta recommends focusing on secured bonds rated AA+ or higher, with different rating categories indicating varying risk levels from AAA (very low risk) to C (default status). The experts advise studying company financials, including debt-to-equity ratios and past performance, as higher returns typically correlate with higher risk. Investors should also understand liquidity risks, as corporate bonds may not trade regularly unlike shares, potentially leaving investors without buyers when they need to sell before maturity. According to recent market analysis, credit risk and interest rate are the primary risks of investing in fixed income, with bond values typically decreasing directly in response to interest rate increases. The experts note that credit risk and interest rate are the primary risks of investing in fixed income, with bond values typically decreasing directly in response to interest rate increases.
According to Bhasin's explanation, Yield to Maturity (YTM) is crucial when buying bonds in secondary markets, providing a better picture of returns if held until maturity. The coupon represents the stated interest rate, but actual returns can be lower due to premium pricing in secondary markets. Using a practical example, a ₹100 face value bond with 8% coupon would provide ₹8 annual interest, but if purchased at ₹101.50, the investor loses ₹1.50 at maturity, resulting in an effective return of approximately 7% over two years rather than the stated 8%. As noted in recent market analysis, when interest rates rise, the prices of fixed-income securities generally fall because new investments will pay a higher interest rate than existing investments, making the latter less attractive to investors. The experts explain that fixed-income investments are generally less volatile than stocks and other investments, meaning less risk of losing money in fixed-income investments.
As reported by the experts, investors should match bond maturities with specific goals using a bond ladder strategy, selecting different maturity periods for various financial needs. Rungta suggests spreading investments across multiple companies and varying maturities to create regular cash flow. The experts caution against moving money into bonds solely because equity markets are underperforming, instead recommending maintaining asset allocation based on age, financial goals, and risk appetite. For conservative investors seeking predictable cash flows, corporate bonds can form part of a diversified fixed-income portfolio, but investors must understand both returns and associated risks before investing. According to recent market guidance, conservative investors looking for a diverse portfolio are advised to purchase fixed-income assets, with the amount of portfolio allocation depending on the investor's preferred investing approach. The experts note that investors can diversify by combining stocks and fixed-income securities to produce a portfolio that may contain 50% fixed-income and 50% stocks, offering both growth potential and stability.
Bond yields have risen sharply over the past year, with India's 10-year government bond yield nearing 7%. As per Mint reports, the India 10-year government bond yield is now around 6.96%, close to the psychologically important 7% level, with Bloomberg data showing a 47 basis points increase over the last 12 months. Imran Khan from EquiRize Securities explains that the relative attractiveness of fixed income has improved meaningfully, with starting yields more attractive and global interest rates structurally higher than during the ultra-low-rate period. Against the backdrop of Nifty 50 falling 3.87% and broader market volatility, Khan suggests a reasonable allocation for moderate-risk investors: Equity: 45-60% for long-term wealth creation, FD/very short-term debt: 15-25% for liquidity, and Bonds/high-quality debt: 20-30% for income and diversification. Khan recommends a staggered deployment approach for ₹10 lakh fixed-income allocation: 30-40% now, 30-35% if yields move higher, and the balance once there is greater visibility on inflation and RBI policy.