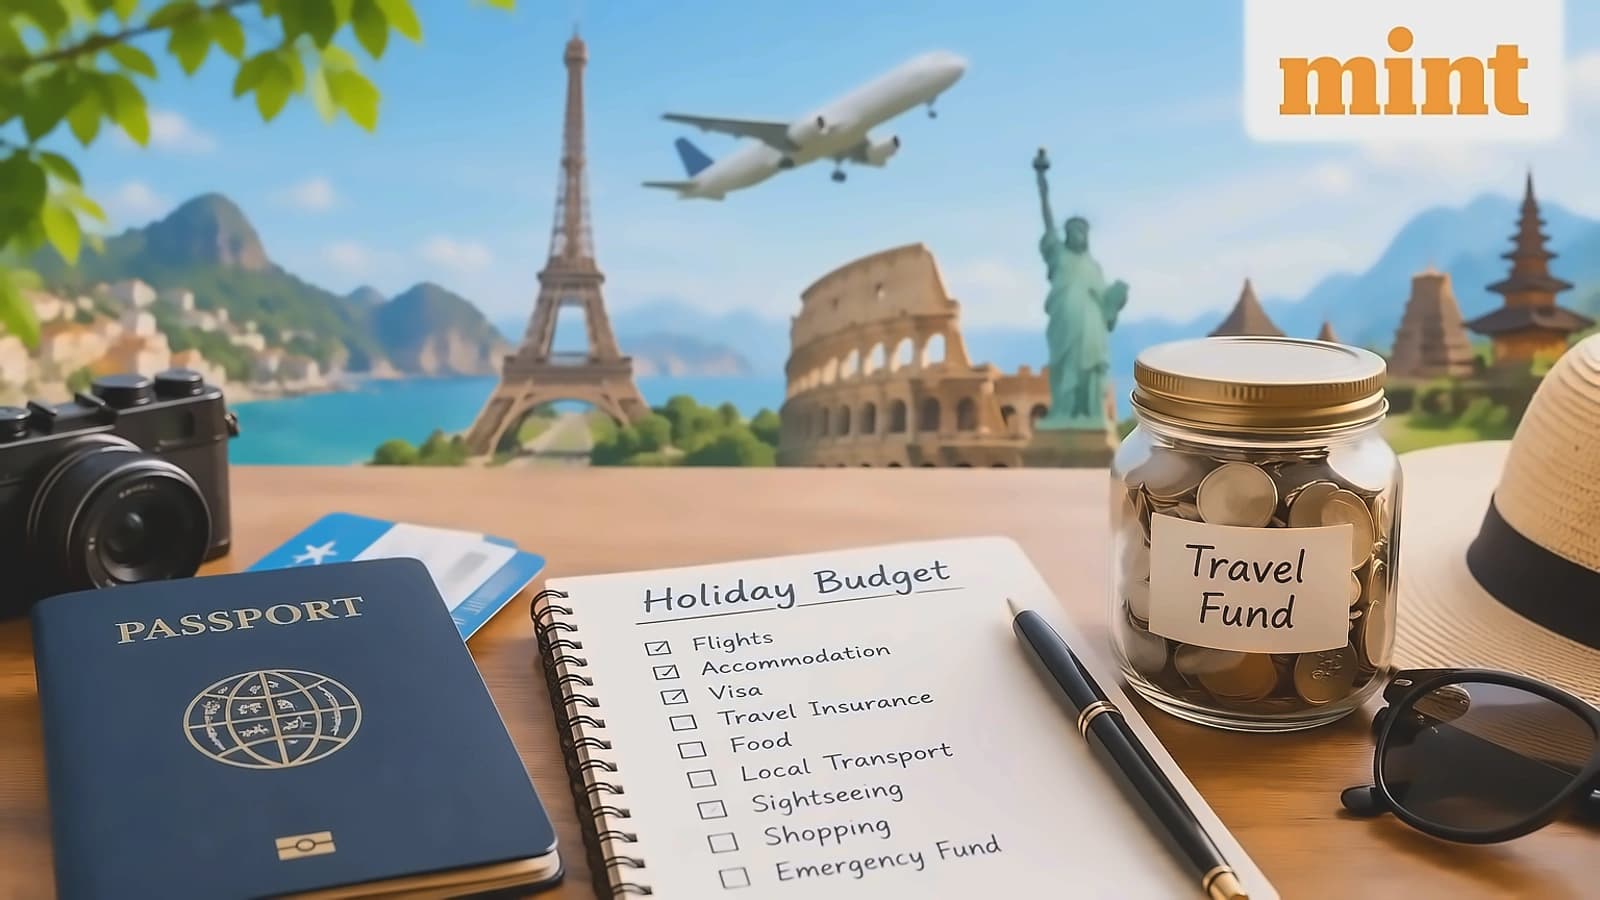
According to reports from Mint, a ₹3 lakh budget can provide considerable flexibility for a one-week international holiday, though actual costs vary significantly by destination and travel style. The recommended allocation includes ₹70,000 for flights (comparing dates and booking early), ₹45,000 for accommodation (setting nightly limits and strategic check-outs), ₹10,000 for visas (checking official fees), ₹3,000 for travel insurance (comparing medical coverage), ₹30,000 for food (fixing daily budgets), ₹20,000 for local transport (including airport transfers), ₹30,000 for sightseeing (listing paid attractions), ₹25,000 for shopping (setting spending caps), and ₹67,000 for emergency buffer (keeping untouched for miscellaneous expenses).
For event-led international travel, financial planning requires a different approach than traditional sightseeing trips. As reported by Business Standard, a ₹25,000 concert or race ticket can quickly turn into a ₹1 lakh-plus trip once flights, accommodation, visas, food, local transport and sightseeing are added. The key strategy involves separating budget into fixed and variable expenses - event tickets, visas, flights and accommodation are generally fixed costs, while food, local transport, shopping and sightseeing offer more flexibility. For example, a four-day Singapore Formula 1 trip might budget ₹35,000–₹45,000 for flights, ₹25,000–₹35,000 for accommodation, ₹20,000–₹30,000 for the F1 ticket, and ₹15,000–₹20,000 for food and transport. The race ticket typically accounts for only 20-30% of total core expenditure, emphasizing the importance of budgeting for the entire trip rather than just the event.
According to the planning methodology outlined in Mint's article, travelers can calculate monthly savings using the formula Monthly holiday savings = (Total trip budget − existing holiday savings) ÷ months until departure. For a ₹3 lakh target starting from zero savings, the monthly requirements would be ₹50,000 for 6 months, ₹25,000 for 12 months, ₹16,667 for 18 months, and ₹12,500 for 24 months. The article emphasizes keeping contingency reserves separate from regular spending and avoiding debt reliance when planning routine holiday expenses. For event-led travel, the approach should be 'build the trip backwards from your savings' - decide the total budget before buying tickets, then calculate monthly requirements rather than starting with the event cost.
For international travel, currency management requires careful planning beyond basic forex requirements. As reported by Business Standard, the approach should start with 'how much will I actually spend while I'm there' rather than 'how much foreign currency should I buy'. For a five-day trip requiring ₹4,000 daily for meals and transport, that's ₹20,000 for basic daily expenses. Adding ₹10,000-₹15,000 for sightseeing or shopping brings total on-ground spending to ₹30,000-₹35,000. The Reserve Bank of India permits resident travellers to purchase foreign currency up to $3,000 per visit for most destinations. A combination of cash and cards is more practical than relying entirely on either - carry enough cash for initial days and use zero-forex cards for balance, while maintaining a second payment option separately as backup. Avoid dynamic currency conversion at terminals and use bank-operated ATMs instead of airport counters.
Event-led travel carries unique financial risks that require additional planning. As reported by Business Standard, an emergency buffer of 10-15% of total trip budget is essential - for a ₹1.2 lakh holiday, that means keeping ₹12,000-₹18,000 accessible. This money should not be treated as shopping budget - imagine missing a connecting flight could cost ₹20,000-₹40,000 for replacement tickets and accommodation. Other unexpected expenses include lost cards, baggage delays, medical emergencies, and flight disruptions. For payment security, maintain primary card for most transactions, backup card kept separately, and ensure cash for immediate essentials. The emergency buffer should remain accessible throughout the trip, not treated as discretionary spending money.