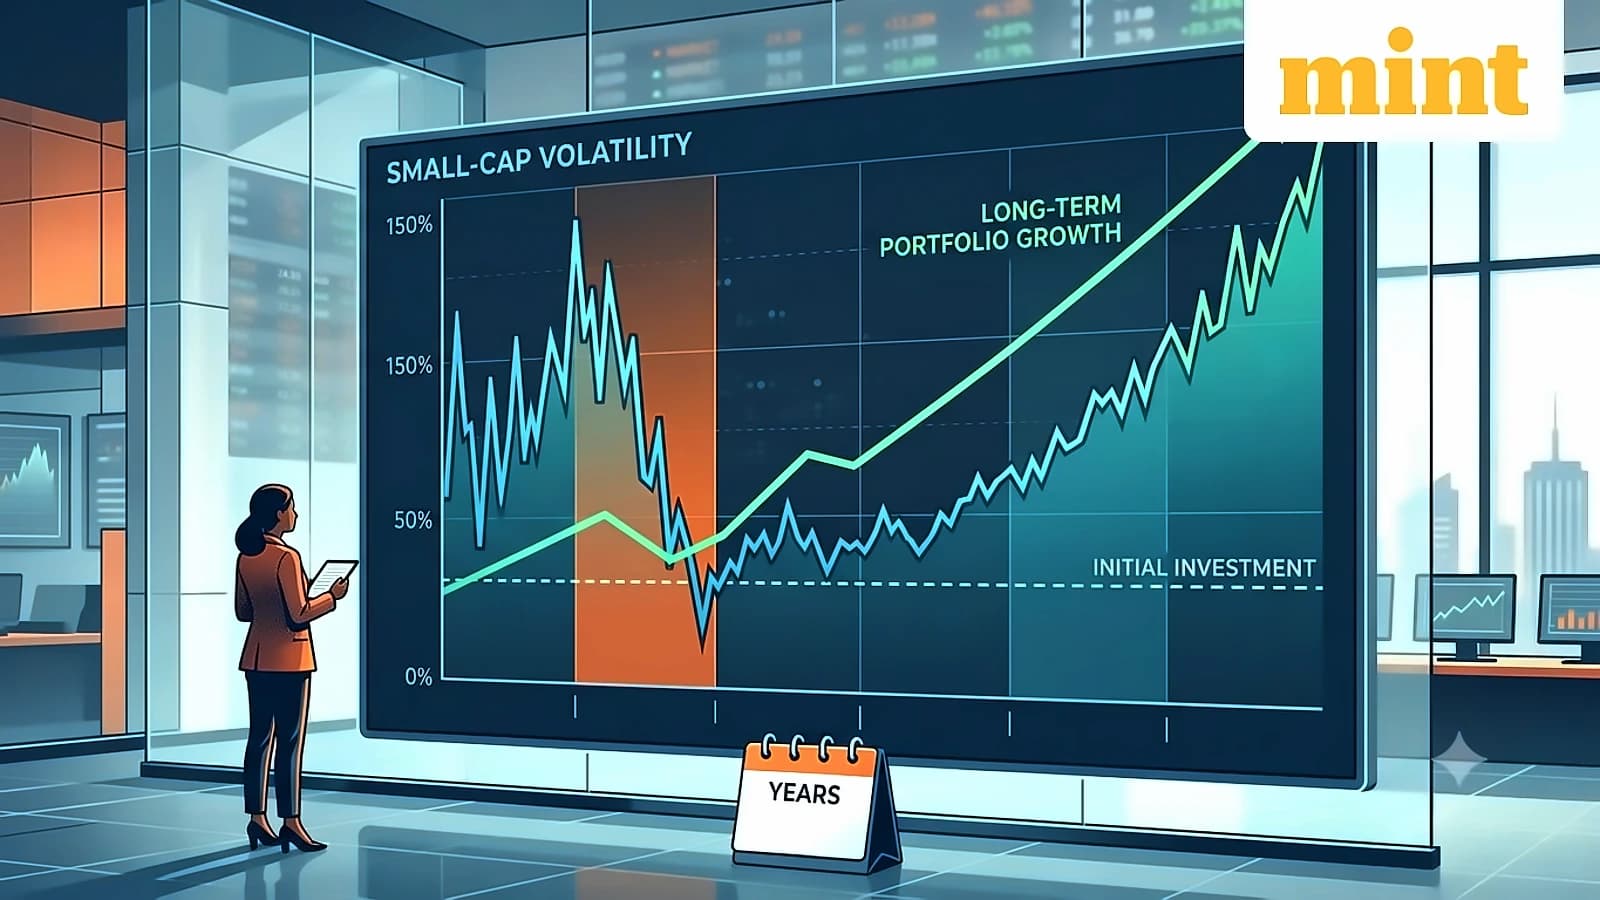
New insights reveal that systematic investment plans in the Nifty50 have consistently underperformed, delivering a mere 4.5% XIRR over the past five years. This result places Nifty50 SIPs below the returns of traditional fixed deposits, creating a stark reality for large-cap investors. The underperformance becomes more pronounced over shorter periods, with Nifty50 SIP returns being negative 4.6% over two years and negative 10.5% over one year, according to data from ACE MF. However, the weakness has not been uniform across market segments, as Nifty Midcap 150 delivered 14.89% over five years and Nifty Smallcap 250 TRI returned 15.34% over the same period. Over seven years, the two indices gained 19.22% and 20.64% respectively, highlighting the divergence between large-cap and mid/small-cap performance.
A recent DSP Mutual Fund report reveals a critical gap between fund-reported returns and actual investor returns, highlighting how timing of investments and withdrawals can create significant differences even when funds deliver strong long-term performance. The report uses the Kinetics Internet Fund example from the US internet boom to illustrate this phenomenon. Between December 1998 and December 2003, the fund generated a compounded annual return of 8.3%, while investors faced a loss of 11.9%, creating a 20.2 percentage point gap. Similarly, from December 1998 to July 2026, the fund delivered 10.4% annualised returns while investors earned only 0.4%, showing how long-term compounding existed but investor behaviour did not allow full capture.
The current five-year period for Nifty50 SIPs began after the post-Covid rally and ended during a phase of market weakness, making it an unfavourable window for measuring equity returns. According to OmniScience Capital's Vikas Gupta, from September 17, 2021 to September 17, 2024, Nifty 50 lump-sum returns stood at 14% CAGR, while monthly SIP returns were 21%. However, the subsequent two-year period has been flat for both lump-sum and SIP investors. The DSP report reinforces this by stating that "the fund was not the problem. The timing of capital was." As explained by INDmoney, a fund can disappoint while doing exactly what its mandate says, such as a value fund avoiding expensive companies during a growth-stock rally. The key is to establish whether the lag reflects a style cycle or genuine fund deterioration before reacting to the return numbers.
Despite recent underperformance, five-year rolling returns for the Nifty 50 TRI since 1999 have averaged around 15%, with only 0.07% of observations delivering negative returns. According to OmniScience Capital, such periods have typically been followed by strong returns, which help bring longer-term performance closer to historical averages. The correction has moderated some valuation excesses, making valuations relatively more reasonable in several parts of the market. As JM Financial's Ladia noted, "Going forward, near-term returns will be less about where the index goes and more about identifying businesses that can beat earnings expectations while still being reasonably priced." The analysis suggests that the next phase could be more dependent on earnings and stock selection than on a broad-based rise in the index, emphasizing the importance of fund manager skill in stock selection rather than index direction.
For a complete SIP performance review, investors should record five key items: SIP XIRR and cash-flow dates, fund returns against benchmarks, relevant category comparisons, changes in holdings and expenses, and progress toward goals. According to INDmoney, the analysis should include rolling-return behaviour to reduce dependence on single start dates and test multiple windows of equal length. Most importantly, investors must wait, review, or reconsider based on the severity of the performance gap and whether the cause is understood. As Union AMC CEO Rajkamal Tiwari noted, there is no fixed formula for how many months or years an investor should give every underperforming scheme, emphasizing the importance of longer-term consistency over short-term volatility. The DSP report reinforces this by advising investors to focus on their investment horizon and stay disciplined through market cycles rather than chasing funds after strong past performance or exiting after sharp falls.