According to recent market analysis, short duration funds and credit risk funds serve distinct investment purposes in the fixed income market. Short duration funds primarily focus on managing rate risk by maintaining shorter investment horizons to limit exposure to interest rate fluctuations. In contrast, credit risk funds concentrate on managing default risk by focusing on credit quality assessment and portfolio diversification strategies. PRSD (State Street Short Duration IG Public & Private Credit ETF) represents a differentiated approach that combines investment-grade public credit with select private credit exposures, creating a broader opportunity set for security selection and excess return generation. The value of systematic credit investing lies in translating fundamental investment ideas and experience into rules that can be applied consistently and efficiently in actual bond portfolios, differing from simple factor-based approaches that may lack precision in assessing issuer risk profiles.
The tax treatment of these fund categories varies significantly based on their investment strategies. As reported by market experts, short duration funds typically face higher taxation due to their exposure to interest rate movements and the resulting capital gains implications. Credit risk funds may offer more favorable tax treatment since they focus on credit quality rather than rate sensitivity, potentially reducing taxable income for investors. PRSD's tax efficiency is enhanced by its investment-grade orientation, with private credit typically representing only 10-35% of the portfolio, while the strategy's focus on public credit securities helps maintain lower tax exposure. Recent tax changes effective April 1, 2023 have simplified the tax structure, with gains now taxed at individual slab rates regardless of holding period, though investors who sold before July 23, 2024 may still benefit from indexation benefits.
Short duration funds generally provide better liquidity compared to credit risk funds, making them more suitable for investors requiring quick access to their investments. According to investment experts, credit risk funds may offer lower liquidity due to their focus on longer-term credit analysis and portfolio construction strategies, which can result in more restricted access to funds. PRSD maintains strong liquidity characteristics through its investment-grade focus and active management approach, with the fund designed to provide intraday, firm, executable bids on investment-grade asset-backed instruments sourced through Apollo's private credit platform. Ultra-short duration funds offer similar liquidity advantages, with investors able to redeem units anytime and receive proceeds within a day for emergency fund allocation purposes.
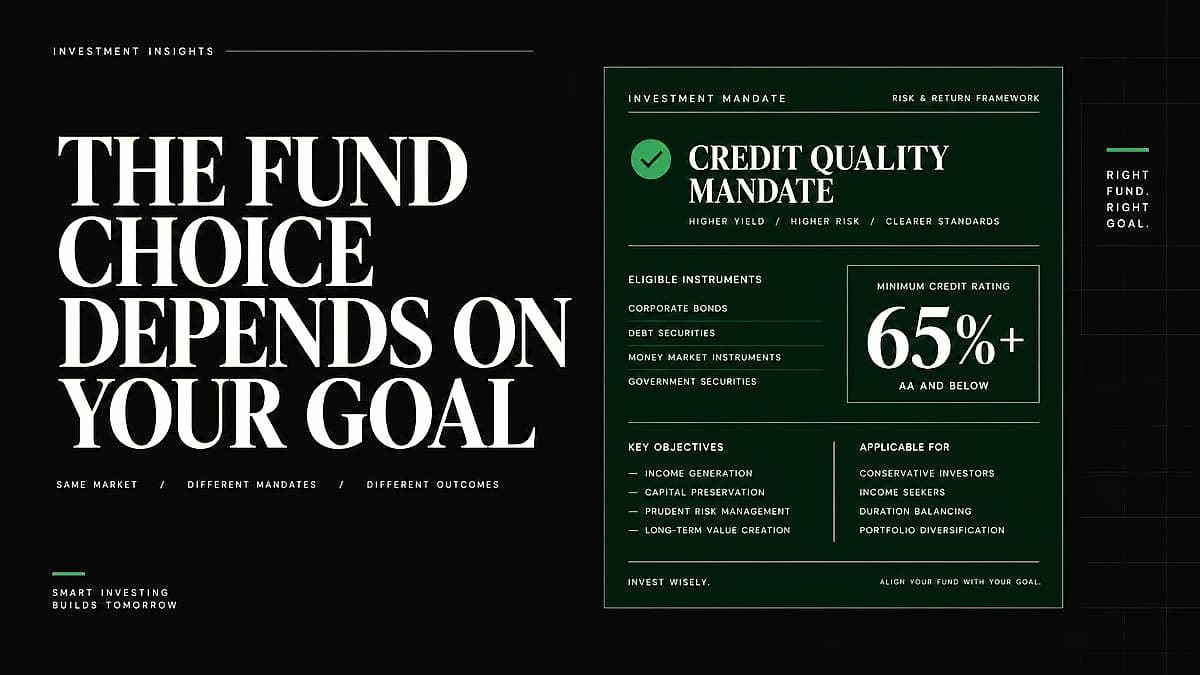
The choice between these fund categories should primarily depend on investment time horizon and risk tolerance. As reported by market analysts, short duration funds are more suitable for short-term investment horizons where interest rate movements are a primary concern. Credit risk funds are better suited for long-term investors who prioritize credit quality over interest rate sensitivity, with the investment decision ultimately driven by yield considerations taking a secondary role to taxation, liquidity, and time horizon factors. PRSD offers a middle ground approach that combines short-duration risk management with enhanced income generation potential through its diversified credit exposure strategy. Ultra-short duration funds are particularly suitable for investors with short-term goals (3-6 months), conservative investors seeking rates higher than savings accounts, and those requiring quick redemption access for emergency fund allocation.
Recent performance data demonstrates PRSD's ability to enhance portfolio efficiency when combined with traditional short-duration strategies. As shown in analysis covering the period from September 2025 to July 2026, replacing 50% of a core SPAB allocation with PRSD reduces portfolio duration by 33% while increasing yield-per-unit-of-duration from 0.85 to 1.29. The strategy's average correlation of excess returns against the largest five active short-term bond ETFs is only 0.21 compared with an average pairwise excess-return correlation of 0.60 for those top five ETFs, indicating differentiated alpha generation that reduces portfolio concentration risk. PRSD currently provides a yield advantage of approximately 26 basis points versus the Bloomberg U.S. Universal 1-5 Year Index while maintaining an investment-grade orientation, demonstrating its effectiveness in diversifying short-duration income sources. Ultra-short duration funds typically offer higher capital appreciation potential than liquid funds with limited interest rate risk, making them suitable for investors seeking better returns than traditional savings accounts while maintaining relatively safe liquidity profiles.