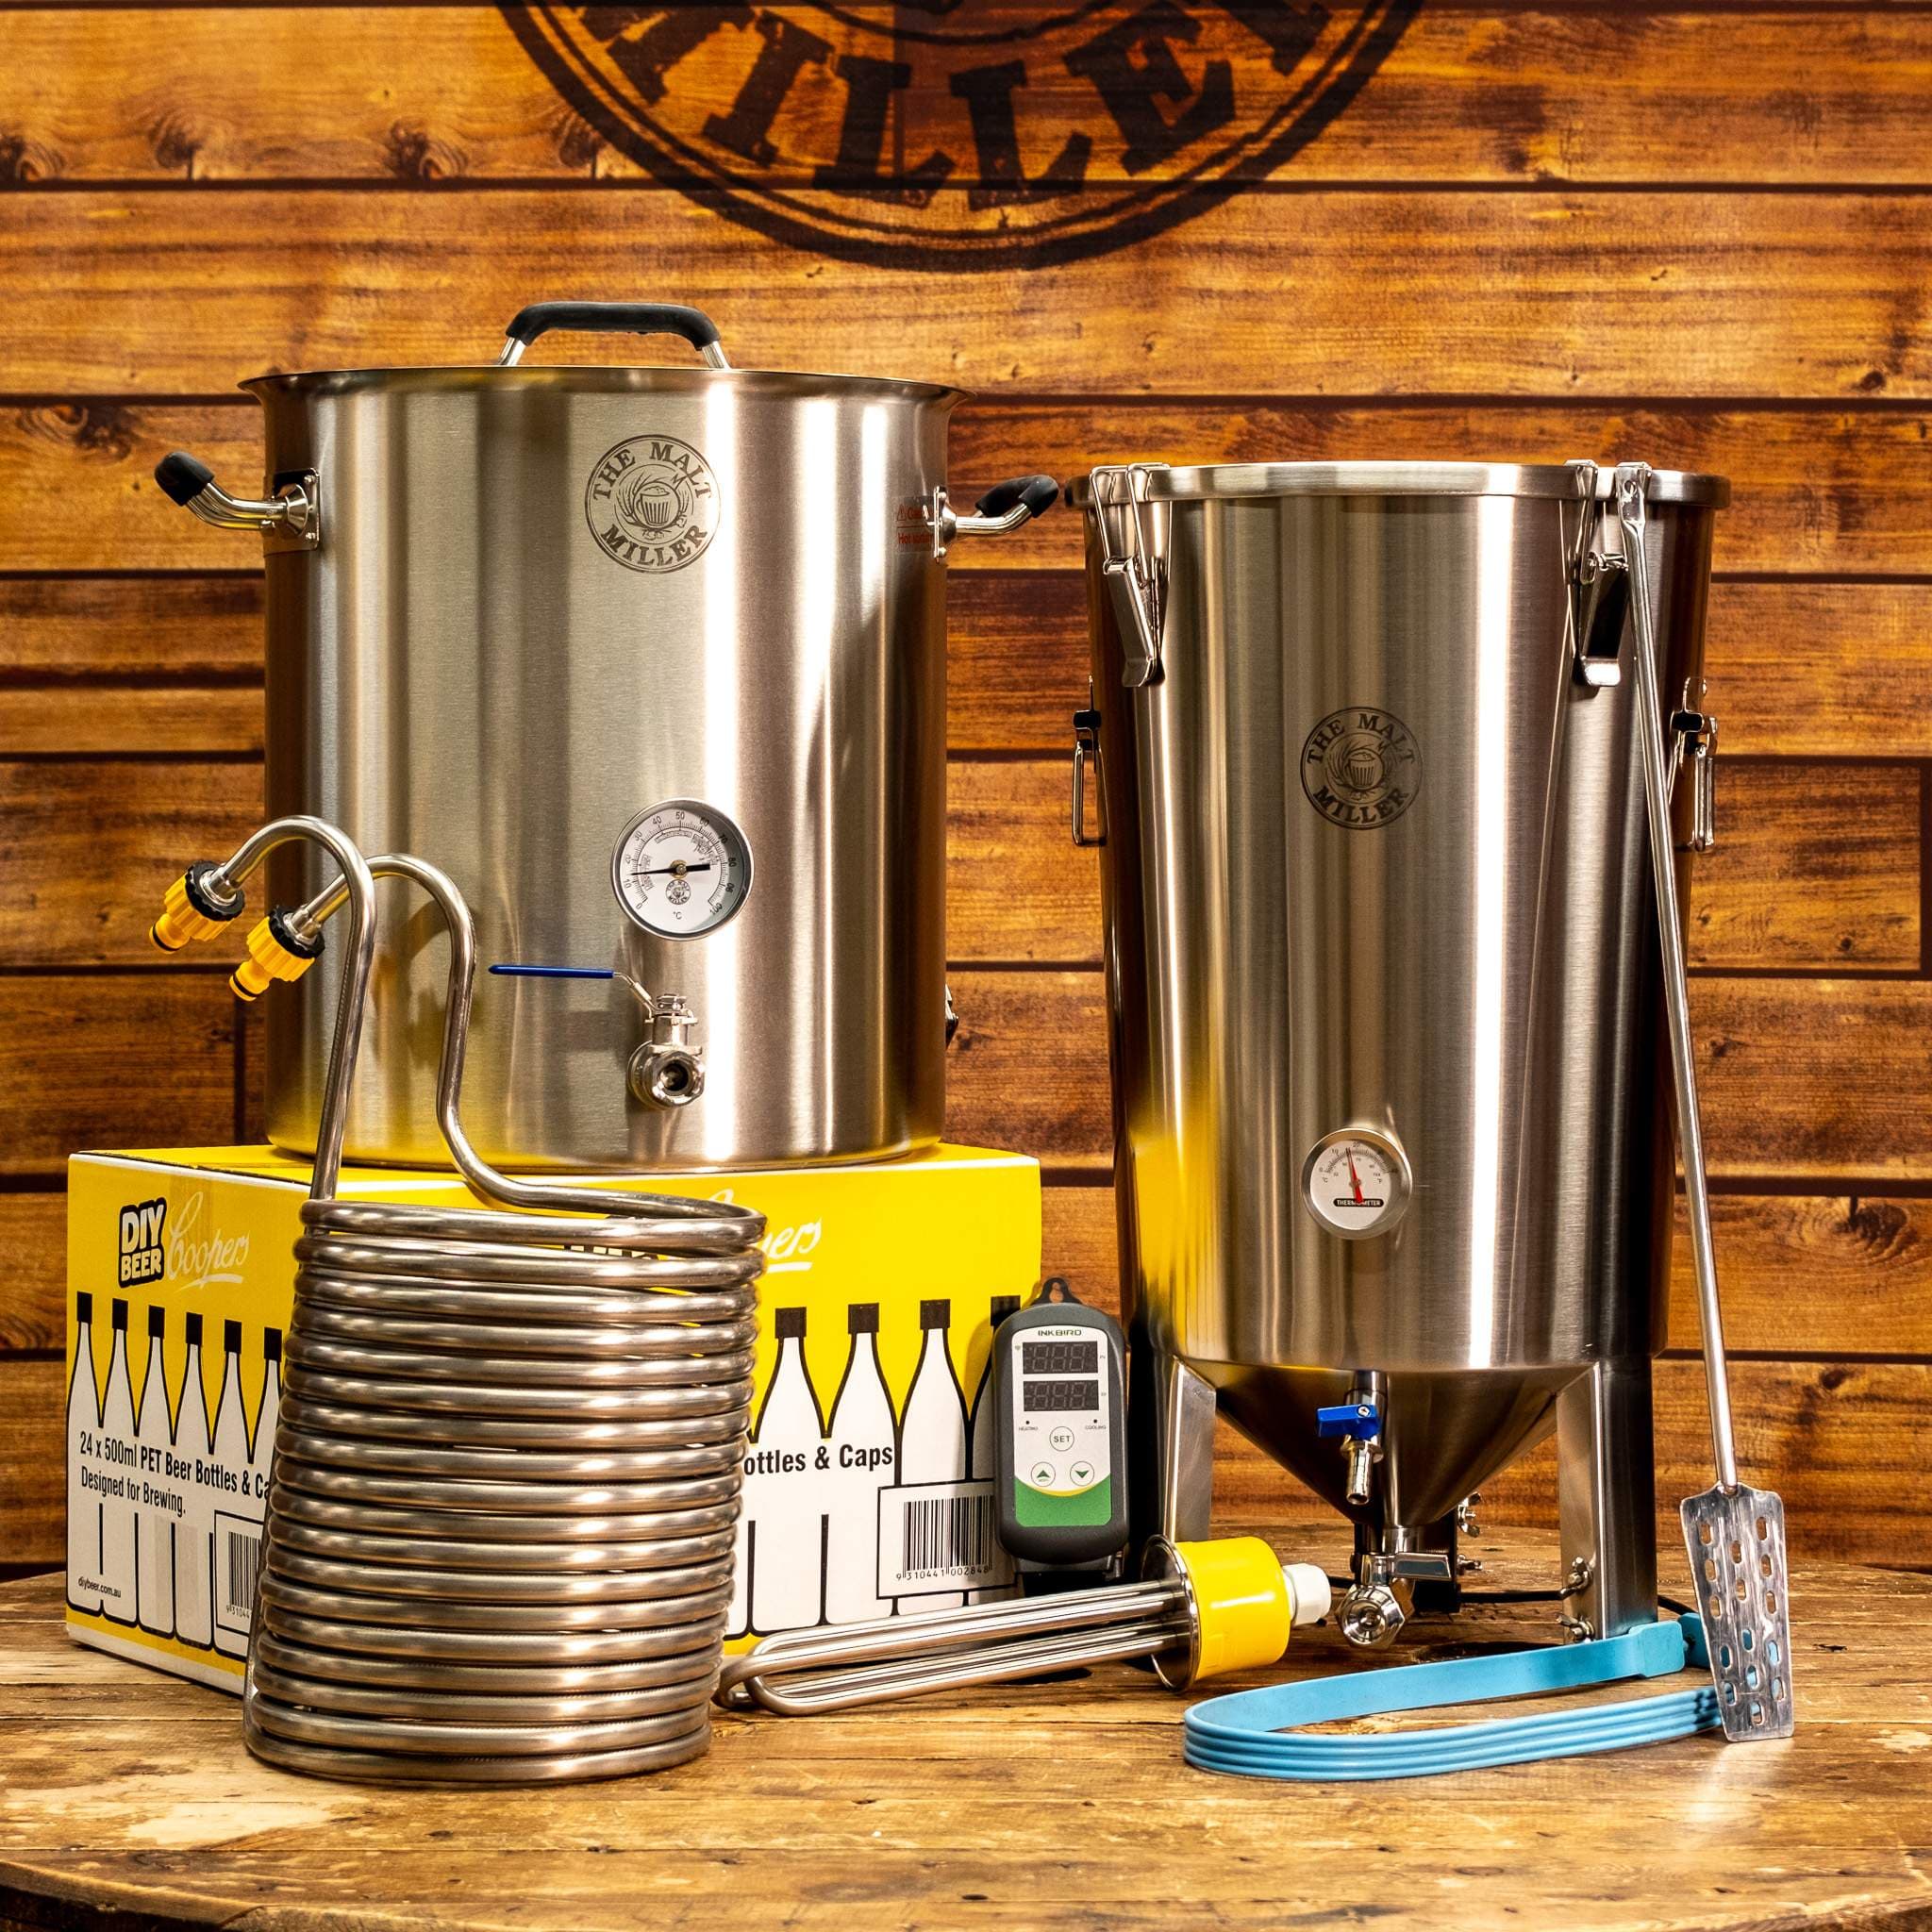
There's a quiet revolution happening in India's drinking culture. Craft beer bars are multiplying in metros, single malt whisky is no longer a niche pursuit, and premium spirits are finding shelf space in Tier-2 cities. Behind every pint poured and every dram savoured is a complex web of industrial machinery, and that's precisely where SpectraA Technology Solutions Limited operates.
The Bengaluru-based engineering OEM has opened its IPO to the public markets with ~₹43 crore SME IPO on NSE Emerge, priced at a band of ₹112–₹118 per share. The subscription window is open from September 17 to September 21, 2026.
What does SpectraA actually do?
Founded in 2009, SpectraA is not merely an equipment supplier. It is an engineering-led, turnkey project executor. The company takes complete ownership from design and fabrication to installation, commissioning, and even decommissioning of process plants across breweries, distilleries, malt spirit facilities, food & beverages, and extraction plants.
In plain terms: if a brewery wants to set up a new plant or upgrade an old one, SpectraA handles the entire job. This full-stack model: building key equipment in-house using standardized modules, gives the company better cost control and scheduling discipline than a pure-play equipment trader.
The company's commercial brewery equipment is its backbone, contributing 68.14% of FY26 revenues. But the more interesting growth story is in malt spirit equipment, which has tripled its revenue share from 3.57% in FY24 to 10.28% in FY26; riding India's single malt and premium whisky wave. The company also has an international footprint through its Singapore subsidiary, with 29.39% of FY26 revenues coming from exports.
The numbers tell a strong story
The financials are, frankly, impressive for a company of this size.
The EBITDA margin expansion from 5% to 19% in just three years is the headline number. It reflects a combination of better project mix, operating leverage, and growing contribution from higher-margin malt spirit and export projects. The RoE of 60.95% and RoCE of 37.61% are best-in-class metrics that any analyst would pause on. Debt is declining steadily, and the company has maintained positive free cash flow to equity across all three years: ₹1.25 crore (FY24), ₹0.42 crore (FY25), and ₹2.20 crore (FY26).
One caveat: FY25 saw a 15.51% revenue decline before the FY26 rebound. This is the nature of project-based businesses; revenues are lumpy, tied to customer capex cycles, and can swing sharply year to year.
The competitive landscape and the valuation puzzle
SpectraA operates in the India Beer & Malt Spirit Equipment Market, valued at $204 million in 2024 and projected to reach $302 million by 2032 at a 5.1% CAGR. The market is fragmented; dominated at the top by Praj Industries (22.8% market share), with Alfa Laval, GEA Group, and Prodeb occupying smaller but established positions. SpectraA sits in the "Emerging Leaders" category alongside a handful of regional players.
The valuation conversation is where things get complicated. Praj Industries is the only listed peer cited in the RHP, and it trades at a P/E of 258.89x. The two companies are not truly comparable: Praj Industries has revenues of over ₹3,160 crore versus SpectraA's ₹101 crore. Using Praj's P/E as a benchmark could make SpectraA's pricing look conservative, but that framing would be misleading. Investors should evaluate the IPO price on SpectraA's own earnings trajectory and growth potential rather than anchoring to an outlier peer multiple.
The fresh issue proceeds are earmarked for three purposes: ₹11 crore for capex at a new Jaipur manufacturing facility, ₹6.47 crore for repayment of term loans, and ₹9.5 crore for working capital. The balance goes toward general corporate purposes.
Red flags you cannot ignore
No research note is complete without an honest look at the risks, and SpectraA has a few that deserve attention.
The verdict
SpectraA Technology Solutions is a niche, technically capable company riding genuine structural tailwinds; India's premiumisation of alcohol, the craft beer boom, and growing demand for energy-efficient brewery infrastructure. The financial metrics are genuinely strong: a near-quadrupling of EBITDA margins, exceptional return ratios, and a clean deleveraging trend.
But this is an SME IPO, and the risks are proportionate. The governance lapse, lumpy revenue profile, and the absence of a truly comparable listed peer make this a high-conviction, high-risk proposition.
For investors who understand the brewery equipment space and are comfortable with the SME segment's liquidity constraints, SpectraA's growth trajectory makes it worth a close look. For everyone else, patience until post-listing price discovery may be the wiser path.
Disclaimer: This AI-generated analysis, based on RHP/DRHP information, is for informational purposes only. Investors should conduct due diligence and consult financial advisors before making investment decisions. Past performance does not guarantee future results, and all investments carry inherent risks including potential loss of principal.