German Green Steel and Power Limited has arrived at Dalal Street with a 100% book-built IPO. The name sounds exotic, but this is an Ahmedabad-headquartered, Gujarat-based, vertically integrated iron and steel manufacturer focused on thermo-mechanically treated (TMT) bars. It was incorporated in 2008 as Haq Enterprises Private Limited, it went through two more names before finalizing its current name in January 2024.
The IPO at a glance
The IPO comprises a total issue up to ₹304 crore. This includes a fresh issue of ₹290 crore and an offer for sale of ₹14 crore. The price band is set at ₹132 to ₹139 per share, and the IPO opened for subscription on September 25 and closes on September 29, 2026.
What does the company actually do?
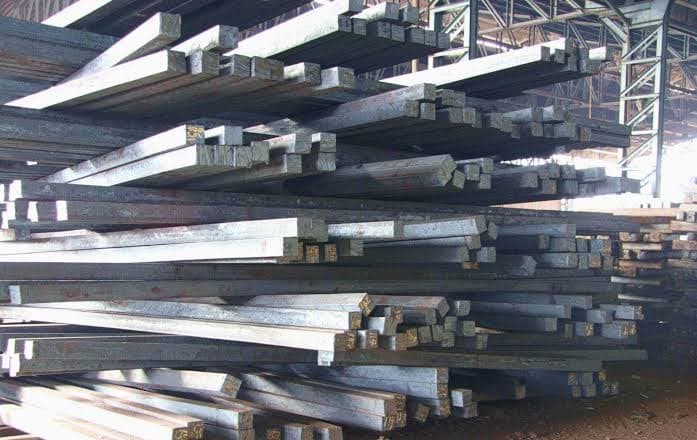
German Green Steel manufactures TMT bars, mild steel (MS) billets and sponge iron. The "German" in its brand refers to Thermex quenching technology, a thermo-mechanical treatment process developed by HSE Germany. The company uses it under Thermex licence and trademark agreements with H&K Rolling Mill Engineers Private Limited. The process improves the yield strength, ductility, bendability and weldability of the bars. The company's edge lies in its vertical integration. Most regional steel players buy its raw materials- billets and sponge iron, from the open market.
It operates two manufacturing facilities in Gujarat:
- Samakhiyali, Kutch: a fully integrated facility making sponge iron, MS billets and TMT bars.
- Viramgam: run through its material subsidiary, German TMT Private Limited. The company has captive power from waste heat recovery and a thermal power plant. A 25.20 MW hybrid wind-solar project is under way in Bharuch, of which a 16.20 MW hybrid plant is already commissioned.
TMT bars contributed 78.74% of FY26 revenue. The company sells through distributors (37.57% of FY26 revenue), dealers (20.89%) and institutional customers.
The numbers: strong growth, improving margins
Revenue grew at a CAGR of 21.91% over FY24–FY26. EBITDA grew at 45.07% and PAT at 38.47% over the same period.
| Metric | FY24 | FY25 | FY26 |
|---|
| Revenue from operations (₹ Cr) | 1,129.78 | 1,507.57 | 1,678.98 |
| EBITDA (₹ Cr) | 79.33 | 116.81 | 166.96 |
| EBITDA margin | 7.02% | 7.75% | 9.94% |
| PAT (₹ Cr) | 41.67 | 59.94 | 79.89 |
| PAT margin | 3.69% | 3.98% | 4.76% |
| Debt-to-equity | 1.13x | 1.18x | 0.79x |
| ROCE | 18.62% | 15.91% | 19.31% |
| RoNW | 23.67% | 20.40% | 18.86% |
Basic and diluted EPS for FY26 is ₹14.91, and NAV per share is ₹77.76. Return on net worth has slipped each year, even as margins and ROCE improved.
Capacity utilisation is mixed rather than uniformly high. TMT bars improved to 87.79% in FY26 from 72.19% in FY25. Other lines slipped:
| Product | FY26 | FY25 |
|---|
| Sponge iron | 95.21% | 99.32% |
| MS billets (combined) | 79.44% | 83.43% |
| MS billets (Samakhiyali only) | 76.42% | 93.01% |
Debt-to-equity fell to 0.79x in FY26 from 1.18x in FY25, after rising from 1.13x in FY24. As of August 31, 2026, total outstanding borrowings were ₹344.13 crore, of which ₹310.97 crore was fund-based.
Valuation: what the RHP tells us
| Peer | P/E |
|---|
| MSP Steel & Power | 61.57x |
| Gallant Ispat | 27.80x |
| Beekay Steel Industries | 22.54x |
| Kamdhenu | 14.57x |
| VMS TMT | 8.92x |
The peer average P/E stands at 35.25x. German Green Steel’s (FY26) P/E at the upper end of the price-band stands at 9.32x. The company's RoNW of 18.86% is well above most peers, which range from 3.28% to 19.77%. The weighted average RoNW is 20.17%, and the weighted average EPS is ₹12.57.
What the IPO money will be used for
Of the net proceeds, ₹226.33 crore will fund capex at the Samakhiyali facility. The total project cost is ₹348.14 crore. The plan includes:
- Sponge iron capacity rising from 66,000 to about 1,48,500 MTPA.
- MS billet capacity rising from 2,14,500 to 4,12,500 TPA, an increase of about 92%.
- TMT bar capacity rising from 1,81,500 to 3,46,500 MTPA.
- The 25.20 MW hybrid wind-solar plant, to cut reliance on the grid.
Of the project cost, ₹62.41 crore had been deployed by August 31, 2026, and ₹59.40 crore is to come from an HDFC Bank term loan. The net proceeds are planned to be deployed as ₹122.53 crore in FY27 and ₹103.81 crore in FY28.
Only ₹7.70 crore goes to debt repayment. That is 2.48% of the company's fund-based borrowings of ₹310.97 crore. General corporate purposes take the remainder; not exceeding 25% of gross proceeds.
One caveat is that none of the objects have been appraised by any bank, financial institution or independent agency. There is no outside validation of the cost estimates.
The red flags you cannot ignore
The income tax search and seizure. The Income Tax Department carried out search and seizure operations from January 17 to 19, 2023. They covered the company's erstwhile registered office, its promoters, some promoter group members, group companies and both manufacturing facilities. Documents, digital data, cash and jewellery were seized, and some documents have still not been released. Prohibitory orders on the Samakhiyali facility have been lifted. The company has since received orders quantifying tax demands, and its appeals are pending before the Commissioner of Appeals.
A Supreme Court petition over an acquired plant. The company bought a distressed steel unit of Global Hi-tech Industries Ltd at Bhuj, Kutch, through a Debt Recovery Tribunal auction that concluded on June 30, 2023 for ₹23.28 crore. Prudent ARC Ltd has filed a Special Leave Petition (No. 36554/2025) in the Supreme Court. It challenges the Bombay High Court order of December 9, 2025, which dismissed its challenge to the auction. The RHP says the asset is not integral to the current capacity expansion plans, but failure to secure possession could still hurt operations.
Extreme promoter concentration. Promoters and the promoter group hold 96.63% of pre-offer capital (promoters 81.28%, promoter group 15.35%). The company has only 45 shareholders, of whom 38 are public holders with 3.37% between them.
A board short on listed-company experience. Most directors have never served on the board of a listed company. Apart from one independent director, none of them have. The RHP admits this limits the guidance they can give after listing.
Other risks:
- Customer concentration: the top 10 customers contributed 50.62% of FY26 revenue, and the largest alone contributed 10.67%.
- Related-party dealings: these include Iraki Enterprise Limited and the Kaavyaratna group entities.
- Trademark and licence disputes: H&K Rolling Mill Engineers sent cease-and-desist notices in 2021 and 2025 over the Thermex and TMX trademarks. The company and its subsidiary then signed fresh licence agreements in November 2025 and January 2026, and renamed the subsidiary from German TMX to German TMT. The RHP warns that similar claims could arise again.
The bottom line
German Green Steel and Power is an operationally solid business. Revenue is growing at over 20% a year, EBITDA margin has improved from 7.02% to 9.94%, and leverage has come down in FY26. The expansion plan is large and the TMT bar business is running at high utilisation. However, billet and sponge iron utilisation slipped in FY26, and RoNW has declined for three years.
The governance questions are material. They include the income tax search and pending tax demands, a Supreme Court petition on an acquired plant, near-total promoter ownership, a board with little listed-company experience, and a history of trademark disputes with its technology licensor. The expansion capex has also not been independently appraised.
Disclaimer: This AI-generated analysis, based on RHP/DRHP information, is for informational purposes only. Investors should conduct due diligence and consult financial advisors before making investment decisions. Past performance does not guarantee future results, and all investments carry inherent risks including potential loss of principal.