Vesuvius India Ltd has received a Buy rating with a target price of ₹560, representing significant upside potential from its current market price of ₹389.60. According to reports from The Hindu BusinessLine, the recommendation is based on the company's strong market position and growth prospects in the refractory industry. The broker has initiated coverage on Vesuvius India with this Buy rating, valuing the company at a 30x CY28E P/E multiple.
The company holds a 50-55% market share in India's refractory market, positioning it as one of the leading players in the sector. As reported by The Hindu BusinessLine, Vesuvius India is part of the Vesuvius plc Group and provides flow control solutions, advanced refractories and comprehensive refractory management services to steel, foundry, aluminium, cement and other high temperature industries. The company has built a strong product portfolio and technical service network as an early mover in localising flow control manufacturing in India, supporting its leadership position in the domestic market.
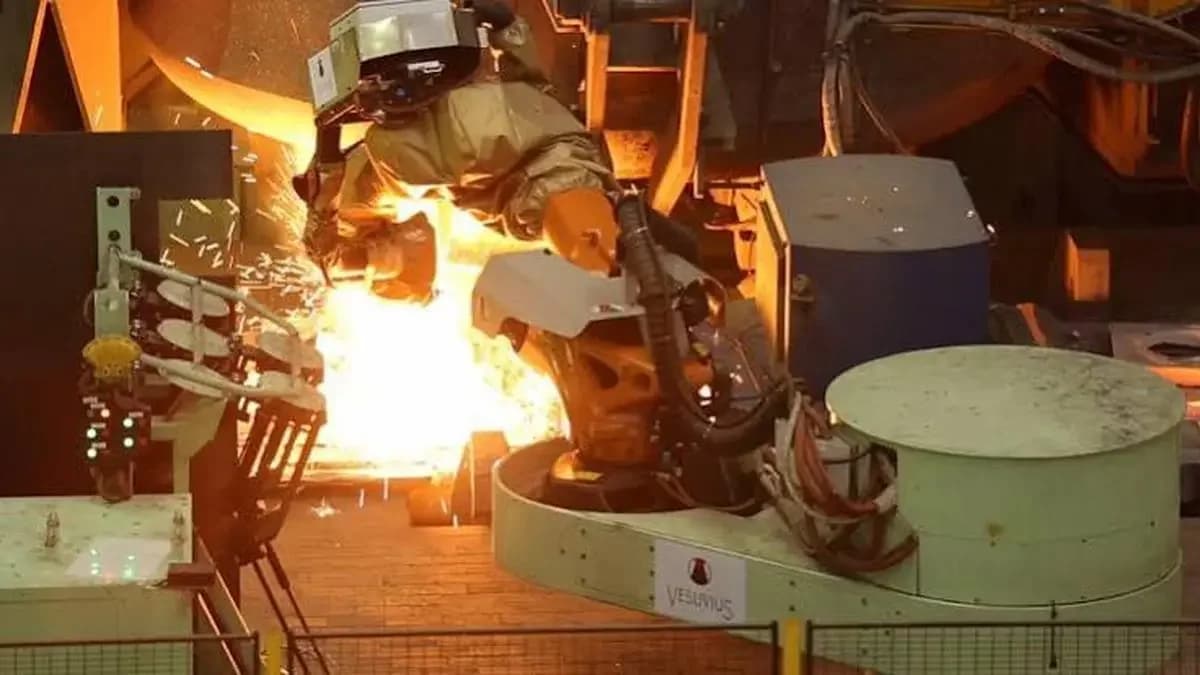
The India refractory market revenue is expected to grow at a CAGR of 9.9% from 2026 to 2033, providing a favorable backdrop for the company's growth. According to the broker report, Vesuvius India's revenue is projected to grow at approximately 12% CAGR over CY25-CY28E, supported by sustained growth in the steel industry and increased demand for refractory and flow control products. The considerable contribution from the steel sector is expected to drive the company's performance in the coming years.
The company's service-led model and provision of total refractory solutions are expected to support recurring revenue through maintenance and related services. As reported by The Hindu BusinessLine, the ramp up of new capacities is expected to support normalisation and improvement of margins, contributing to the company's overall financial performance. This service-oriented approach is expected to provide stable revenue streams and enhance the company's competitive position in the market.
The broker has initiated coverage on Vesuvius India with a Buy rating, valuing the company at a 30x CY28E P/E multiple. According to the report, this valuation reflects the company's strong market position, growth prospects, and the expected margin improvements from capacity expansion and service model enhancements. The premium valuation is justified by the company's leadership position, strong product portfolio, and the favorable industry outlook for the refractory market.