According to PL Capital's latest research report, the brokerage expects its ports coverage universe to report revenue growth of 16.2% year-on-year in Q2 FY27, alongside Ebitda growth of 14.1% and net profit growth of 5.1% YoY. However, quarter-on-quarter performance is expected to show sequential decline with revenue, Ebitda, and net profit growth of -1.2%, -2.6%, and -8.0% respectively. The positive YoY growth is supported by resilient container and international cargo volumes, though this is partially offset by weakness in select commodities and weather-related disruptions in India.
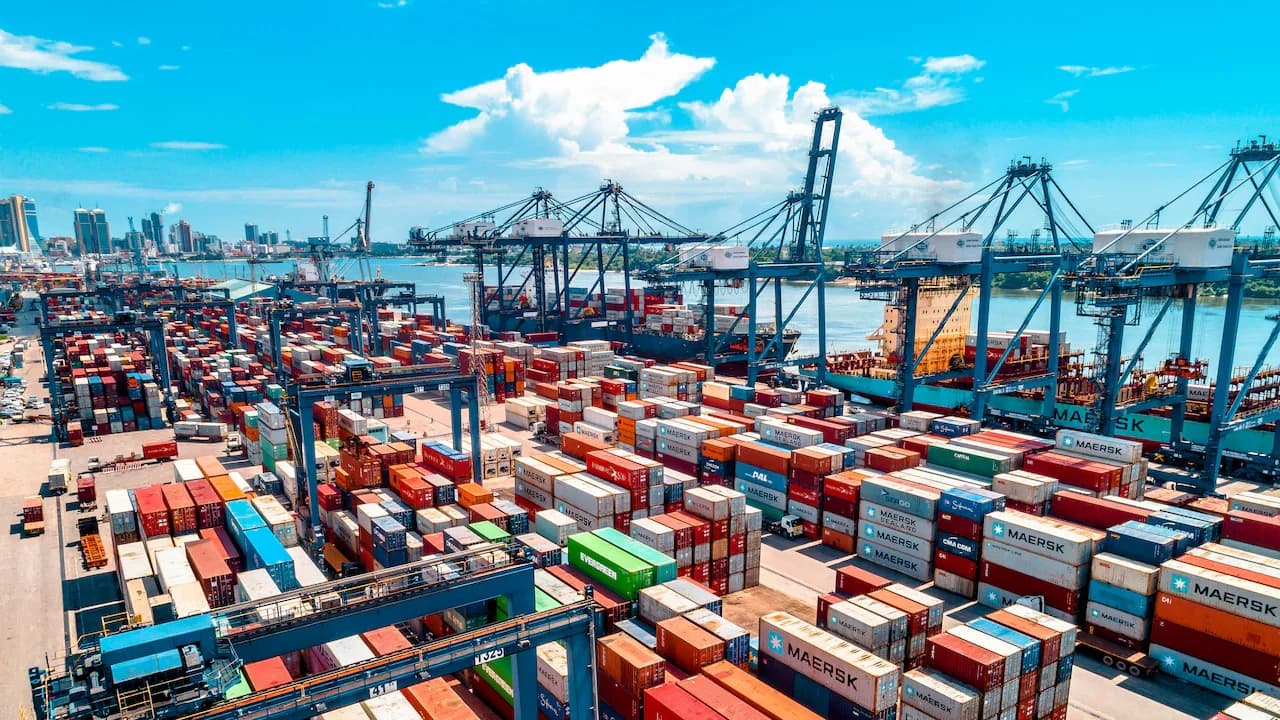
As reported by PL Capital, Adani Ports continued robust volume performance during the quarter, aided by sustained container throughput and healthy international volumes across CWIT and NQXT. However, cyclone-related disruptions on the East Coast and moderation in liquid and imported thermal coal volumes negated domestic cargo to some extent. The company is expected to retain its FY27 volume outlook, with stronger international volumes providing improving visibility into H2 FY27.
According to the brokerage report, JSW Infrastructure is expected to report subdued consolidated volume growth as Fujairah remains impacted and the group's steel unit ramps up post debottlenecking. However, domestic operations are expected to deliver higher single-digit volumes aided by Jaigarh and Dharamtar facilities, while improving logistics business should support consolidated revenue growth.
PL Capital highlighted that H2 FY27 is likely to see gradual normalisation in cargo flows, although elevated freight rates and weather-related disruptions remain near-term headwinds. The brokerage remains constructive on the ports sector, supported by rising containerisation, integrated logistics, and healthy capacity expansion. Importantly, both Adani Ports and JSW Infrastructure are expected to retain their FY27 volume outlook, with planned capacity additions remaining on track to support medium-term growth.