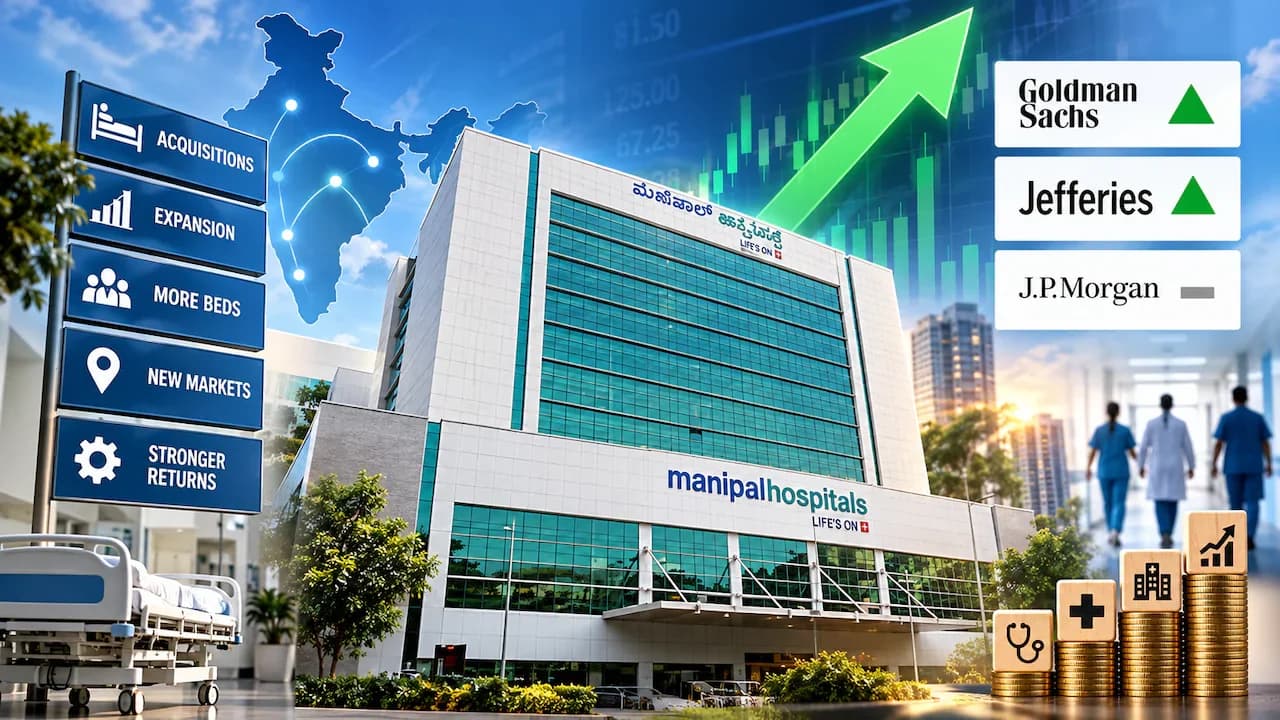
Max Healthcare Institute has received dual buy ratings from leading brokerages, with Anand Rathi issuing a buy rating with target price of ₹1,200 and ICICI Securities recommending a buy rating with target price of ₹1,300. As per Anand Rathi's research report dated November 03, 2026, the brokerage has revised its target price from ₹1,220 earlier while maintaining a bullish outlook on the stock. According to ICICI Securities's report dated November 04, 2026, they maintain a buy rating with an unchanged target price of ₹1,300, reflecting strong confidence in the company's operational performance and expansion strategy.
Max Healthcare Institute delivered robust quarterly results with consolidated revenue growing 18% year-on-year to ₹30.6 billion and EBITDA rising 18% YoY. As reported by Anand Rathi, the sequential growth rebound was driven by new bed additions and seasonality factors. According to ICICI Securities, the company delivered strong operating performance in Q2FY27 with revenue and EBITDA growth of ~18% YoY each, driven by a 13% uptick in occupied bed days and 8% growth in ARPP. The company's Max Labs/Max@Home revenue came in at ₹660/860 million (up 24/37% YoY) while overall occupancy remained flat at 77% and ARPP rose 8% YoY to ₹231,000.
The company has been on an aggressive brownfield bed expansion spree, adding 758 beds across its network in the last one year - representing a 16% addition to its capacity. As reported by ICICI Securities, the company is further optimising its payor mix by reducing exposure scheme-based patient at mature hospitals while international patient flows remain strong (+33%). The company's board approved significant capital expenditure of ₹4.15 billion for 209 brownfield beds across existing hospitals, including 85 beds at MSSH, Noida, 60 beds at MSSH, Vaishali and 64 beds at BLK Max. Additionally, the board approved ₹930 million capex for redevelopment and clinical capacity enhancement at Max Super Speciality Hospital, Sec-128, Noida. Most notably, the company approved revision of project cost to ₹11 billion and timeline for completion of the proposed ~525-bed hospital at Sec-56, Gurugram to April 2027.
The research firms have raised their FY27E/FY28E EBITDA estimates to factor in better margins with the newly operationalised brownfield beds. According to ICICI Securities, they raise their FY27E/FY28E EBITDA by ~1%/4% respectively. The research firm maintains its FY27E and FY28E EBITDA estimates unchanged and expects EBITDA to grow at 19% CAGR over FY26-29E. As reported by Anand Rathi, they introduce estimates for FY29 and roll forward valuation to 1HFY29E, maintaining their buy rating with a revised target price of ₹1,200. The valuation is based on hospital/laboratory business at 30x/25x 1HFY29E EV/EBITDA multiples, reflecting confidence in the company's expansion strategy and operational improvements across its network.