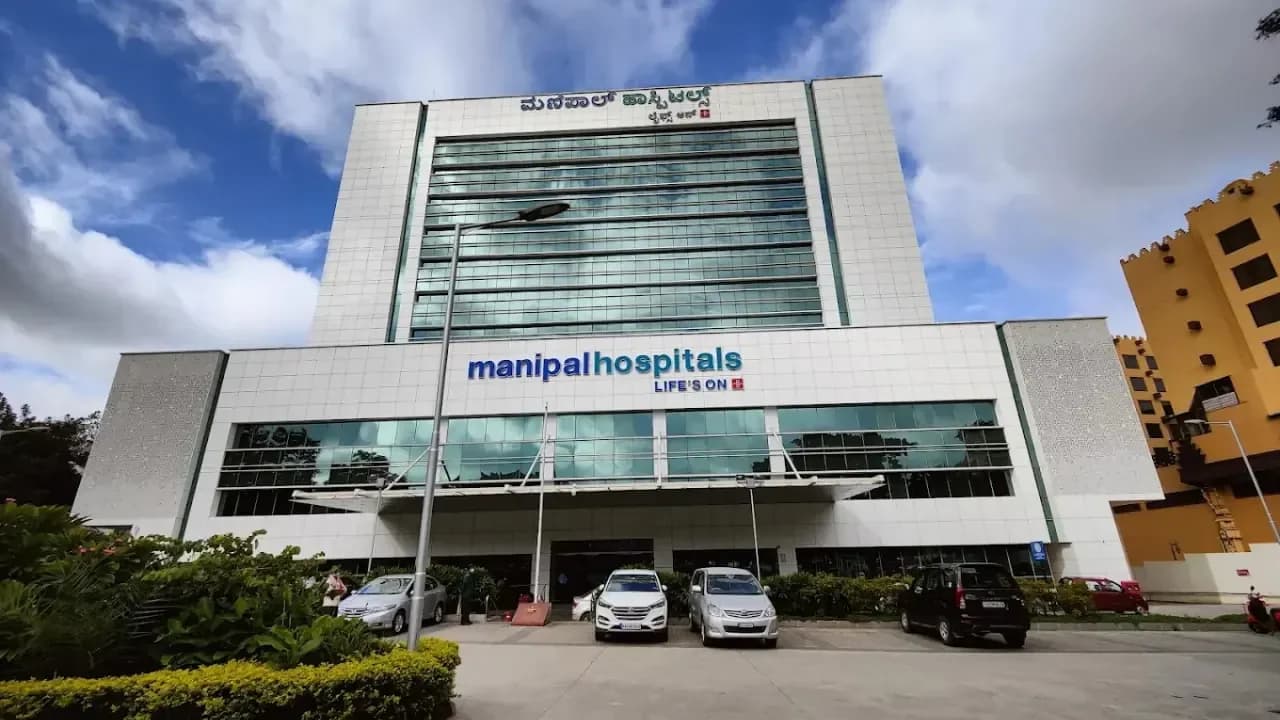
Kotak Institutional Equities has initiated coverage on Manipal Health Enterprises with an 'Add' rating and a fair value of ₹825, implying approximately 8% upside from current market prices. According to reports from Kotak Institutional Equities, the brokerage expects the company to deliver around 16% sales CAGR and 19% EBITDA CAGR over FY26-29E. The hospital chain currently operates 13,140 beds across 50 facilities with a growing presence across key metros and a pipeline of nearly 2,400 new beds.
The core of Kotak's investment thesis centers on Manipal's proven ability to acquire hospitals and improve their operating performance through a repeatable M&A playbook. As reported by Kotak Institutional Equities, the company has completed five acquisitions since FY2022, with Columbia Asia offering the clearest example of the strategy. Columbia Asia's sales increased around 2.5 times between FY21 and FY26, while margins expanded to 34% from 18%, aided by clinical upgrades and operating efficiencies. Similar improvements have been visible at Vikram, while AMRI is beginning to show signs of a turnaround. The key differentiator is whether the integration process itself has become a capability — standardising clinical protocols, procurement, and occupancy improvement at each acquired site.
Manipal plans to increase its capacity by around 18% to 15,566 beds by FY30E, with nearly 2,400 new beds coming online. According to Kotak Institutional Equities, around 40% of these additions will be in its core markets of Bengaluru, Kolkata and Pune. The brokerage expects higher footfalls across existing and new beds, alongside greater contribution from complex procedures, to drive operating leverage. For AMRI, Medica and Sahyadri combined, Kotak expects around 14% sales CAGR and 22% EBITDA CAGR over FY26-29E. The 19% EBITDA CAGR against a 16% sales CAGR implies margin expansion, typically driven by occupancy improvements as beds are largely fixed costs.
Kotak expects Manipal to generate around ₹63 billion of cumulative free cash flow during FY27-29E, supporting deleveraging and improving return ratios. The brokerage estimates RoIC could reach around 13% by FY29E. Another important growth driver is Manipal's continued shift towards its CONGO-R mix, which currently stands at around 65%. Kotak expects this to support an approximately 8% ARPOB CAGR between FY26 and FY29E.
For valuation, Kotak has assigned a 27x September 2028E pre-Ind AS 116 EBITDA multiple, in line with its valuation for Apollo's hospital segment and most peers. The brokerage has applied a slight discount to Max, citing lower RoCEs. However, Kotak identified acquisition-related integration issues and lower RoCEs versus peers as key risks, particularly given Manipal's aggressive M&A-led expansion strategy. The hospital group's transformation from a single-city base into a national network demonstrates the success of this acquisition-focused growth model.