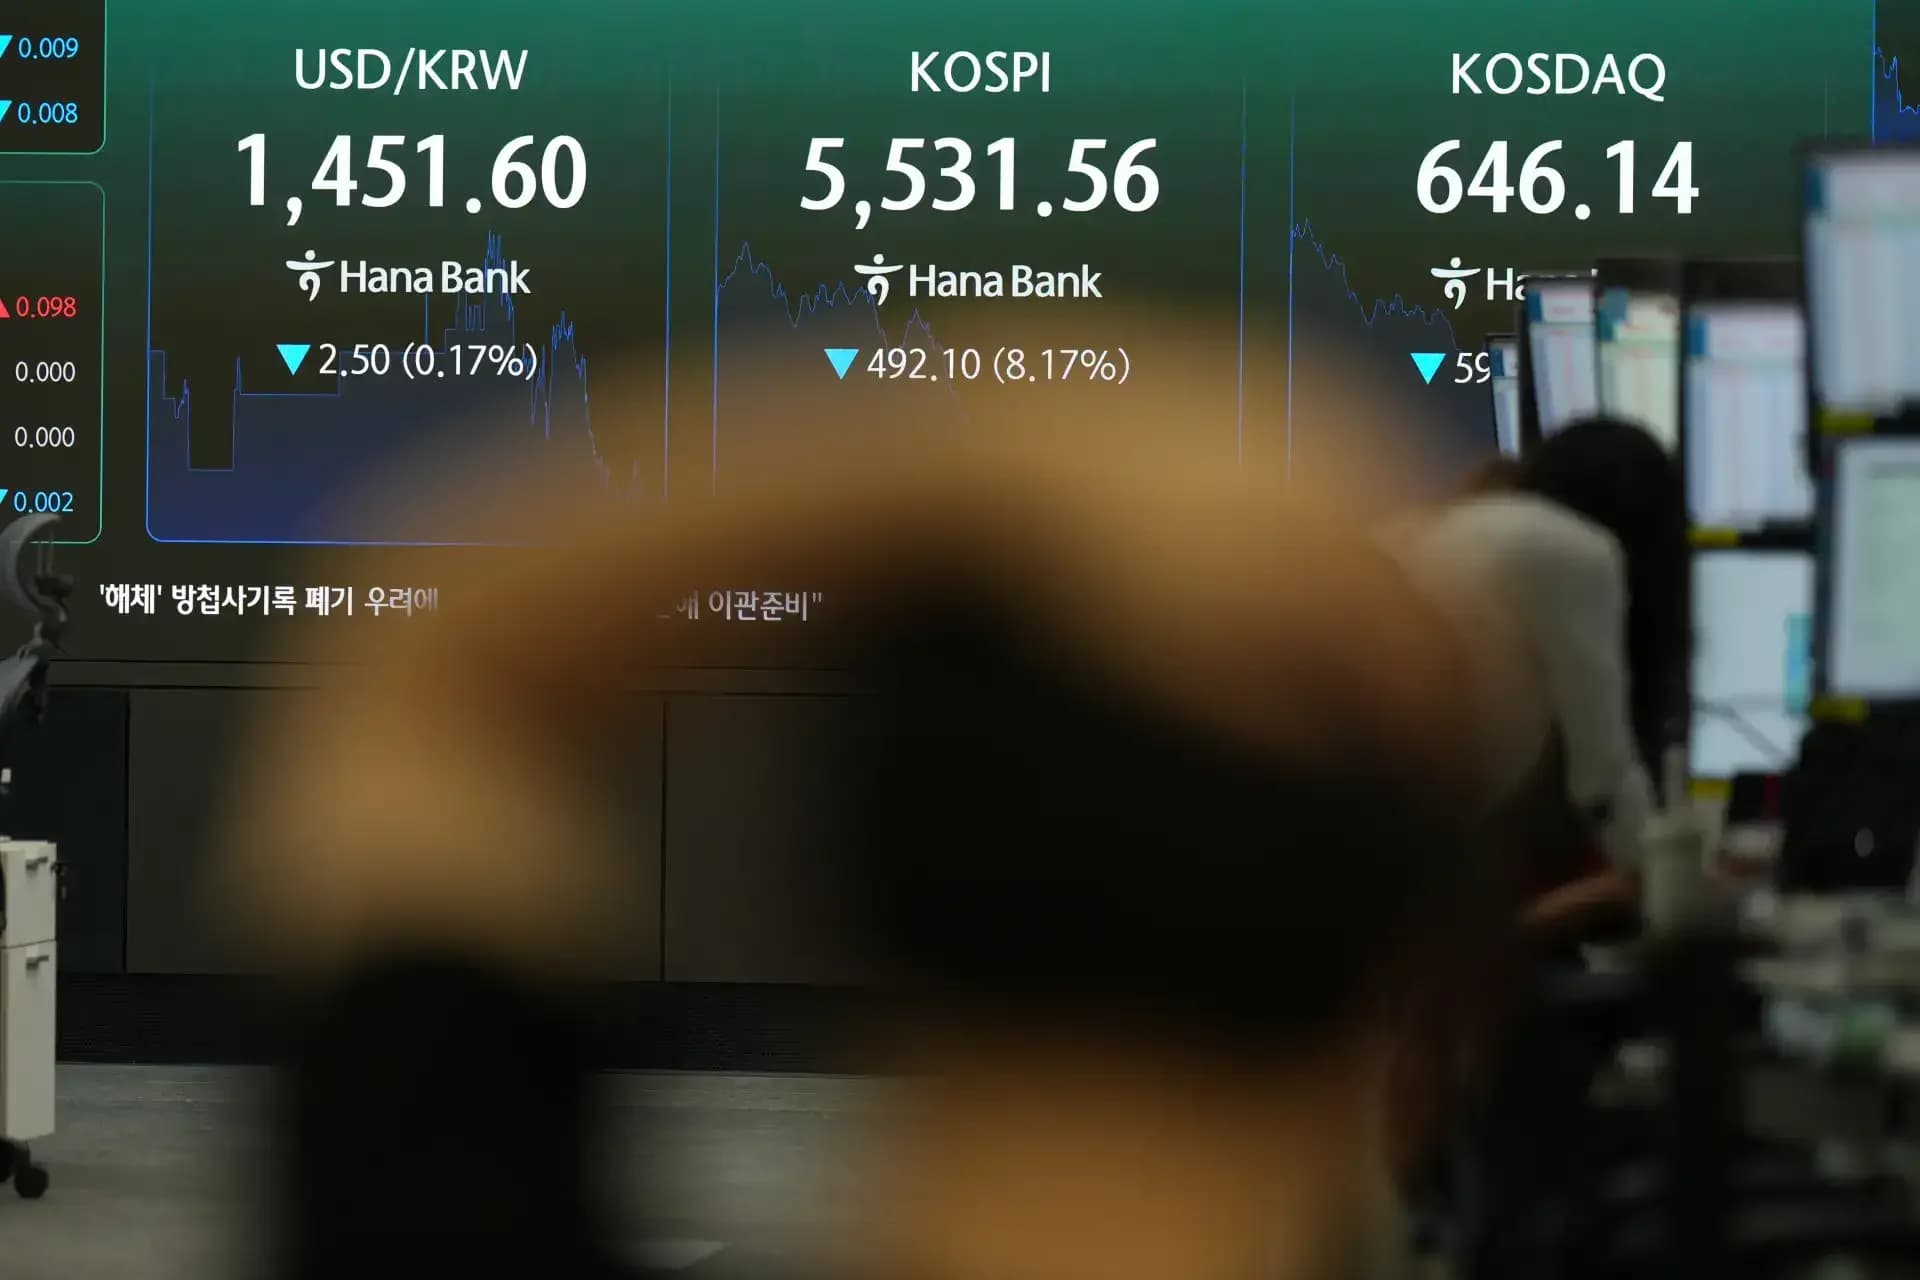
Asia's next leverage-driven market crash may be brewing as margin debt across the region reaches concerning levels, according to latest analysis from Reuters. South Korea's brutal summer equity rout saw the KOSPI collapse 39% from June 22 to July 30, driven by the rapid buildup and subsequent unwinding of margin loans held by retail investors. When tech shares tumbled in June on AI capital spending concerns, falling collateral values triggered widespread margin calls, with brokers dumping shares from over a million leveraged accounts and creating a self-reinforcing cascade that erased billions in market value. India's Margin Trading Facility book has surged from just over $1 billion at the end of 2020 to $16.3 billion as of August 31, while China's outstanding margin balance has tripled from $68 billion at the beginning of 2019 to $200 billion as of August 31.
Nomura has issued a stark warning that the AI boom may be masking growing US risks, as heavy global exposure to dollar assets leaves markets vulnerable to an AI-driven shock. According to Nomura's latest special report, the ratio of US net international investment position (NIIP) liabilities to the sum of all net creditor nations' NIIP assets has surged to 80%, which the international brokerage believes marks a vivid measure of how concentrated the Rest of World savings have been funnelled into USD investments. While noting that US NIIP liabilities increased and USD appreciated during the great financial crisis and pandemic, Nomura explained it is more plausible now for US NIIP liabilities to decrease. The brokerage warned that a setback in AI could trigger a sharp correction in US equities, weaken the dollar and potentially turn into a broader global risk-off event.
Market analysts are now warning that financial markets are beginning to reflect pre-blowup mania conditions, according to recent reports from Market Factors. The warning comes as U.S. margin debt is climbing faster than mortgage or credit card debt, a potential sign of mania that deserves investor attention. Richard Bernstein Advisors warns that margin debt growing much faster than credit card or mortgage debt represents a concerning trend under John Kenneth Galbraith's framework of moving from promising innovation to greed through leverage and derivatives. The rise of leveraged, single stock ETFs compounds these concerns, as investors face the risk of margin calls resulting in forced selling of previously market-leading stocks.
Gabriela Santos, J.P. Morgan Asset Management's chief market strategist for the Americas, warned that true diversification from the artificial intelligence trade is now difficult to achieve. According to reports from CNBC, Santos explained that the AI capital expenditure buildout has grown so large that its effects now touch nearly every asset class, from equities to fixed income and private markets. Speaking on CNBC's "Closing Bell Overtime," she emphasized that investors can remain bullish on AI while still needing to think carefully about portfolio construction, including position sizing, leverage, and diversification. The summer's momentum unwind particularly affected AI-linked stocks in July and continued into August, as reported by CNBC, with Santos noting that this episode underscored key lessons for AI-bullish investors about careful portfolio construction.
J.P. Morgan built an AI factor basket to test how closely assets and portfolios track the broader AI trade, with results showing most assets now moving together. According to Santos' analysis, genuine diversification is mostly limited to treasuries, gold, core real estate, and European equities. This scarcity echoes recent warnings about a broader stock-bond diversification collapse, as historically bonds reliably cushioned portfolios during recessions. However, Santos noted that the dynamic has changed due to competition for capital, supply shocks, inflation, and rate volatility. Scotiabank strategist Hugo Ste-Marie noted in a recent research report that bonds have been "hard to love" lately with fixed income ETFs performing poorly, making money market funds and GICs alternative diversification options.
J.P. Morgan Private Bank's Global Investment Strategist Weiheng Chen and Head of Investment Strategy, Asia Joshua Lewin argue in their August 28, 2026 report that emerging markets are experiencing a structural shift after fifteen years of underperformance. According to their analysis, EM equities outperformed developed markets by more than 12 percentage points in 2025 and have risen 24% versus 10% for developed markets through the first half of 2026. The strategists conclude this represents "not merely a cyclical rebound, but a broader structural shift" driven by AI supply-chain positioning, commodity scarcity, and governance reform. Taiwan and South Korea occupy indispensable roles in the global semiconductor supply chain, with Taiwan producing the vast majority of world's most advanced logic chips and South Korean firms dominating global high-bandwidth memory production.