HDFC Securities has reiterated its Buy rating on Honasa Consumer Ltd. with a September 2027 target price of ₹550, based on 5x EV/sales valuation. According to reports from NDTV Profit, the brokerage's valuation reflects sector-wide de-rating, with the current target price implying approximately 40x EV/EBITDA and 49x P/E ratios. The recommendation is supported by the company's strong growth visibility and disciplined execution strategy.
The brokerage expects 25% overall revenue growth for Honasa Consumer in Q2 FY27, with ~12% operating profit margin. As reported by NDTV Profit, with a broadening addressable market and continued focus on disciplined execution, HDFC Securities anticipates the company will sustain both its growth trajectory and margin expansion over the medium term. The projections are supported by the company's strategic focus on offline distribution channels.
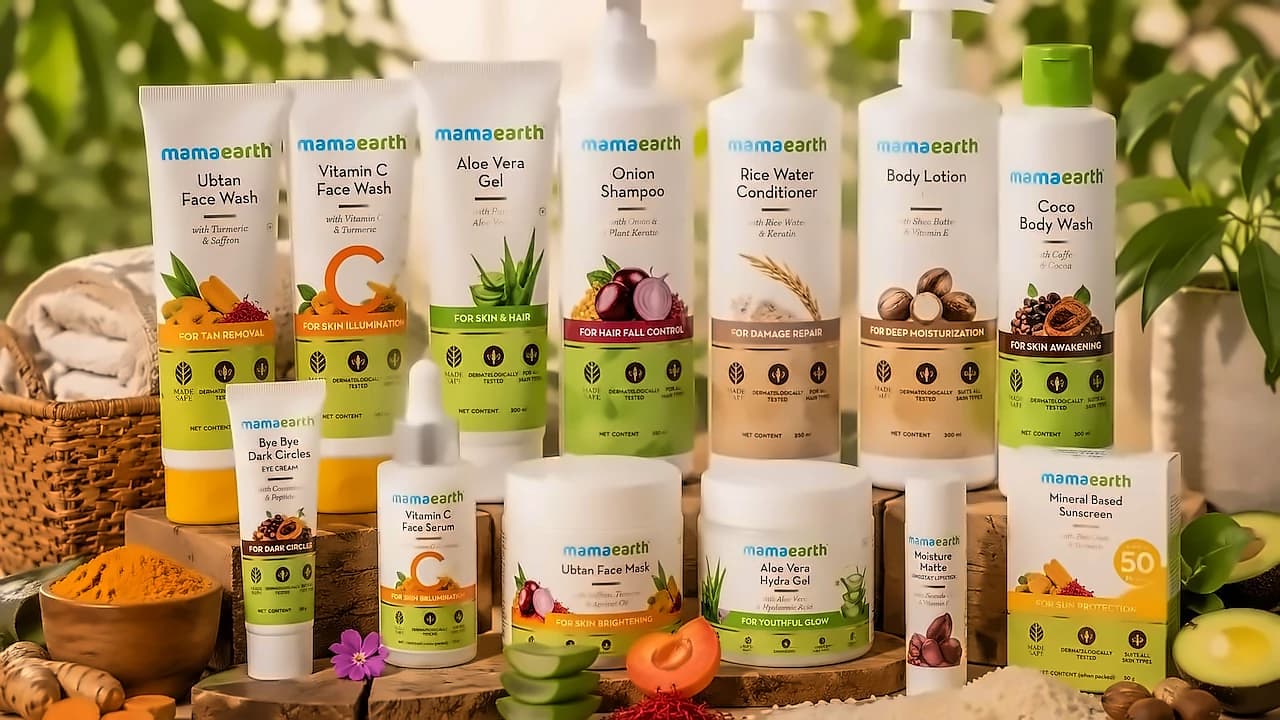
The brokerage's channel checks with distributors across key markets highlight that offline execution remains central to the next phase of growth. According to the report, the offline channel accounts for 35% of the business, while its contribution for Mamaearth is higher at 50%+. Management is targeting 3x expansion in direct reach over three years, with current efforts focused on boosting throughput at existing outlets.
The emphasis has shifted to tightening the primary–secondary growth parity and maintaining distributor inventory discipline at ~30 days. As reported by NDTV Profit, although certain hygiene issues remain, they are being progressively resolved through stronger trade inputs, more competitive schemes, and greater parity with online-led offerings. This operational focus supports the company's growth strategy and market positioning.
Despite positive brokerage recommendations, Honasa Consumer shares experienced a 5% decline following recent block deals, as reported by The Economic Times. The stock currently trades at a reference price of ₹466, with multiple brokerages maintaining varying ratings. Equirus has forecast 314 basis points of EBITDA margin expansion to 13% by FY29E, driven by operating-expense optimization, while Antique Stock Broking has suggested a 'Buy' call with a target of ₹616 and JPMorgan maintains an 'Underweight' rating with a ₹410 target.